


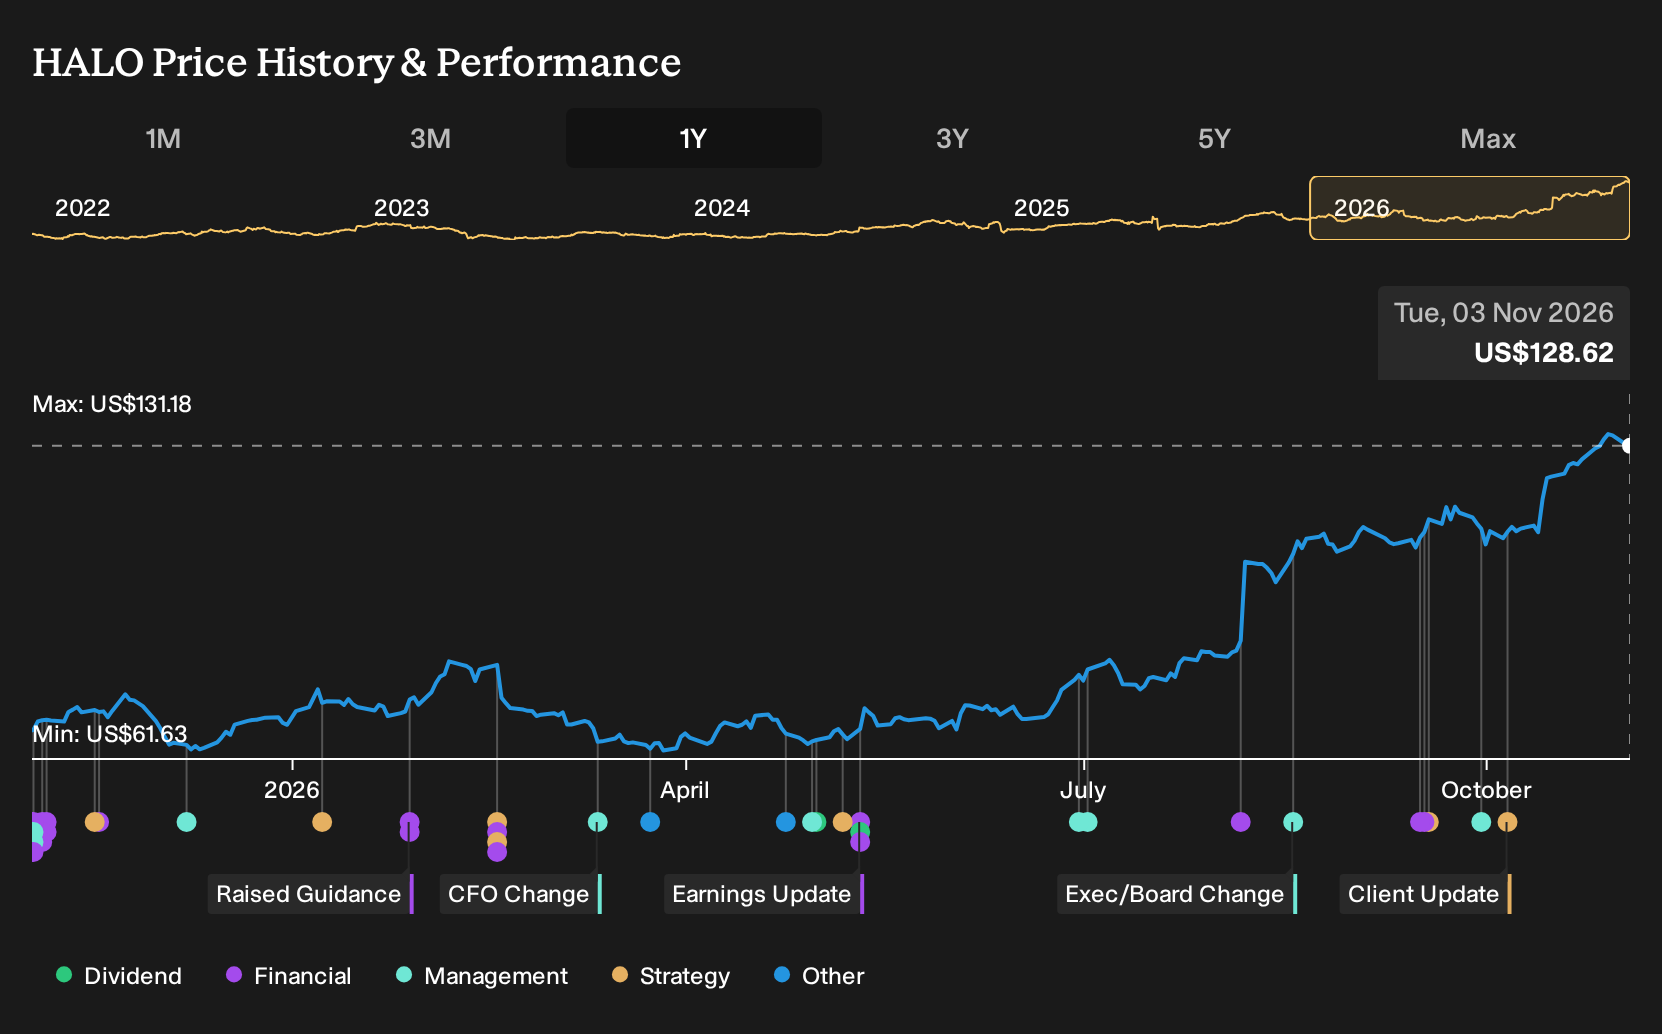
If you had been weighing Halozyme Therapeutics in late 2025, the split between bullish and bearish analyst targets already hinted at a real fork in the road. Holding Halozyme Therapeutics over the past year would have returned 88.3%, including dividends. If you were deciding on 3 November 2025 whether to buy into a royalty rich drug delivery specialist amid concerns over ENHANZE dependence and future pricing pressure, what information on record really mattered most?
This theme extends beyond Halozyme Therapeutics. See which of 34 healthcare AI stocks may still merit a closer look.
The Two Halozyme Therapeutics Stories Investors Had To Compare
The shares cost US$66.2 at the start of the period, and the central question was whether Halozyme Therapeutics could keep turning ENHANZE into long life royalty power or whether that reliance would backfire.
The bullish Narrative pointed to a Fair Value of US$71.67, a price implied by expectations for 18.7% annual revenue growth and profit margins rising toward 54.2% within three years as subcutaneous partnerships expanded.
The bearish Narrative anchored on a Fair Value of US$49.57 and focused on ENHANZE dependence, with concerns that patent expiry and pricing pressure could erode royalty economics and compress future earnings.
What The Evidence Did To The Halozyme Therapeutics Debate
Halozyme Therapeutics put hard numbers behind the royalty rich story. Revenue moved from US$325.7m in Q2 2025 to US$481.0m in Q2 2026, and net income also rose, which backed the bullish focus on partner uptake. Net margin slipped from 50.7% to 47.8%, so the period still asked questions about just how far profitability can stretch. Overall, the evidence cut both ways.
The lesson is simple. When a thesis hangs on high margin royalties, investors can track both the top line and the net margin trend, and test whether each new licensing deal or volume lift actually preserves that margin across several reporting periods.
What Halozyme Therapeutics' Run Already Prices In
Halozyme Therapeutics now trades at US$129 after an 88.3% gain over the past year, while this Narrative’s Fair Value sits below the current price based on its own framework.
The Narrative leans on ENHANZE, Hypercon and Surf Bio building a long royalty stream, so you would be assuming continued partner uptake despite pricing pressure and competing subcutaneous platforms.
"The main thing that has to go right is that Halozyme Therapeutics continues to convert demand for subcutaneous formulations and high concentration auto injectors into new, durable royalty agreements while managing margin pressure and growing competition in hyaluronidase."
Not everyone reads the same price the same way. → See the lower figure this Narrative lands on, and how it gets there
Halozyme Therapeutics And A Parallel Bet
Halozyme Therapeutics leans on royalties from partners that need better treatment formats. Your next question is whether other businesses are chasing similar patient demand.
One large drug maker is building an obesity and diabetes portfolio. It is pushing injectables, oral drugs and combinations that aim to reshape weight and blood sugar control.
Alongside that, it is adding cancer, neuroscience and immunology therapies. Those treatments give it extra revenue pillars beyond weight loss medicines.
If these newer medicines gain traction, the firm could spread its earnings base across many chronic conditions. That is a very different way to tap the same long term health trends Halozyme targets.
One Narrative has already put a figure on it. → Uncover the company trading 15% below one Narrative's Fair Value
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com