


Par Pacific Holdings (PARR) is back in the spotlight after a third quarter update that combined strong earnings, a first profitable renewables quarter, and an agreement to exit its Laramie Energy stake.
Par Pacific Holdings has given investors a bumpy ride in recent weeks, with the share price down 4.36% over the past week and 15.14% over the past month to US$71.28, even though the 90-day share price return is still positive at 1.95% and the year-to-date share price gain sits at 99.00%.
That kind of pullback after strong third quarter earnings, the first profitable renewables quarter and the agreed Laramie Energy exit suggests some short term profit taking. At the same time, the 1-year total shareholder return of 75.87% and 5-year total shareholder return of 336.50% show how much the longer term holders have already benefited from the story so far.
Scan beyond Par Pacific Holdings and see how other energy names with strong recent earnings and cleaner balance sheets stack up using our handpicked list of solid balance sheet and fundamentals (23 results)
Par Pacific Holdings now trades well below the average analyst target despite strong recent earnings and a profitable renewables quarter. Is that a sensible safety margin, or market caution that has gone too far ahead of fair value estimates?
Most Popular Narrative: 24% Undervalued
Par Pacific Holdings last closed at $71.28, while the most followed narrative anchors fair value at $93.29. This frames the recent pullback as a gap between the current price and modeled long term earnings power.
Persistently tight refining markets in the Pacific Basin, supported by reduced Persian Gulf and Russian exports, conservative Asian refinery runs and protectionist trade policies, keep Par Pacific Holdings highly exposed to strong refined product cracks that could continue to support revenue, EBITDA and earnings power.
See why 21 investors see Par Pacific Holdings as 24% undervalued.
Result: Fair Value of $93.29 (UNDERVALUED)
Still, the Par Pacific Holdings narrative frays quickly if regional refinery outages lift costs again or if its sizeable tax shield erodes more quickly than expected.
Find out about the key risks to this Par Pacific Holdings narrative.
Another View On Par Pacific Holdings: Cash Flows Say Overvalued
Analyst targets present Par Pacific Holdings as undervalued, yet the SWS DCF model points in the opposite direction. On a future cash flow basis, PARR at $71.28 screens above an estimated value of $63.24, so the stock appears overvalued using this measure. Which yardstick do you rely on more for your own work?
Look into how the SWS DCF model arrives at its fair value.
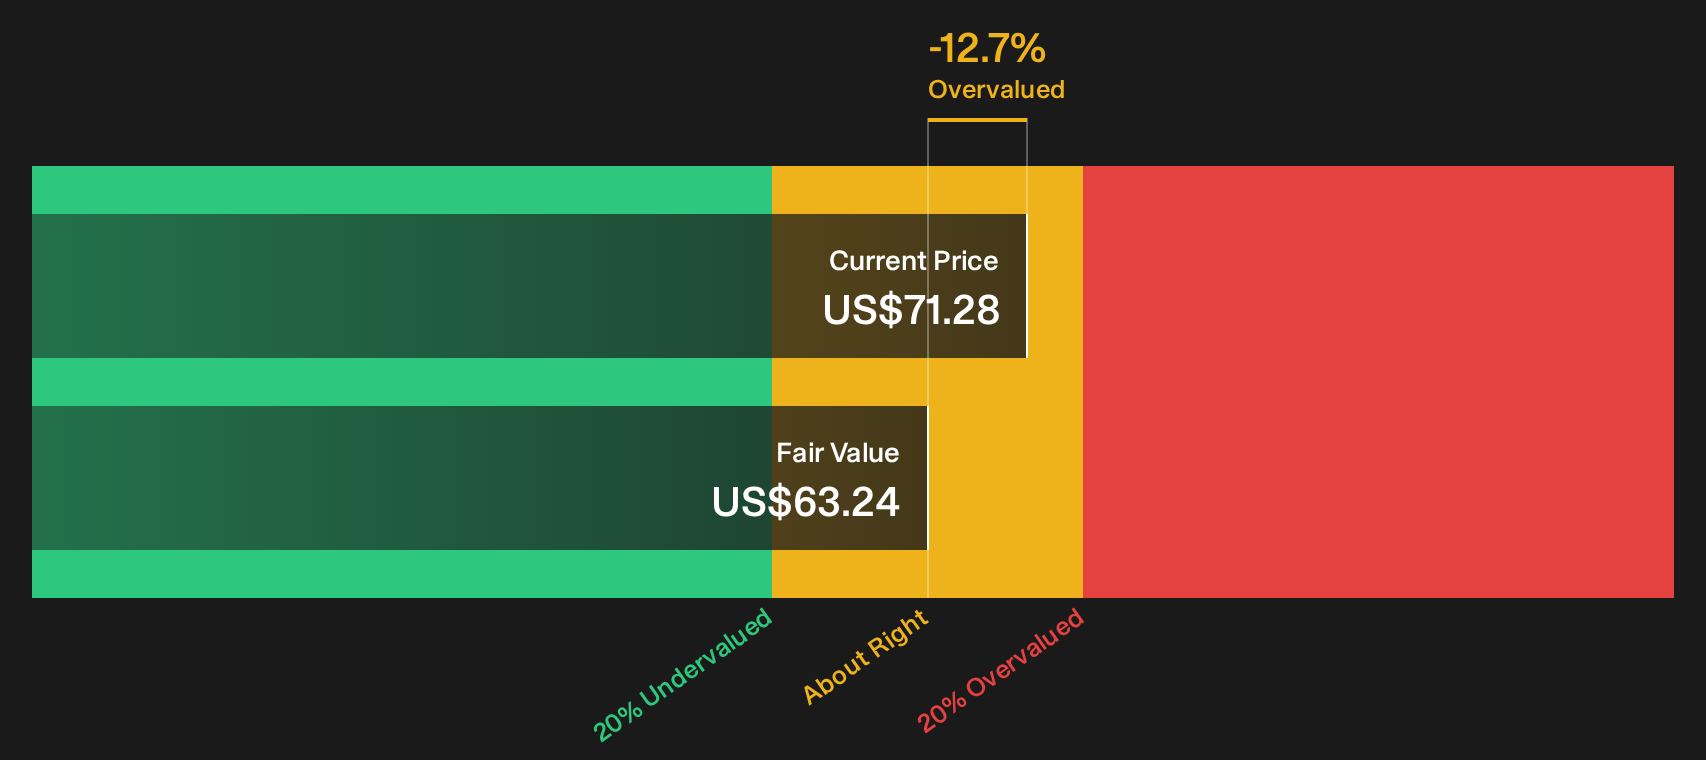
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out Par Pacific Holdings for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 35 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
Mixed signals on Par Pacific Holdings can leave the story feeling split, so move quickly, test the numbers yourself, and weigh both sides using the 4 key rewards and 2 important warning signs.
Looking for more investment ideas beyond Par Pacific Holdings?
If the Par Pacific Holdings setup has your attention, do not stop here. Broaden your watchlist now or you risk missing the next compelling setup.
- Target resilient balance sheets by scanning companies with steady fundamentals through our list of solid balance sheet and fundamentals (23 results).
- Hunt for quality at a discount by reviewing the 35 high quality undervalued stocks that currently match disciplined valuation filters.
- Lock in potential income streams by assessing stocks in the 4 dividend fortresses that meet your yield and stability criteria.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com