


New York-based American International Group, Inc. (AIG) provides insurance products for commercial, institutional, and individual customers in North America and internationally. Valued at a market capitalization of $43.1 billion, the company operates through North America Commercial, International Commercial, and Global Personal segments.
AIG stock has lagged behind the broader market over the past year, growing 2% compared to the S&P 500 Index’s ($SPX) 10.5% surge. Moreover, in 2026, the stock has declined by nearly 5.9%, underperforming the SPX’s 10.6% gain.
Zooming in further, the State Street Financial Select Sector SPDR ETF (XLF) has risen 9.7% over the past year, rallying the stock. In 2026, XLF has grown 4.4% and has also outpaced the stock.
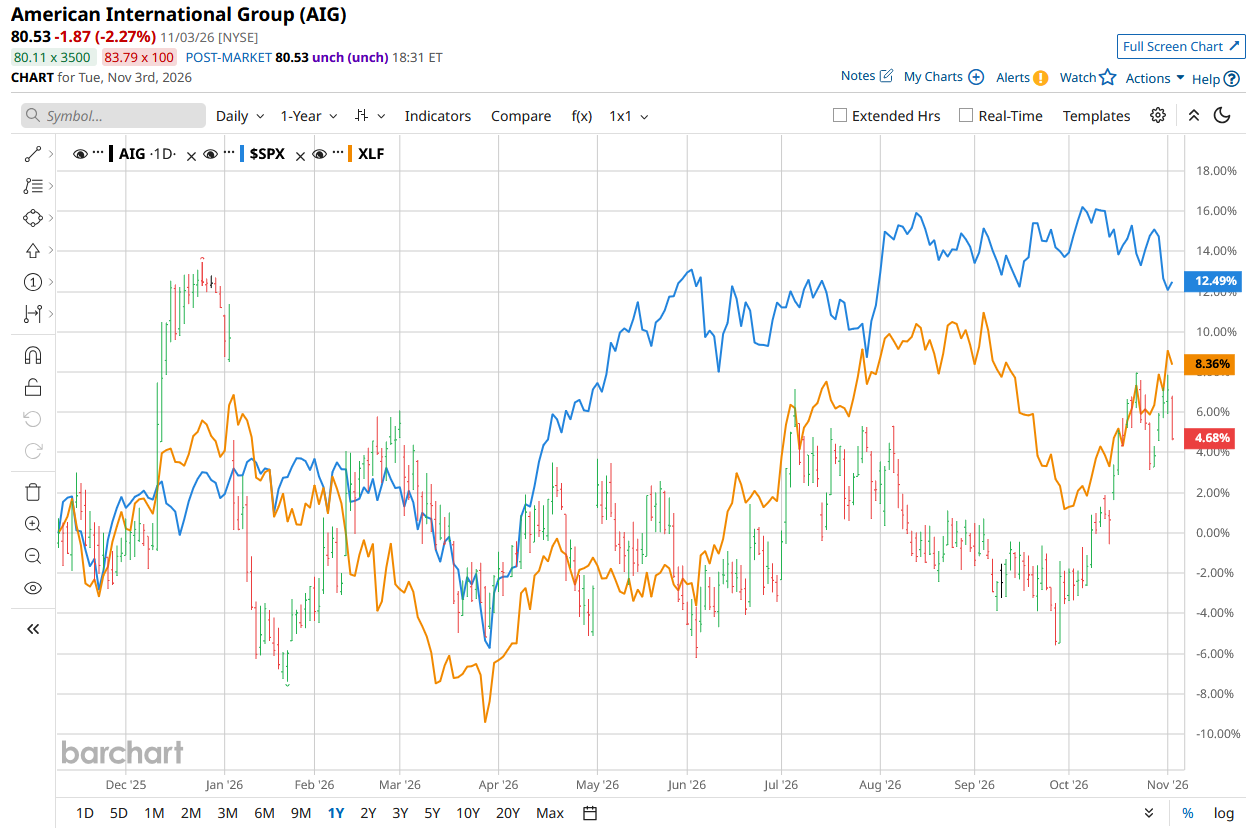
AIG released its Q3 2026 earnings in the previous trading session, and the stock declined nearly 2.3% following the release. AIG’s revenue for the quarter amounted to $7.5 billion and surpassed the Street’s estimates. Moreover, its adjusted EPS also topped the consensus estimates and came in at $2.06. Despite posting cheery results, the market’s reaction to the earnings was bearish overall.
For the current year, which ends in December, analysts expect AIG’s EPS to rise 13.8% to $8.07 on a diluted basis. The company surpassed the consensus estimate in each of the last four quarters.
Among 24 Wall Street analysts covering AIG stock, the consensus is a “Moderate Buy.” That’s based on six “Strong Buy” ratings, two “Moderate Buys,” and 16 “Holds.”
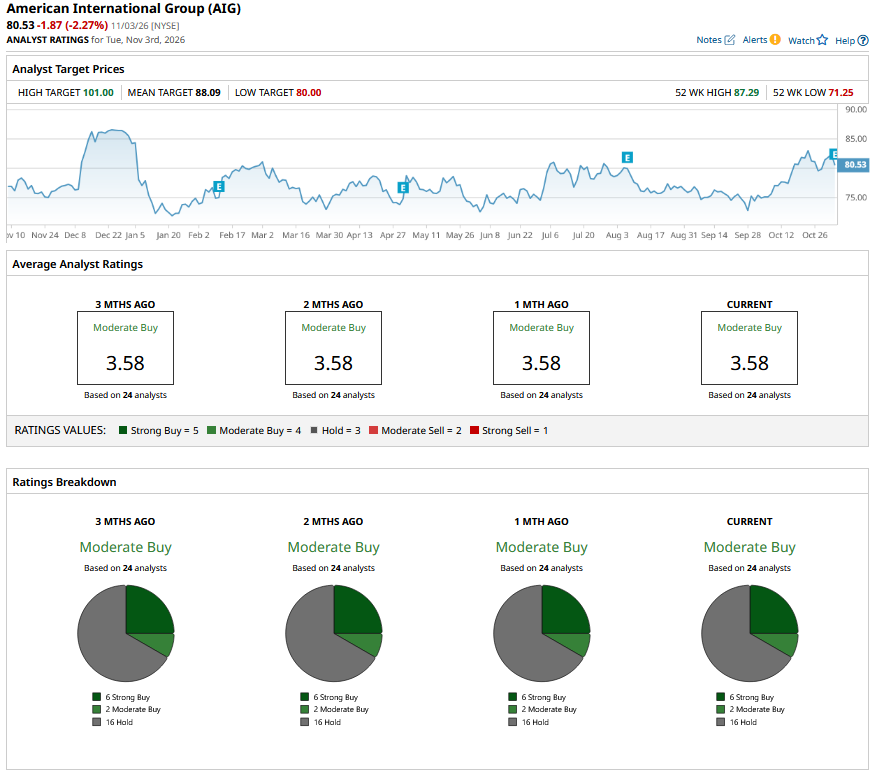
The configuration has remained largely unchanged over the past months.
On Oct. 8, Barclays analyst Alex Scott maintained a “Hold” rating on American International Group and set a price target of $81.
AIG’s mean price target of $88.09 offers a 9.4% upside compared to the current market price. Its Street-high target of $101 implies a robust 25.4% upside from current levels.
On the date of publication, Aritra Gangopadhyay did not directly have a position in any of the securities mentioned in this article. All information and data in this article is solely for informational purposes. For more information please view the Barchart Disclosure Policy here.