


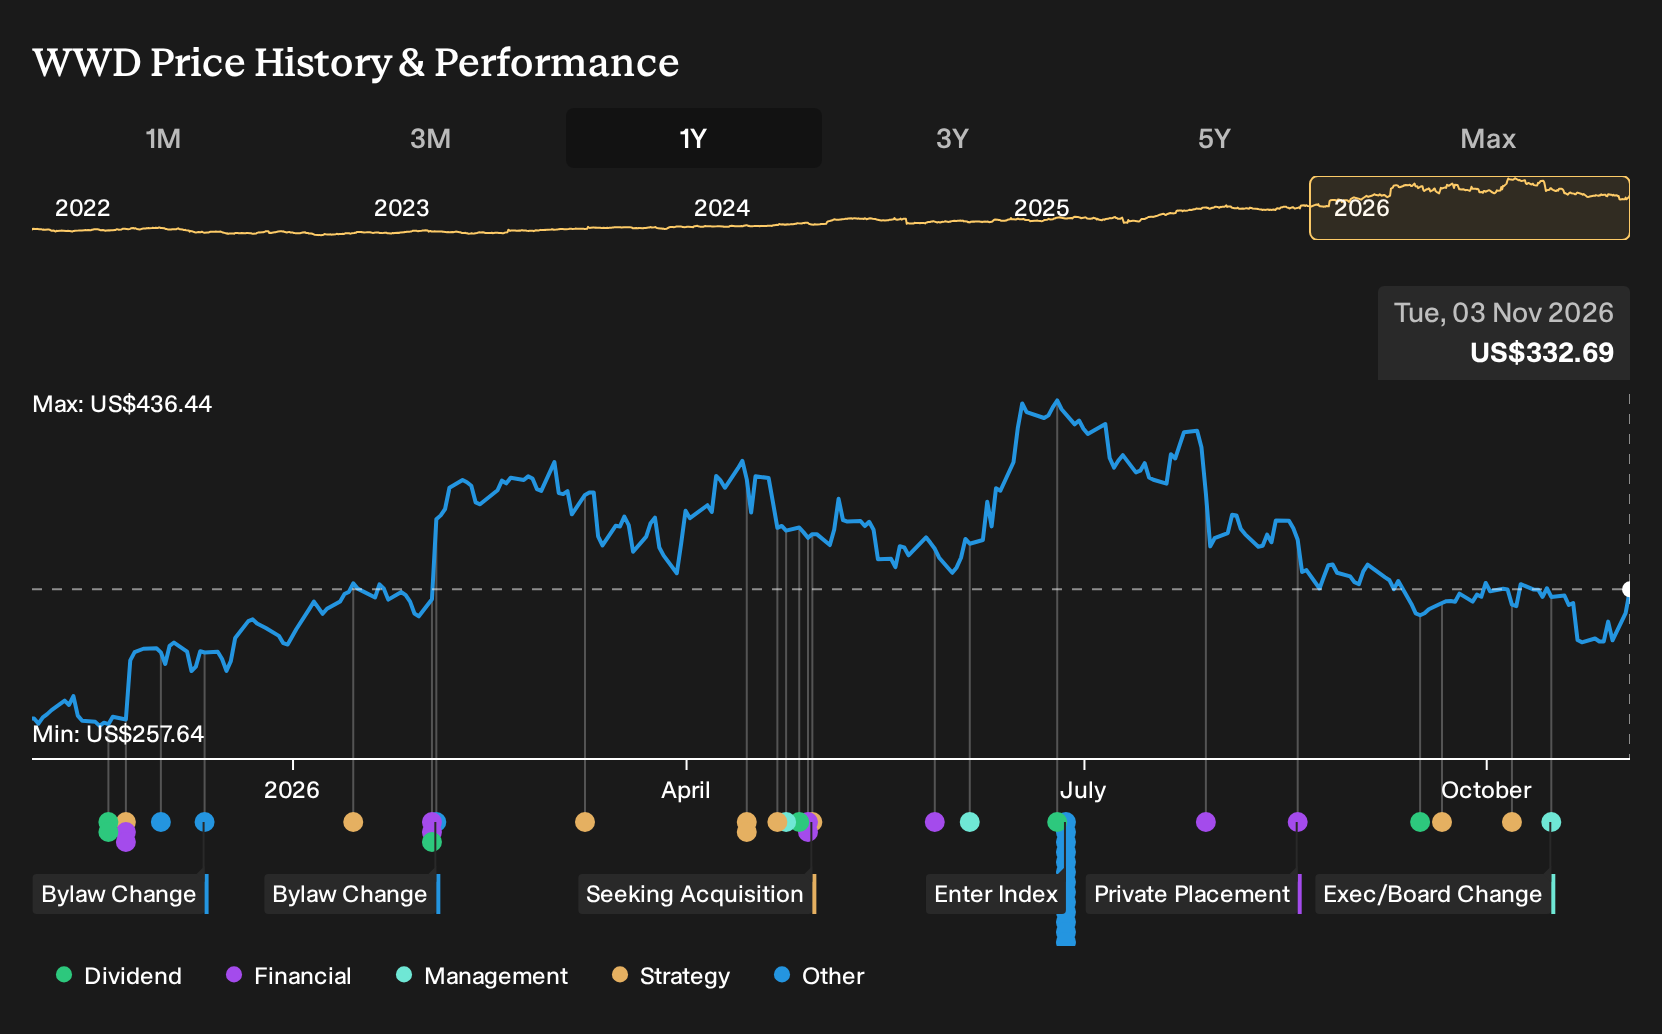
Woodward’s recent quarter put something very tangible on the table. The business crossed US$1b in sales and raised full year guidance, while also returning cash through buybacks and dividends. Holding Woodward over the past year would have returned 27.3%, including dividends. If you were deciding back on 2025-11-03, before these results and upgrades hit the wires, what would you have needed to believe about contracts, margins, and capital discipline to justify buying?
A Narrative on Simply Wall St is one investor's written case for a company, with its growth, margin and multiple assumptions spelled out. Those assumptions imply an estimated Fair Value.
Woodward has already moved. Pinpoint other ways to investigate the theme among 93 robotics and automation stocks.
The Two Woodward Stories Investors Had To Weigh
The shares cost US$262 at the start of the period, so any case for Woodward had to stack up against that entry point.
The bullish Narrative put Fair Value at US$291, 11% above the start price. It leaned on Woodward’s role in cleaner aerospace platforms and assumed revenue growth of 7.2% with profit margin reaching 13.6% and a future P/E of 39.4x.
The bearish view set Fair Value at US$245, 6% below the start price. It focused on geopolitical risk and customer concentration, yet still assumed 7.5% revenue growth, margin at 13.9%, and a future P/E of 25.5x.
What The Woodward Results Put To The Test
Woodward clearing US$1b in quarterly sales and lifting full year guidance backed the optimistic case that contracts, demand, and execution could support higher revenue and wider profitability. The Q3 2025 to Q3 2026 figures show sales rising from US$915.4m to US$1.11b, net income increasing, and net margin moving from 11.8% to 13.2%. The evidence mainly supported the optimistic case.
The key lesson is simple. When a thesis hangs on margin expansion and capital discipline, track net margin and cash returns against the original assumptions and decision date, not just headline revenue.
What Woodward’s Run Leaves You Paying For Today
Woodward shares now trade at US$333, after a 27.3% gain over the past year from US$262. The selected bullish Narrative places its Fair Value above that level and ties the case to how pricing, automation and service execution feed through to earnings and cash generation.
Instead of broad optimism, the Narrative asks whether today’s price fully credits Woodward’s capacity projects, automation rollouts and LEAP aftermarket layers continuing without eroding operating discipline. That is the concrete bet a buyer at US$333 has to examine.
"The main thing that has to go right is that Woodward sustains strong demand across aerospace and industrial markets while executing factory expansions, product moves and ERP and automation rollouts without eroding its operating discipline."
The price and this Narrative do not agree. → Uncover what this Narrative says Woodward is actually worth
Where Woodward’s Theme Extends Next
Woodward anchors your attention on aircraft and turbines. The same push for efficiency is reshaping data halls full of AI hardware.
Those facilities do not just need electricity. They need power systems and cooling gear that keep racks within tight thermal limits.
A different industrial player focuses on that backbone. It designs and maintains infrastructure that manages heat, power and uptime for large computing sites.
The angle is simple. As AI capacity needs reshape data centre design, this behind the scenes supplier’s importance also shifts.
The case is on the record, with the assumptions it rests on. → See the Narrative that values this company 73% above its price
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com