


MaxLinear (MXL) is back in the spotlight after third quarter sales reached US$218.06 million with net income of US$28.9 million, alongside fourth quarter revenue guidance of US$240 million to US$260 million.
MaxLinear’s recent results and higher fourth quarter guidance came amid a sharp pullback in the shares, with a 30 day share price return of down 39.61% and a 7 day move of down 14.33%. At the same time, the 1 day gain of 4.30% suggests some momentum returning after the earnings release and new credit facility. Despite that volatility, the year to date share price return of 245.60% and a 1 year total shareholder return of 346.72% show that investors who held through the swings have seen very strong gains. However, the 5 year total shareholder return of down 5.43% highlights how recent optimism contrasts with a weaker longer run record.
Spot similar semiconductor rebounds and contrasting pullbacks by scanning our curated list of 53 AI infrastructure stocks that are riding demand for high-speed connectivity and data throughput.After MaxLinear’s sharp pullback and huge one year rebound, the real tension is simple. Is most of the easy upside already in the rear-view mirror, or do the current numbers still leave room on the table?
Most Popular Narrative: 32% Undervalued
Against MaxLinear's last close of $63.97, the most followed narrative anchors fair value at $94.55. This implies a sizeable valuation gap built on data center and AI optical demand assumptions rather than recent share price swings.
Accelerating demand for high-speed data center optical interconnects and next-generation PAM4 DSP solutions (Keystone and Rushmore), supported by robust design win momentum with major module makers and hyperscale customers, positions MaxLinear to capture a significant share of growing global data/AI infrastructure spend, likely driving meaningful revenue growth from late 2025 through 2027.
See why 18 investors see MaxLinear as 32% undervalued.
Result: Fair Value of $94.55 (UNDERVALUED)
Still, the MaxLinear story can change quickly if broadband and connectivity demand weakens again or if fierce pricing pressure in semiconductors erodes margins faster than bullish models assume.
Find out about the key risks to this MaxLinear narrative.
Another View: MaxLinear Looks Expensive On Sales
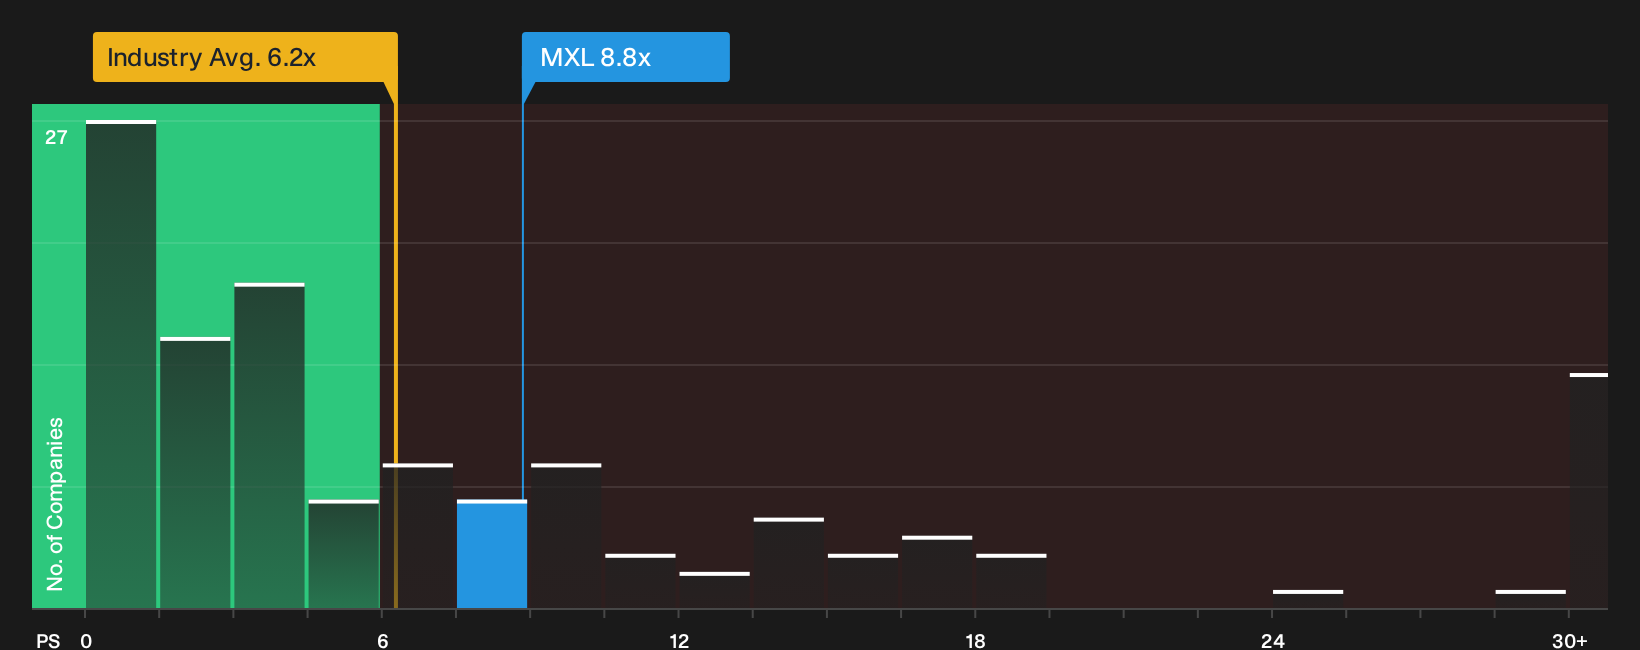
On the flip side of that 32% undervalued story, MaxLinear’s current P/S of 8.8x sits above both the US Semiconductor industry at 6.2x and peers at 8.1x, even though the fair ratio sits higher at 10.1x. That pricing leaves less room for error if sentiment cools again.
For a closer look at how this revenue based lens compares with the broader group and the fair ratio that the market could move toward over time, See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Mixed messages in MaxLinear's story so far. Act quickly: pull up the full data set, pressure test the bullish and cautious cases, then weigh the 1 key reward and 2 important warning signs.
Looking for more investment ideas beyond MaxLinear?
If MaxLinear has your attention, do not stop here. The same data engine that surfaces this story can help you uncover your next opportunity.
- Target potential upside by scanning a curated set of 19 high quality undiscovered gems that pair strong fundamentals with relatively low market attention.
- Prioritise resilience by filtering for 30 resilient stocks with low risk scores that score well on financial health and business stability.
- Focus on balance sheet strength by reviewing a list of solid balance sheet and fundamentals (23 results) that may better handle shocks without constant refinancing pressure.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com