


Take-Two Interactive Software (TTWO) is back in focus after fresh analyst surveys flagged strong teenager interest in Grand Theft Auto VI and its online mode, ahead of the company’s November 9 earnings release.
Despite Wednesday’s bounce, with Take-Two Interactive Software closing at US$194.99 after a 1-day share price return of 1.5%, momentum over the past few months has faded. The share price is down 17% over 90 days and the year-to-date share price return is down 22.5%, even as the 3-year total shareholder return of 43% still presents a stronger long-run picture ahead of the Grand Theft Auto VI catalyst.
Compare how Take-Two Interactive Software stacks up against other potential rebound candidates by scanning our curated list of 35 high quality undervalued stocks that combine quality with compressed sentiment.
Analyst targets sit far above Take-Two Interactive Software’s recent US$194.99 close, yet the market is clearly cautious after this drawdown. Is that discount mispricing Grand Theft Auto VI, or is it fairly flagging execution and earnings risk ahead?
Most Popular Narrative: 30% Undervalued
Against the recent close of $194.99, the most followed narrative on Take-Two Interactive Software points to a fair value of $276.97. This frames the current drawdown as a sizeable discount rather than just a stalled rally.
Take-Two sits at a genuinely pivotal inflection point. Over many years it has made heavy investment, including strategic acquisitions, and is approaching the moment of payoff. GTA VI could reshape its financial profile for the better half of the next decade.
See why 95 investors see Take-Two Interactive Software as 30% undervalued.
According to Clive_Thompson, the narrative fair value of $276.97 is built using a discount rate of 8.98%, which is relatively moderate for a large, established publisher with diversified platforms. The gap between that estimate and the recent price implies investors are weighing the earnings loss of $320.4m and the current lack of profitability more heavily than the expected turn to profits over the next three years.
The same storyline leans on analysts’ forecasts that earnings could grow 53.85% per year and that return on equity might reach 38% in three years, while revenue is modeled to expand at 10.7% annually. Those assumptions contrast with the recent past, where losses increased at an annual rate of 43.5% over five years and net income remained in the red. This helps explain why some holders have stepped back despite the GTA VI enthusiasm.
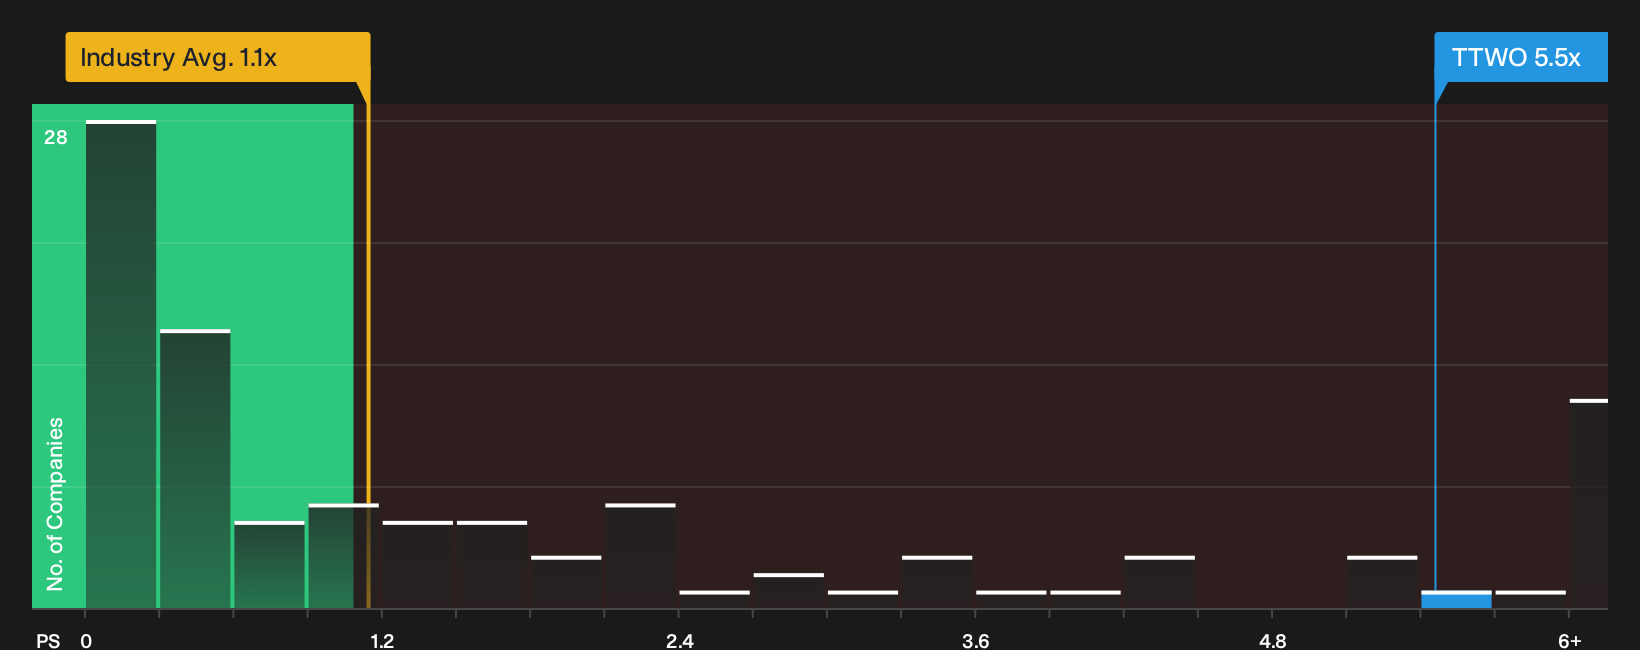
Risk is not ignored in this narrative. It flags that Take-Two Interactive Software is still unprofitable, carries funding that is fully made up of higher risk sources such as external borrowing, has recorded significant insider selling in the last three months, and trades on a P/S of 5.5x compared with an estimated fair P/S of 3.7x and a US Entertainment sector average of 1.1x. Those pressure points sit alongside strengths such as a seasoned management team with an average 16.1 years of tenure, a highly independent board, and analyst targets that sit more than 20% above the current share price with a strong level of agreement.
At its core, the popular narrative suggests the current share price embeds a cautious view on execution. The fair value estimate of $276.97 assumes Take-Two turns forecast growth in bookings and earnings into sustained profitability and strong equity returns. The November 9 earnings update and any detail on Grand Theft Auto VI monetisation will be important checkpoints for which side of that debate gains the upper hand.
Result: Fair Value of $276.97 (UNDERVALUED)
Still, the Take-Two Interactive Software story can break if the timing of GTA VI slips again or if ongoing losses of $320.4m signal deeper profitability issues.
Find out about the key risks to this Take-Two Interactive Software narrative.
Another View: What Multiples Say About Take-Two Interactive Software
There is a different message when you look at Take-Two Interactive Software through its P/S ratio. The stock trades at 5.5x sales compared with a fair ratio of 3.7x, while the US Entertainment group sits closer to 1.1x and direct peers average 2.3x. That sort of premium can reflect quality, but it also raises the question of how much future success is already in the price.
For investors weighing that premium, the valuation breakdown examines what has to go right for those sales multiples to hold up over time and how much margin for error remains at current levels. See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Opinions are mixed on whether the recent weakness in Take-Two Interactive Software represents a potential opportunity or a warning sign. Consider the full set of data points, then weigh the 3 key rewards and 1 important warning sign
Looking for more investment ideas beyond Take-Two Interactive Software?
If you want a clearer edge than just waiting on Take-Two Interactive Software’s next move, broaden your watchlist now with focused screeners built to surface specific opportunities.
- Target potential mispricings by scanning a curated 35 high quality undervalued stocks that combine solid fundamentals with sentiment that still looks compressed.
- Strengthen your core holdings by reviewing a list of solid balance sheet and fundamentals (23 results) so you are not caught off guard by fragile finances.
- Get ahead of the crowd by checking a 19 high quality undiscovered gems that highlight quality businesses the wider market may not be paying attention to yet.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com