


Tesla has become a far more complicated story than a pure electric vehicle play, with energy storage, chips and robotics all increasingly in the mix. Yet the market still values the business on a single share price that ultimately needs to be supported by its sales. After a period of mixed returns and headline grabbing projects, the open question is whether the current valuation of Tesla stock can be explained by what it is generating in revenue today and what it may reasonably add over time.
- Over the past 3 years the share price has gained 79.4%, which puts real weight on the question of how far Tesla's sales base and pricing power can carry that move.
- Big ticket commitments such as the reported 2,500 unit Tesla Semi order, potential new solar capacity in Texas and strong Megapack demand all feed into expectations that future revenue streams can support a higher sales run rate and a different margin mix than the car business alone.
- The analysts covering Tesla have run their own numbers. See what analysts think Tesla's shares could be worth.
The issue now is whether Tesla's current share price is justified by the level and trajectory of its sales.
If you are assessing whether Tesla’s valuation still aligns with its sales, it can be helpful to compare it with a broader group of 35 high quality undervalued stocks.
Has Tesla Run Too Far on Sales?
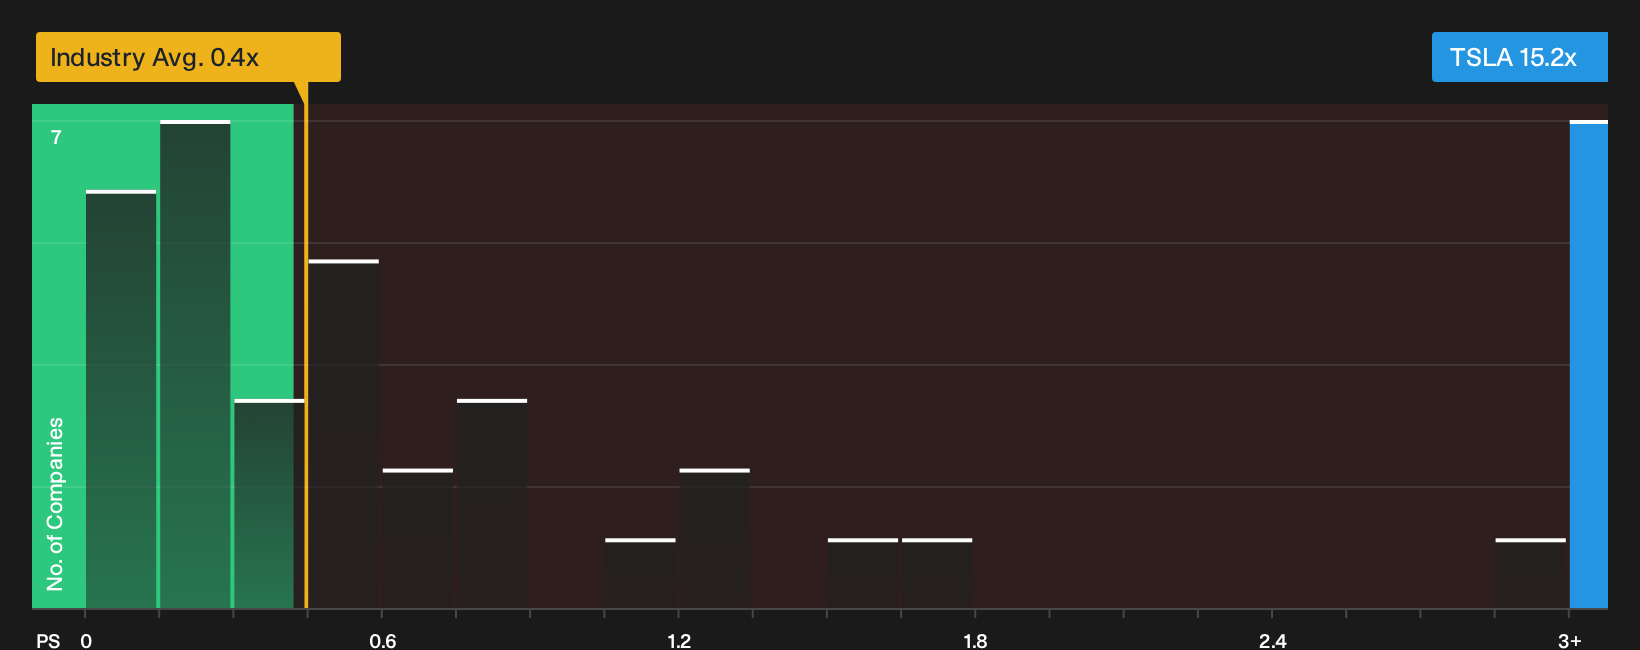
P/S fits Tesla because revenue is still the clearest common yardstick across its mix of autos, energy storage and software style services. On that basis, the stock trades on a P/S of 15.2x, compared with an auto industry average of 0.4x and a peer group around 1.1x. That is a very large premium to what investors are currently paying for sales in more traditional manufacturers.
The fair value model, which adjusts for Tesla’s growth profile, profitability pattern, size and risk, points to a materially lower P/S than today’s level, so the shares screen as overvalued on this metric. Because the gap is so wide, the framework is effectively flagging that the market is paying a high price for each dollar of Tesla’s revenue rather than offering a precise target multiple. Despite the excitement around Megapack demand, the Semi rollout and robotics and chip projects, the current P/S ratio already embeds a rich expectation for what those lines can contribute over time. Explore the numbers behind Tesla's P/S valuation.
The Tesla Narrative: What Would Justify Today's Price?
Simply Wall St Narratives pick up where Tesla's valuation puzzle leaves off by explaining the growth, margin and earnings paths that would need to hold for the stock to be worth materially more or less than it is today on the market. Each scenario ties a fair value to a specific set of potential catalysts and risks, so you can track over time which version of Tesla's story appears to be unfolding.
Community views on Tesla could hardly be more split, with one camp framing it as a future "Physical AI" platform and the other highlighting today’s rich multiples and execution risks.
Bull case: 40% undervalued
"Just as the iPhone created the App Store economy, Optimus is poised to create the "Labor Economy." Hardware as a Trojan Horse…"
Discover why this Narrative puts Tesla at 40% undervalued.
Bear case: 1228% overvalued
"The company’s price-to-earnings ratio sits at around 330x, it would take approximately 330 years for earnings per share to cover the price…"
Explore why this Narrative puts Tesla at 1228% overvalued.
One more check on Tesla that belongs beside the valuation story
Price ratios and growth narratives only tell part of the picture for Tesla, because the research also highlights separate risk indicators that could matter just as much to your decision. Take a closer look at 3 warning signs before settling on a valuation.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com