


Global Payments (GPN) has tightened its corporate rulebook. Fresh bylaw amendments now route internal shareholder disputes to the Georgia State-wide Business Court and require at least 1% ownership to launch derivative actions.
Recent headlines around a possible leveraged buyout have lit a fire under Global Payments, with a 7 day share price return of 20.35% and a 30 day gain of 25.03% helping lift the year to date share price return to 29.75%. However, the 5 year total shareholder return is still down 22.43%. Momentum is therefore improving off a weak longer track record as investors reassess both the opportunity and the risk around the stock and any potential transaction.
Surf the same leveraged buyout theme by scanning a hand-picked roster of potential takeover and rerating stories in our 19 high quality undiscovered gems.Global Payments now trades well below some estimates of fair value, yet only slightly under the average analyst target, after a sharp LBO fueled jump. Is that a genuine discount or a warning label the market refuses to remove?
Most Popular Narrative: 7% Undervalued
The most followed Global Payments valuation story now pegs fair value at $105, a touch above the latest $98 close. This keeps the LBO chatter more firmly anchored in the numbers rather than pure speculation.
The current valuation suggests the market is discounting Global Payments' ability to deliver on its synergy targets, free cash flow conversion above 90%, and multi year capital return plan.
Disciplined capital return and free cash flow conversion, with Q2 2026 adjusted free cash flow of US$687 million, conversion at about 75% of adjusted net income and a reiterated goal for full year conversion above 90%, along with plans to return over US$2b in 2026 and US$7.5b through 2027 while delevering toward 3x net leverage, can support earnings per share growth and equity value over time.
See why 43 investors see Global Payments as 7% undervalued.
Result: Fair Value of $105 (UNDERVALUED)
Still, execution risk around the Worldpay integration and prolonged travel related weakness could easily flip the Global Payments story from a discounted opportunity to a value trap.
Find out about the key risks to this Global Payments narrative.
Another View: Global Payments Looks Expensive On Earnings
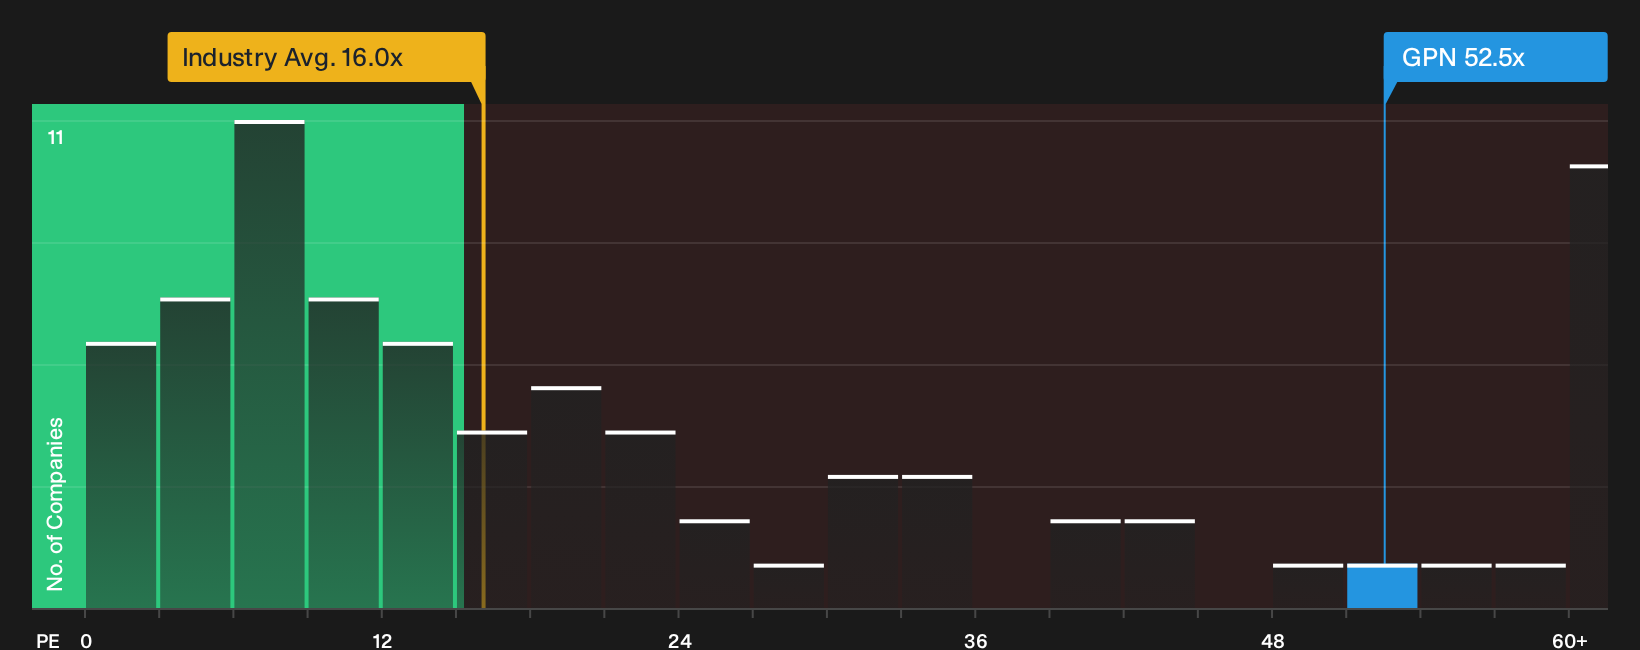
On price based metrics, Global Payments tells a very different story. The stock trades on a P/E of 52.5x, compared with 16.2x for the US Diversified Financial industry, a peer average of 42.3x, and a fair ratio of 33.8x that the market could move toward.
That kind of gap points to meaningful valuation risk if sentiment cools or earnings slip again. The key question is whether you trust the growth narrative enough to justify paying this type of premium.
See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Sentiment on Global Payments is clearly split, with meaningful concerns sitting alongside genuine optimism about its potential. Move quickly, check the underlying numbers yourself, and weigh both sides by starting with the 2 key rewards and 3 important warning signs.
Looking For More Ideas Beyond Global Payments?
If you stop with Global Payments, you risk missing other setups where price, quality, and balance sheet strength line up in your favor. Use the screener and widen your opportunity set while the market is still sorting winners from laggards.
- Target mispriced quality by running a focused search for companies that look statistically cheap yet financially robust through the 35 high quality undervalued stocks.
- Identify potential income streams by scanning for businesses with substantial yields and resilient payout histories using the 4 dividend fortresses.
- Reduce portfolio risk by filtering for resilient balance sheets and solid fundamentals with the list of solid balance sheet and fundamentals (23 results).
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com