


ChemoMetec (CPSE:CHEMM) drew fresh attention after management raised revenue and EBITDA guidance for the 2026/27 financial year, following first quarter figures that showed 28% revenue growth and a higher 63% EBITDA margin.
Recent trading reflects that guidance shift. ChemoMetec’s share price has climbed 18.9% over the past month and 58% across 90 days, yet the year-to-date share price return is still down 3% and the 1-year total shareholder return has fallen 15%, pointing to recovering momentum after a weaker spell.
Scan how ChemoMetec fits into the wider opportunity set by reviewing our hand picked 603 high quality undiscovered gems with similarly strong fundamentals and under-the-radar potential.
After a 58% move in 90 days, yet a 1-year return still in decline, ChemoMetec now forces a choice. Is this a fresh entry point, or a bounce that invites patience while the valuation settles?
Most Popular Narrative: 3% Overvalued
The widely followed narrative puts ChemoMetec’s fair value at DKK638, slightly under the last close of DKK654.5, which suggests expectations are already rich and resting on specific execution milestones.
The thesis leans heavily on multiyear replacement of NC-200 and large automation collaborations with partners such as Hamilton, Tecan and Roche. Management has limited visibility, long validation timelines and no firm numbers from these collaborations, so any delays, lower than expected unit replacement ratios or fewer systems per site could leave revenue and EBITDA below analyst expectations.
See why 1 investors see ChemoMetec as 3% overvalued.
Result: Fair Value of DKK638 (OVERVALUED)
Still, the thesis can fray if heavy product development spend fails to translate into adoption, or if NC-200 replacements and automation partnerships deliver fewer systems than expected.
Find out about the key risks to this ChemoMetec narrative.
Another View: ChemoMetec Through The DCF Lens
Against the analyst fair value of DKK638 that implies ChemoMetec is 3% overvalued, the Simply Wall St DCF model points in the other direction. On that framework, DKK654.5 trades about 2.4% below an estimated future cash flow value of DKK670.84. Which signal do you treat as the anchor?
For a closer look at how those cash flows are treated over time, and how sensitive the result is to the inputs, review the Look into how the SWS DCF model arrives at its fair value..
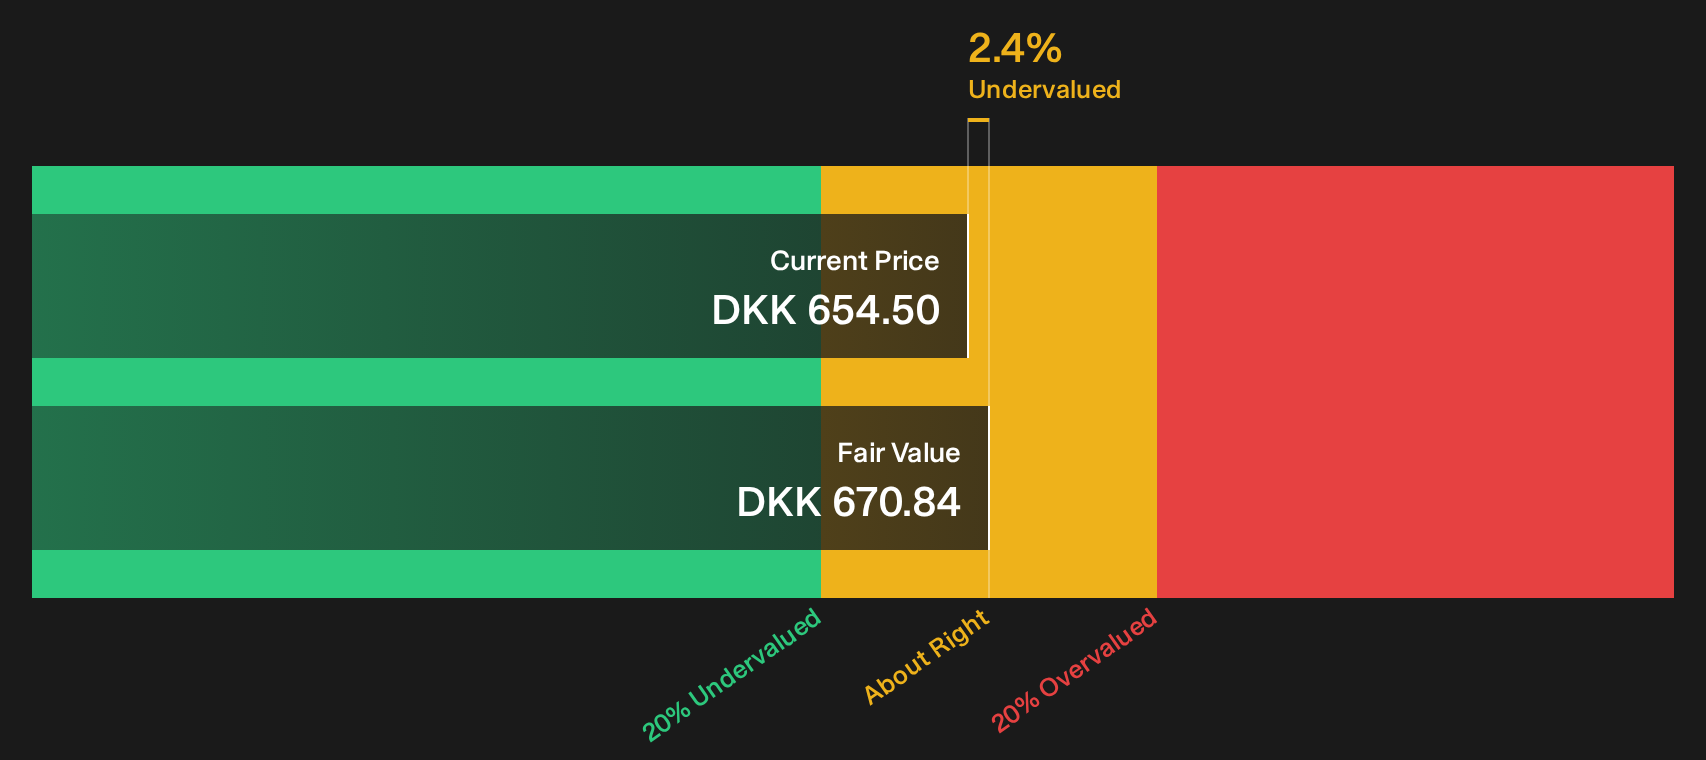
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out ChemoMetec for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 197 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
Mixed messages on ChemoMetec’s value story. That tension is exactly why it helps to move quickly, review the full data set, and weigh both the 3 key rewards and 2 important warning signs.
Looking for more ChemoMetec investment ideas?
ChemoMetec may be front of mind today, but the next opportunity often hides where fewer investors are looking, so do not leave that edge on the table.
- Target resilient returns by focusing on companies with stronger financial fundamentals through the 221 resilient stocks with low risk scores.
- Spot potential mispricings early by scanning the 197 high quality undervalued stocks before others catch on.
- Prioritise balance sheet strength by filtering for robust fundamentals using the list of solid balance sheet and fundamentals (196 results).
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com