


NuScale Power has seen its share price fall sharply over the past year, even as it pushes ahead with small modular reactor partnerships and manufacturing plans. With the stock now trading well below where it was 12 months ago, investors are increasingly asking whether the current price still lines up with the company’s book value.
- Over the past year the share price has fallen 84.9%, which puts the spotlight on whether today’s valuation can still be explained by the balance sheet behind NuScale Power.
- The recent move to have Doosan Enerbility manufacture key reactor modules, together with the large cash position and very limited current revenue, can reshape expectations for how quickly NuScale Power may convert its capital base into future earnings.
- The analysts covering NuScale Power have run their own numbers. See what analysts think NuScale Power's shares could be worth.
The issue now is whether the current share price of NuScale Power is appropriately aligned with the book value that shareholders are buying into.
If you are weighing NuScale Power against other nuclear-focused plays, it can help to compare how the market is pricing similar infrastructure stories through the 16 nuclear energy infrastructure stocks.
Does NuScale Power Look Undervalued on Book Value?
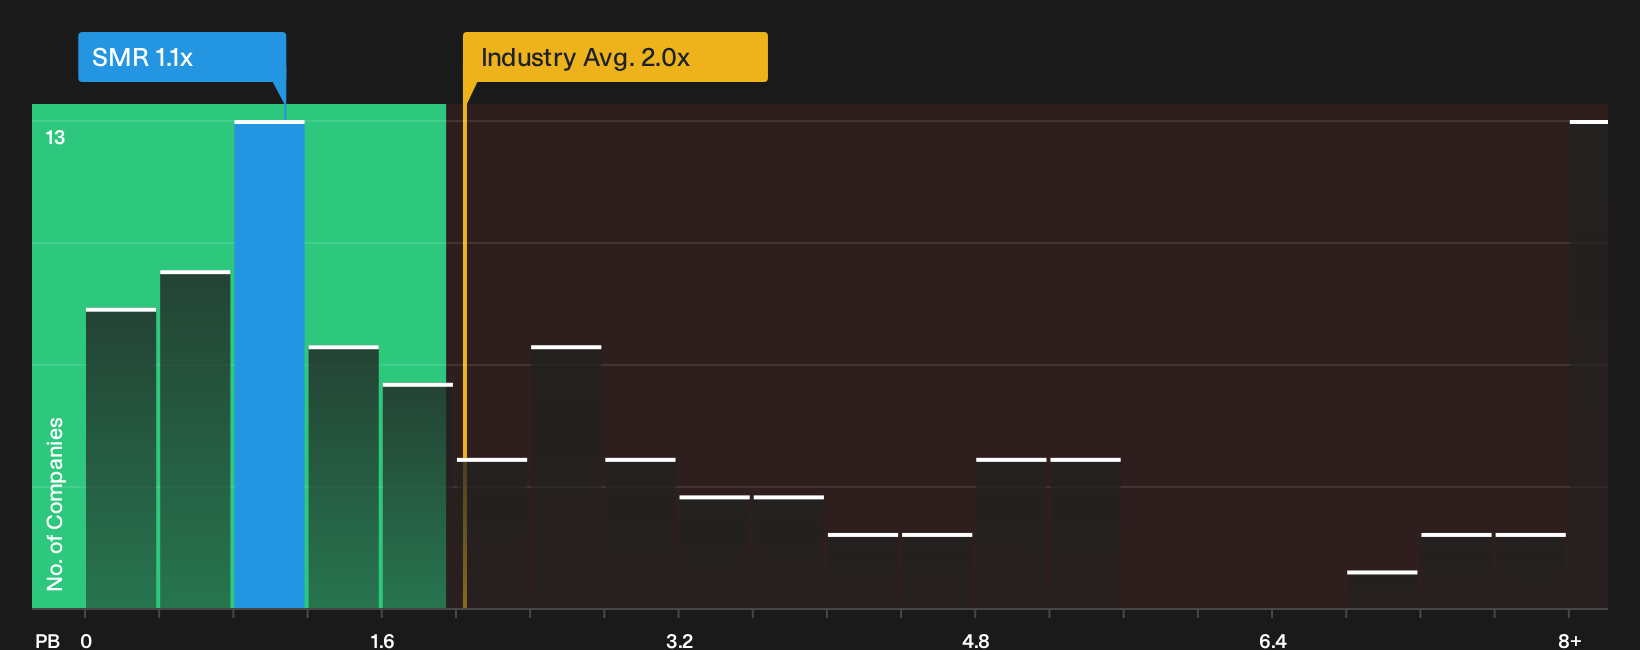
P/B is a useful yardstick for NuScale Power because the story today is still mostly about its capital base and nuclear assets rather than earnings. The stock trades around 1.1x P/B, which is close to its recorded equity value and well below the Electrical industry average of roughly 2.0x. Against peers closer to 5.6x, the market is putting a relatively modest premium on NuScale Power’s balance sheet.
Because the recent Doosan Enerbility manufacturing deal pushes the business further into the build out phase, that discount suggests investors are not paying up aggressively for those plans compared with many electrical equipment rivals. For you as a shareholder, the key question is whether that lower P/B multiple reflects genuine project and execution risk, or whether it leaves room if NuScale Power converts more of its large cash position and reactor partnerships into contracted projects over time. Explore the numbers behind NuScale Power's P/B valuation.
The NuScale Power Narrative: What Would Justify Today's Price?
Simply Wall St Narratives pick up where the NuScale Power valuation puzzle leaves off. They spell out which combinations of future growth, profitability and earnings paths would need to play out for the stock to trade meaningfully higher or lower than it does today. Each scenario links its number to a specific view on how NuScale Power's growth, margins and risk profile might evolve, which you can check back against as fresh information comes through.
Community views on NuScale Power split sharply between those who see a misunderstood nuclear platform and others who focus on execution and legal risk.
Bull case: 95% undervalued
"NuScale holds the only SMR design currently certified by the Nuclear Regulatory Commission. That certification took years and hundreds of millions of dollars…"
Discover why this Narrative puts NuScale Power at 95% undervalued.
Bear case: 563% overvalued
"The ENTRA1 controversy and the resulting fraud lawsuits are serious. It raises questions about whether management can actually execute the commercial side…"
Explore why this Narrative puts NuScale Power at 563% overvalued.
The NuScale Power price is only one piece of the decision
Before weighing NuScale Power purely on its valuation and balance sheet metrics, it helps to understand that our broader checks have highlighted specific risk signals that deserve your attention. Take a closer look at 3 warning signs (1 major) before settling on a valuation.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com