


Vertiv Holdings Co (VRT) moved back into focus after management issued fresh fourth quarter and full year 2026 guidance, pairing those targets with detailed third quarter revenue and earnings figures.
Vertiv Holdings Co has seen sentiment swing sharply in recent weeks, with the share price dropping 6.43% over the past month and 15.10% over 90 days. A subsequent 5.23% one day and 13.14% seven day share price rebound pushed year to date share price returns to 34.37% and lifted the latest one year total shareholder return to 30.64%, on top of a very large 3 year total shareholder return of almost 5x. This puts the recent pullback more in the category of cooling momentum than a full reset in investor expectations.
Scan how Vertiv Holdings Co fits into the wider AI infrastructure story by comparing it with hand-picked 53 AI infrastructure stocks that are also tied to data center power and cooling demand.
After a sharp October drop and a fast snapback on strong guidance, Vertiv Holdings Co now forces a harder call. Is the current price already rich on recent execution, or does waiting for a cleaner entry risk missing the move that management is guiding toward?
Most Popular Narrative: 47.6% Undervalued
Against Vertiv Holdings Co's last close of $235.97, the most followed narrative anchors a fair value at $450. The gap between those two figures is what powers the current debate around whether the recent pullback is opportunity or warning sign.
They have essentially built a moat around the "thermal wall." As AI chips get faster and hotter, the standard air-cooling systems used by everyone else are hitting their physical limit. Vertiv is not just selling equipment, they are selling the only viable path to higher computing density. When you combine their massive installed base with their ability to design integrated, end-to-end power and cooling solutions, they move from being a vendor to an irreplaceable partner.
See why 90 investors see Vertiv Holdings Co as 48% undervalued.
According to FundamentalFlow, this narrative treats Vertiv Holdings Co less like a typical hardware supplier and more like a utility for AI data centers. The argument is that the pricing power and long-term contracts that can come from that role justify a large gap between the current share price and a higher intrinsic value estimate.
That view leans heavily on the forecast profile. Revenue is expected to grow 20.1% per year, ahead of the wider US market at 13.2%. Earnings are projected to expand 25.3% a year, which the data classifies as significant and ahead of the broader market. Earnings growth over the past year was recorded at 102.9%, compared with a 5 year average of 57.5% a year, and net profit margins are described as improving from 10.7% to 16%.
The quality flags in the data set line up with this growth story. Vertiv Holdings Co is assessed as having high quality earnings. Return on equity is reported at 38.1%, which is considered high, and is forecast to reach 46% in three years. Analysts are in close agreement on their forecasts, and the consensus target price of $339.07 sits 30.4% above the last close, while the SWS DCF model value of $265.84 is 11.2% above the market price.
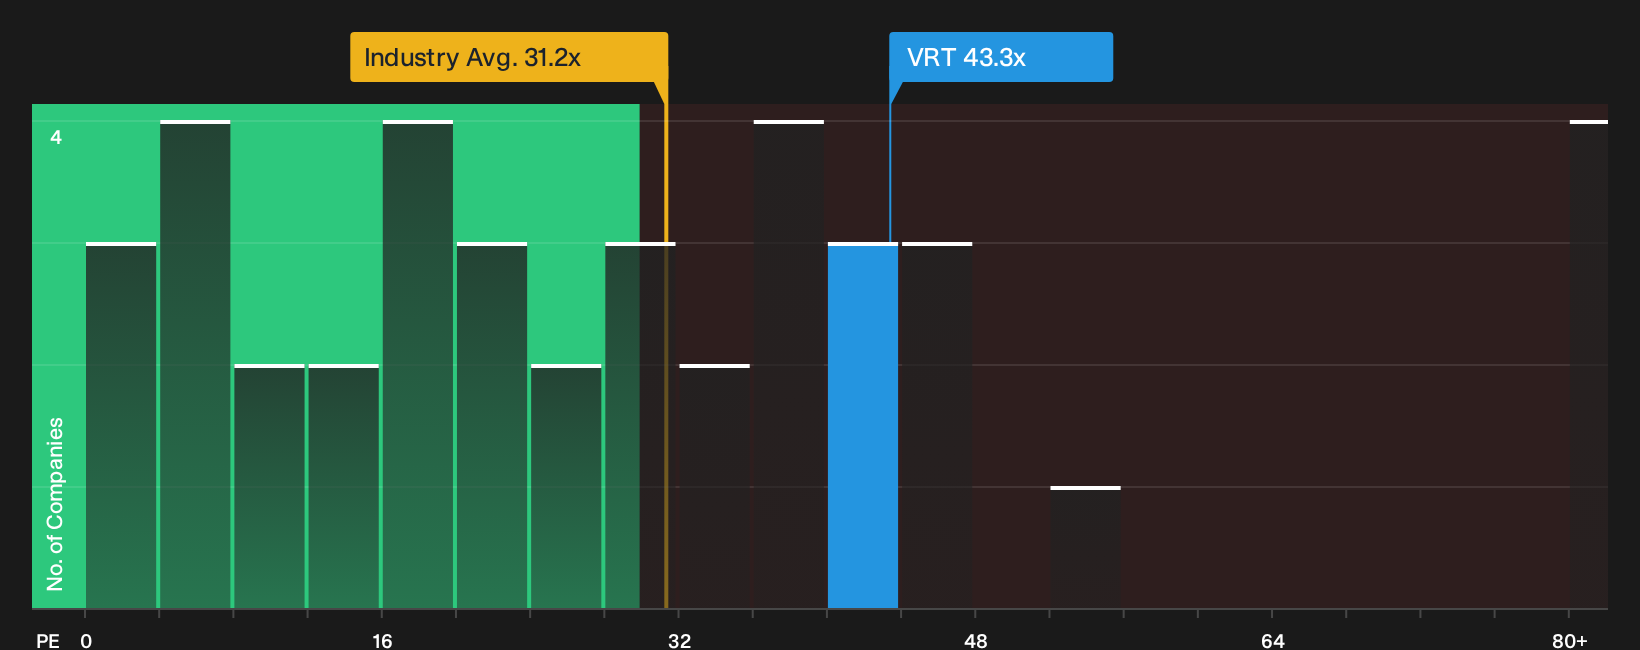
Pricing tells a different story. Vertiv Holdings Co trades on a P/E of 43.3x, which is described as expensive versus both peer averages at 38.3x and the wider US Electrical industry at 31.2x. The same data flags that this multiple is closer to an estimated fair P/E of 46.7x, suggesting the valuation sits in a premium band but not wildly outside the range implied by the growth and profitability profile.
For readers weighing that tension between premium P/E and growth-backed fair value estimates, the narrative and the DCF output both lean in the same direction. The SWS model flags Vertiv Holdings Co as trading below estimated future cash flow value at $265.84, while the most popular narrative points to a much higher $450 fair value anchor.
Result: Fair Value of $450 (UNDERVALUED)
Still, the Vertiv Holdings Co story leans heavily on hyperscaler spending and a large backlog, so project delays or tougher liquid cooling competition could quickly weaken that bullish narrative.
Find out about the key risks to this Vertiv Holdings Co narrative.
Another View: Vertiv Holdings Co Through The P/E Lens
Vertiv Holdings Co may look attractively priced on cash flow models, but the earnings multiple tells a tougher story. The stock trades on a P/E of 43.3x, richer than both peers at 38.3x and the US Electrical industry at 31.2x, even though the fair ratio sits at 46.7x.
That gap means anyone buying today is paying a clear premium for Vertiv Holdings Co on reported earnings, with only a modest cushion to the fair ratio if sentiment cools. The question for you is simple: are growth forecasts and quality metrics enough to justify paying above the peer pack for this AI infrastructure supplier?
See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Feeling the bullish tone around Vertiv Holdings Co but unsure whether it matches your own risk appetite and time horizon? Take a moment to review the underlying metrics and sentiment drivers yourself, then weigh those against the 4 key rewards.
Looking for more Vertiv Holdings Co sized opportunities?
Do not stop with Vertiv Holdings Co. The same tools that surface this AI infrastructure story can help you spot new ideas before they hit everyone’s radar.
- Target potential value upside by scanning a curated 35 high quality undervalued stocks that filters for strong fundamentals at prices the market has not fully reflected yet.
- Prioritize resilience and sleep-better-at-night positions by reviewing a 30 resilient stocks with low risk scores that screens for sturdier balance sheets and calmer volatility profiles.
- Get ahead of the crowd by working through a 19 high quality undiscovered gems that highlights quality businesses still flying under most investors’ radar.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com