


Amidst fears of an AI bubble, the NASDAQ Composite Index ($NASX) has corrected by 8.4% in the past month. There are also fears that an AI-driven stock market slump can translate into a global economic deceleration and “tip several major economies into recession.”
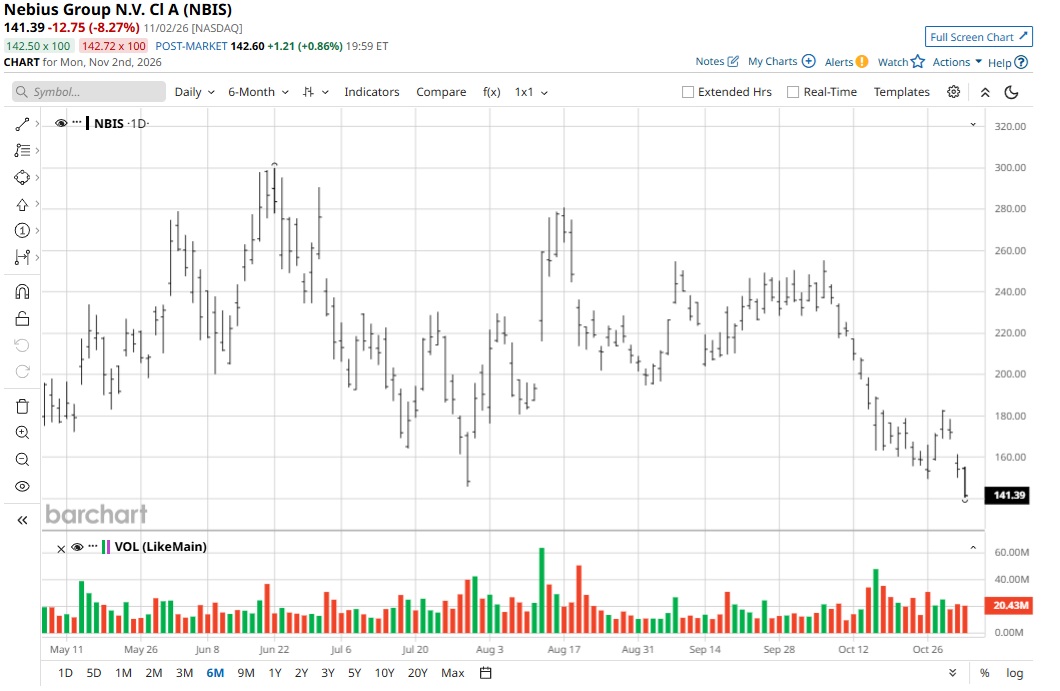
Nebius Group (NBIS) stock has been among the victims of the sell-off. Last Friday, NBIS stock slumped by 11% on “continued investor concerns about financing requirements and the capital intensity of AI cloud expansion.” Further, in the last month, the stock has declined 42%.
Given the deep correction and the earnings momentum, there seems to be a buying opportunity. However, if the broader technology sector sentiment remains depressed, it’s unlikely that NBIS stock will outperform. Therefore, the best strategy is likely to be gradual accumulation.
About Nebius Stock
Headquartered in Schiphol, Netherlands, Nebius is a provider of full-stack AI cloud. The company offers integrated suite of AI and ML cloud solutions, including both hardware and software built in-house.
A combination of AI-optimized hardware and software enables it to deliver high-performance GPU compute clusters, storage, managed services, and advanced tools for AI model training and inference at enterprise scale. Nebius claims to be among the few global, at-scale, multi-tenant cloud providers purpose-built for AI.
For Q2 FY26, Nebius reported year-on-year revenue growth of 454% to $582.3 million. For the same period, the company reported adjusted EBITDA of $236.2 million. This growth was primarily driven by Nebius AI Cloud, where the ARR has also scaled to $3 billion.
While growth has been robust, valuation concerns coupled with a broader sell-off in technology stocks have resulted in NBIS stock declining by 19.9% in the last six months.
Encouraging Quarterly Numbers
Nebius stock has witnessed a deep correction in the last few weeks. However, multiple financial and business metrics are encouraging and point to better fundamentals in the coming quarters.
The first point to note is that Nebius AI Cloud is the growth driver for the company. For Q2 FY25, the segment reported an adjusted EBITDA margin of 24%. However, for Q2 FY26, adjusted EBITDA margin has expanded to 49.7%.
The second important point is that Nebius reported $2.3 billion in operating cash flow for the quarter. Further, the company ended Q2 with a cash buffer of $8 billion. While the capital intensity is significant, Nebius is well positioned to invest.
Financing growth is unlikely to be a challenge because Nebius has long-term contracts with investment-grade customers. In Q2, the company raised $775 million in a secured facility that’s backed by $40 billion in customer commitments.
It’s also worth noting that the company expects to end 2026 with 5GW of contracted power. This is ahead of the guidance of +4GW, which the company had expected in Q1. At the same time, Nebius will be deploying more than 1GW per year, starting in 2027. The progress has therefore been robust, and capacity expansion will be supported by customer pre-payments coupled with secured facilities that are backed by customer commitments. On the flip side, rising interest rates are a potential risk factor.
Overall, business developments for Nebius remain positive. However, NBIS stock has retracted from stretched valuations. Given the intensity of the correction in the last few weeks, there seems to be an opportunity to accumulate.
What Do Analysts Say About NBIS Stock?
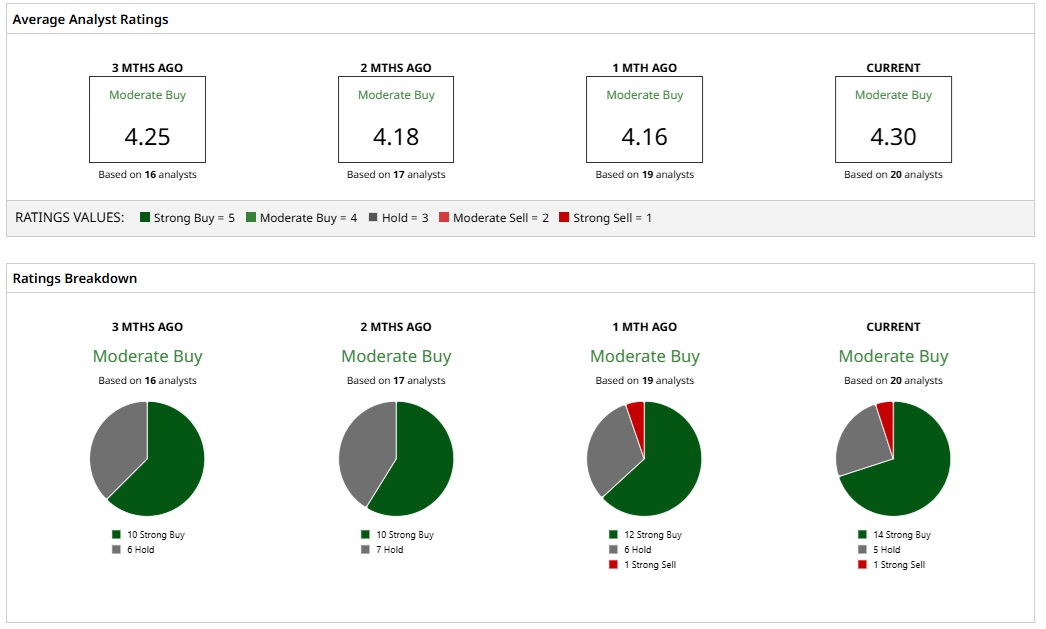
Based on 20 analysts with coverage, NBIS stock has a consensus “Moderate Buy” rating. While 14 analysts have a “Strong Buy” rating for the stock, five have a “Hold,” and one has a “Strong Sell” rating.
The mean price target of $285.19 represents potential upside of 101.7% from current levels. Further, the most bullish price target of $410 suggests that NBIS stock could climb as much as 190% from here.
On the date of publication, Faisal Humayun Khan did not directly have a position in any of the securities mentioned in this article. All information and data in this article is solely for informational purposes. For more information please view the Barchart Disclosure Policy here.