


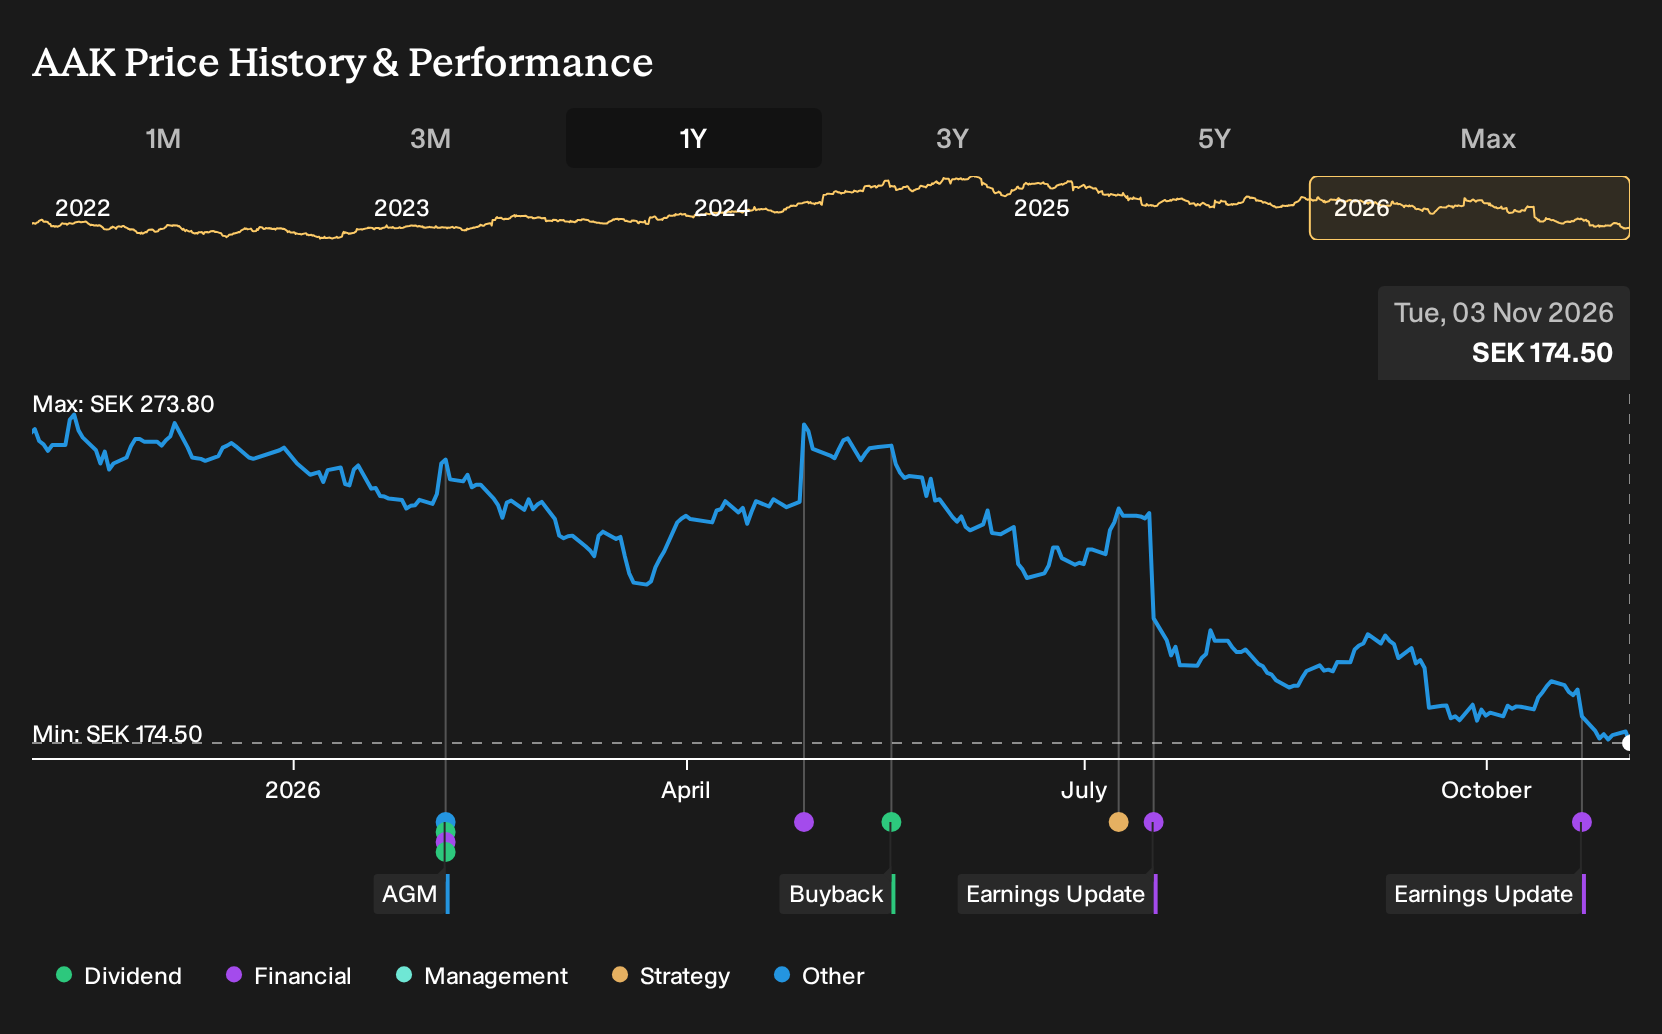
If you backed AAK AB (publ.) for its plant-based fats exposure and ESG angle, the past year will have felt harsh. Holding AAK AB (publ.) over the past year would have meant a 32.0% loss, including dividends. If you made that call on 3 November 2025, you were leaning on modest revenue growth, margin uplift toward 9.9%, and a future P/E of 19.6x. Which of those specific assumptions proved most vulnerable?
If the move has made AAK AB (publ.) harder to judge, start where the gap is still open and scan 194 high quality undervalued stocks.
The Two Stories Investors Had To Weigh On AAK AB (publ.)
The shares cost SEK269 at the start of the period, and anyone looking at AAK AB (publ.) then had to choose between two very different stories.
The bullish view pointed to a Fair Value of SEK308, a rough guide to what that camp thought the shares were worth if its thesis played out. That relied on revenue rising 1.0% and profit margins reaching 9.9%, supported by tighter cost control and an ESG-focused, plant-based fats portfolio.
The cautious camp worked off a Fair Value of SEK245, implying downside if its concerns proved closer to reality. That side worried about declining volumes in Bakery and Chocolate & Confectionery, rising compliance and raw material costs, and pressure on AAK AB (publ.) from large food producers bringing fat-processing in house.
What The Results Changed For The AAK AB (publ.) Thesis
The key fact is simple. AAK AB (publ.) posted Q3 2026 revenue of SEK11,910m against SEK11,498m a year earlier, but net income slipped to SEK837m and net margin moved from 7.9% to 7.0%. That pattern supports the cautious story that questioned how far margins could stretch, even as the chocolate and confectionery fats push and capacity projects kept the bullish angle from fully breaking.
The lesson is to treat margin targets as separate from sales hopes. When weighing any stock with an efficiency story, track net margin against what was assumed and check whether higher volumes are coming with fatter, not thinner, profitability.
What You Would Be Paying For In AAK AB (publ.) Today
AAK AB (publ.) now trades at SEK174, with the selected Narrative viewing Fair Value as higher than that quote. The focus has shifted from chasing volumes to improving mix, cash discipline and how capital is put to work.
To treat the fall as an opening rather than a warning, a buyer today would need to believe AAK can keep lifting value per kilo while Fit to Win and Cash to Grow deliver the operational gains described in the Narrative.
"The main thing that has to go right is that AAK AB (publ.) successfully executes its profitability and efficiency programs, including Fit to Win and Cash to Grow, while managing competitive pressure and production disruptions in Food Ingredients. The current valuation implies that the market is cautious about AAK AB (publ.) delivering on its 2030 profitability ambitions and capital deployment plans, and this narrative interprets that caution as the stock being undervalued and positioned for better share price recognition if those plans hold."
One Narrative disagrees with today's price. → See where this Narrative says AAK AB (publ.) should trade
Which Company Could Surprise You Next?
The next headline does not have to be where your research begins. Go straight to the companies and see whether a contrarian opportunity could be taking shape.
- Company 1 - 42% below our estimate - targets everyday athletes as sports apparel grows beyond its legacy underwear focus.
- Company 2 - 18% below our estimate - attracts senior lawyers onto a dispersed tech platform that rewires partnership economics.
- Company 3 - 49% below our estimate - shifts heavy AI and cloud spending into subscription security platforms tied to ARR growth.
That is three of the list. See every one of the 196 solid balance sheet companies →
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com