


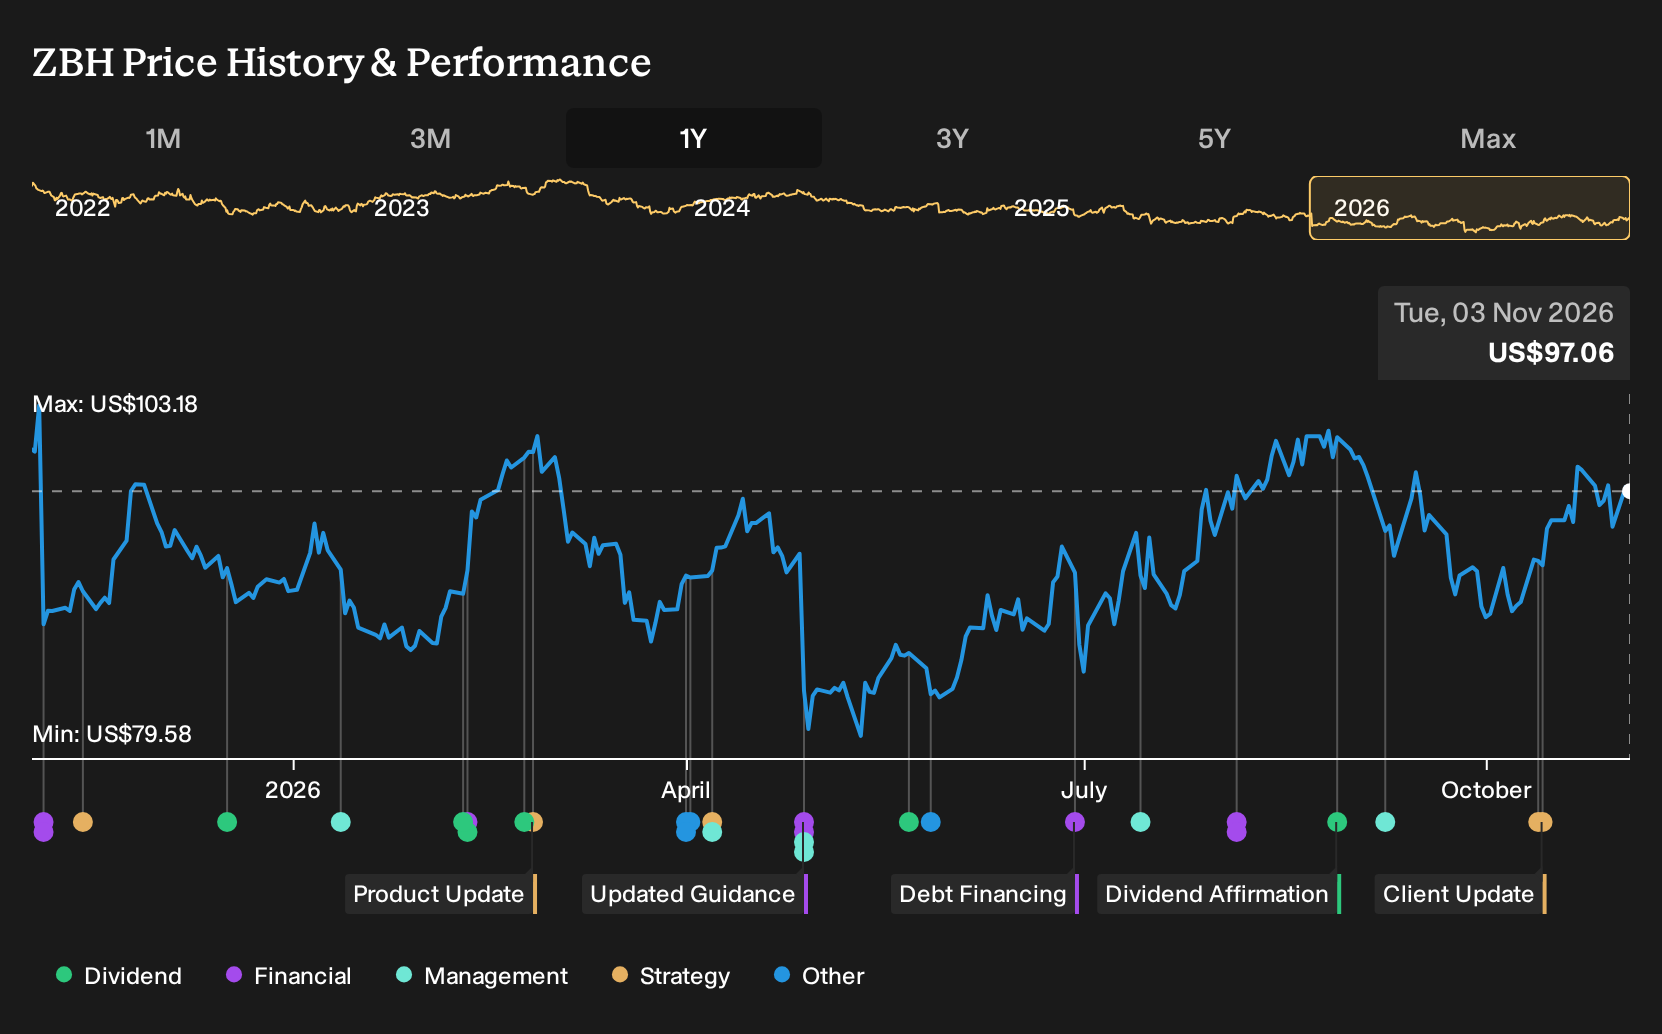
- Zimmer Biomet Holdings reported its Q3 2026 earnings, with revenue rising 4.8% year on year and earnings per share increasing 33.8%, supported by a net debt to EBITDA ratio of 2.7 and an annual dividend of US$0.96 per share, equal to a 0.98% yield.
- The combination of faster earnings per share growth than sales and a leverage level that remains within a moderate range points to improving operational efficiency for Zimmer Biomet Holdings, while the business continues to return cash through dividends.
- We will look at how Zimmer Biomet Holdings' investment narrative lines up with this quarter's 33.8% earnings per share increase.
Scan how Zimmer Biomet Holdings compares with other medical stocks that show stronger earnings momentum and disciplined balance sheets inside the curated 30 resilient stocks with low risk scores
Zimmer Biomet Holdings Investment Narrative Recap
To own Zimmer Biomet Holdings, you need to believe that the orthopedic devices market can keep absorbing more robotics, data tools and procedure volumes while this business lifts earnings faster than revenue. The Q3 2026 report, with 4.8% revenue growth and a 33.8% EPS increase, supports that efficiency story rather than changing it.
The near term swing factor still looks like execution on commercial changes such as Project Optima and ongoing cost programs. Pricing pressure, reimbursement risk and already guided margin pressure for 2026 remain key watchpoints, so this quarter’s strength does not remove the possibility of further margin strain if costs stay elevated.
The Q3 2026 earnings call is most relevant here because it ties the recent 33.8% EPS growth back to Zimmer Biomet Holdings’ ongoing restructuring and commercial overhaul. Management is balancing higher U.S. commercial investment, manufacturing network changes and a net debt to EBITDA ratio of 2.7 while still reporting higher earnings per share.
For catalysts, that call matters because it updates progress on Project Optima, the Costa Rica plant build out and the global capability center in India, all of which link directly to the margin reset narrative. At the same time, investors need to weigh comments on pricing headwinds and restructuring risk against the contribution from higher value Technology & Data platforms and acquisitions such as Paragon 28 and iovera.
Zimmer Biomet Holdings' outlook projects US$9.4b in revenue and US$1.3b in earnings by 2029. This assumes 3.4% yearly revenue growth and an earnings increase of about US$493.3m from US$806.7m today.
Uncover why Zimmer Biomet Holdings' fair value indicates an 11% potential upside to its current price before that discount closes.
Exploring Other Perspectives
Three fair value views from the Simply Wall St Community span roughly US$108 at the low end to about US$261 at the high end, which is a wide spread for Zimmer Biomet Holdings. Treat these as starting points. Pricing pressure, margin strain and restructuring risk mean outcomes can differ sharply, so explore multiple opinions before forming your own stance.
Explore 2 other Zimmer Biomet Holdings fair value estimates, including one that suggests it could be worth just $107.57.
Reach Your Own Conclusion
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so go with your instincts.
- A great starting point for your Zimmer Biomet Holdings research is our analysis highlighting 3 key rewards and 2 important warning signs that could impact your investment decision.
- See our latest analysis for Zimmer Biomet Holdings. This report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Zimmer Biomet Holdings' overall financial health at a glance.
Looking For More Investment Ideas Beyond Zimmer Biomet Holdings?
Zimmer Biomet Holdings may be on your radar already, but building a resilient portfolio usually means lining it up against a broader watchlist of candidates with different strengths. The Simply Wall St Screener can help you quickly filter for stocks that match your risk tolerance, income needs and quality preferences so you are not relying on a single story.
- For investors who want income with stability, focus on payout strength and consistency by reviewing 4 dividend fortresses.
- If capital preservation and sturdier finances matter most to you, start with companies that show healthier gearing and liquidity profiles through the list of solid balance sheet and fundamentals (23 results).
- When you want fresh ideas that the market may be overlooking, broaden your watchlist with the 19 high quality undiscovered gems.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com