


Australian dividend stocks are back in focus as investors reassess income ideas after a sweeping Democrat win in the US raised questions about future regulation, taxes and debt markets. When politics raise new question marks, reliable cash payouts start to look more attractive. This article focuses on higher yielding Australian dividend payers and highlights three income stocks from a carefully filtered list with yields above 3% that appear better supported by profits.
The three stocks highlighted here offer a compelling starting point if you want exposure to higher yielding dividends that look better covered, growing, and relatively stable. However, if you want the strongest names, these 5 dividend aristocrats stocks are at the top of the list.
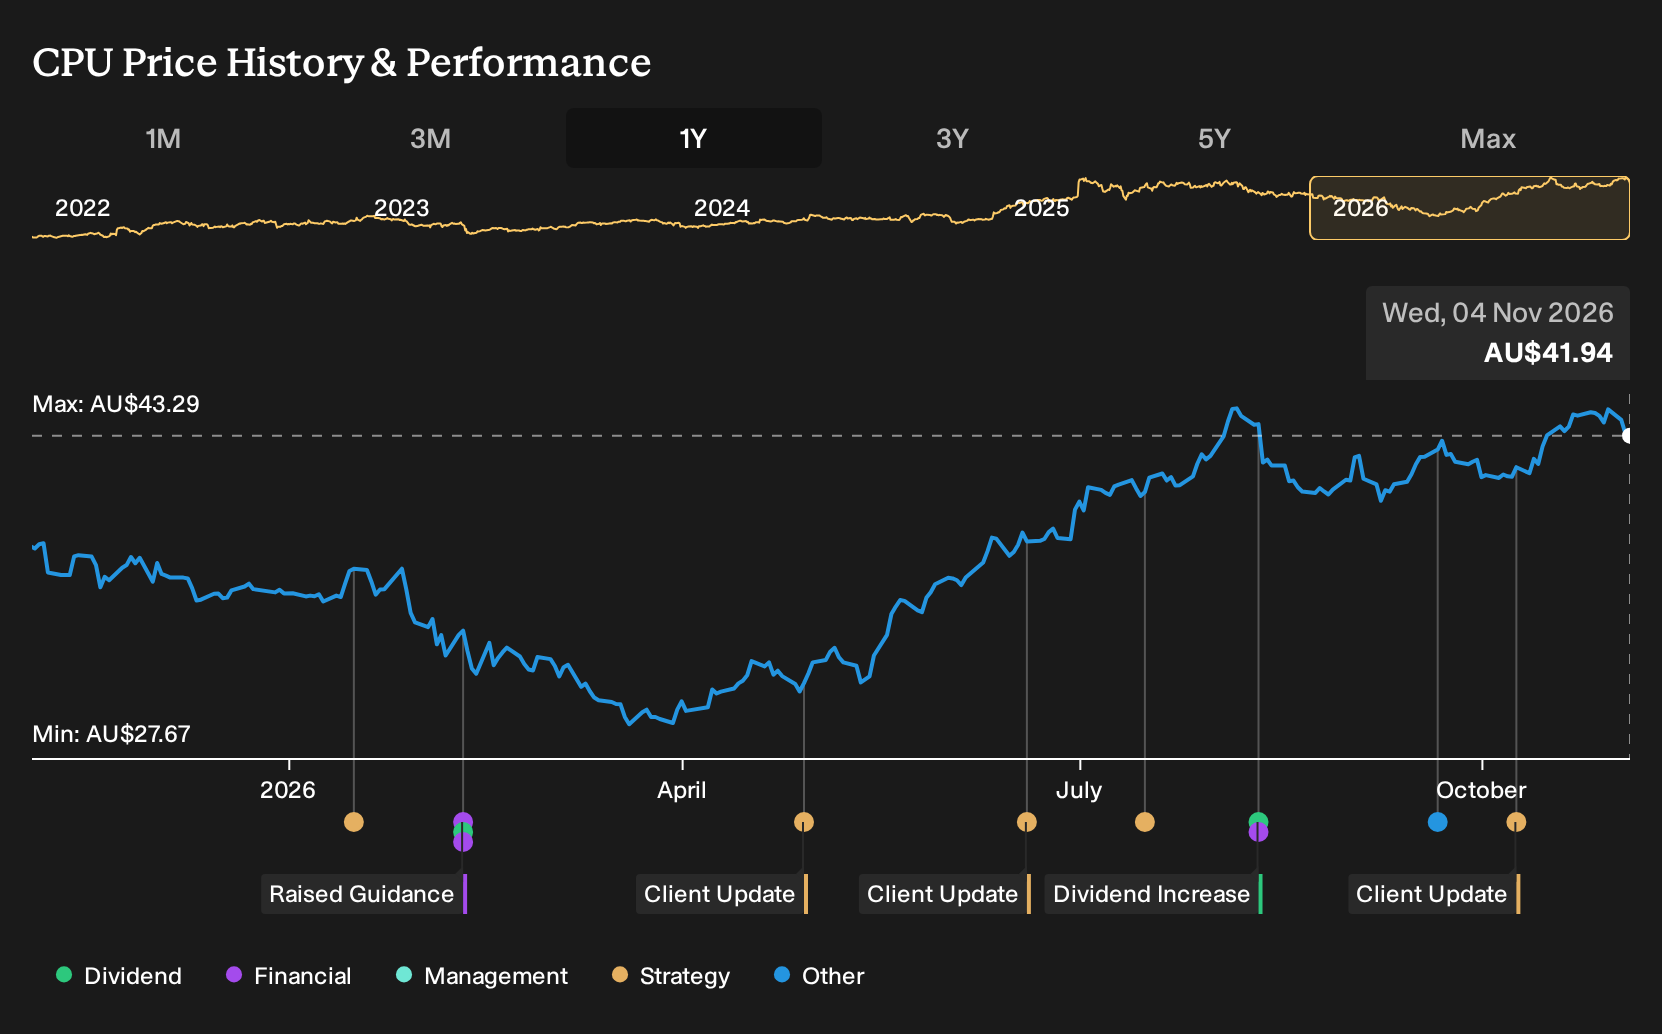
Computershare (ASX:CPU)
Overview: Computershare runs issuer services, transfer agent and employee share plan platforms that handle shareholder records, corporate actions and dividend payments for companies worldwide.
Operations: The group generates most revenue from Issuer Services at about US$1.3b and Corporate Trust at about US$1.0b, with contributions from Employee Share Plans and other activities across the United States, UK and Australia.
Market Cap: A$24.3b
Computershare matters for a dividend-focused investor because its core registry and transfer agent operations handle the plumbing of dividend payments, and recent business updates frame how durable that income engine might be in practice.
"Importantly, this assessment is based primarily on Computershare’s existing operations, current client balances and FY26 earnings guidance."
What really moves the dial for Computershare’s future dividend potential is how one quiet but powerful driver of its earnings ultimately plays out.
To see how that earnings driver could reshape the income profile, read the full narrative for Computershare to understand what current guidance may be masking.
BHP Group (ASX:BHP)
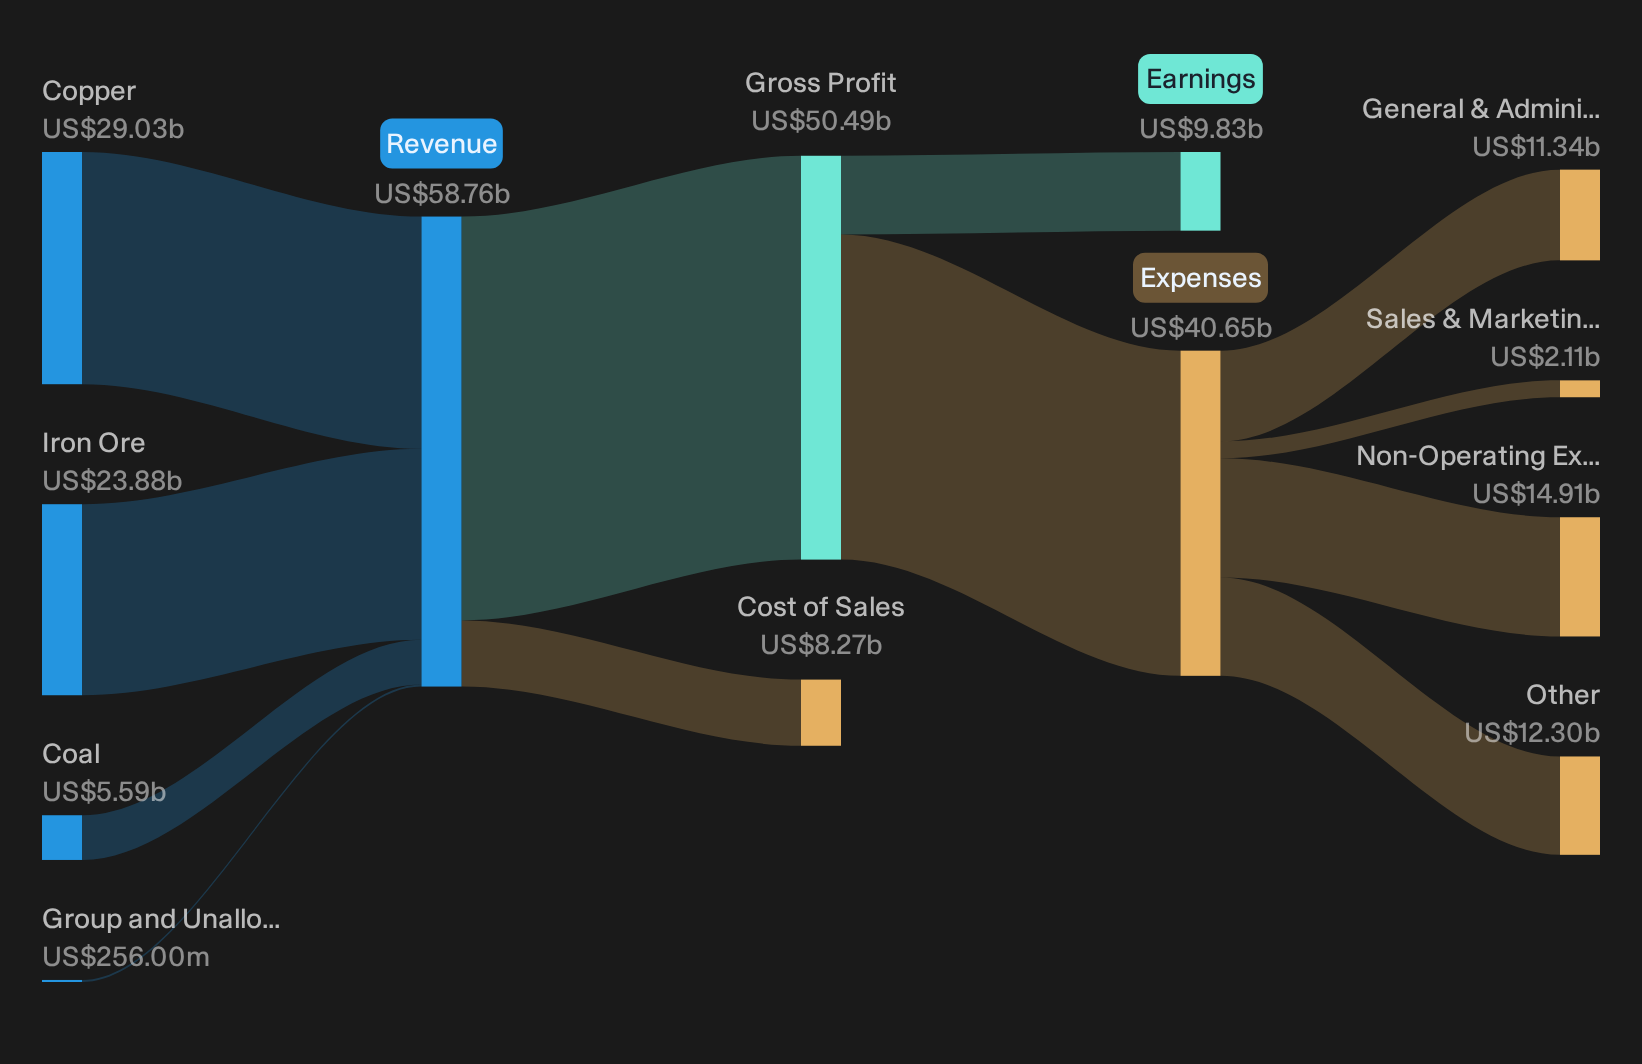
Overview: BHP Group is a global resources company that produces iron ore, copper, steelmaking coal and other commodities that underpin its large, fully franked dividend stream.
Operations: The business generates US$29.0b from Copper, US$23.9b from Iron Ore and US$5.6b from Coal, with China its largest customer market by a wide margin.
Market Cap: A$286.8b
BHP Group matters in a Dividend Powerhouses screen because its bulk iron ore and metallurgical coal operations generate the cash that funds those sizeable, fully franked payouts.
"A strong pipeline of copper and potash projects positions BHP Group to benefit from a global surge in decarbonization efforts and electrification initiatives, with rising demand for critical minerals expected to influence future revenues."
The real test for that dividend powerhouse label is how one large, long dated growth bet ultimately reshapes cash generation and margin resilience.
That long dated wager is only part of the story, and the full narrative for BHP Group shows how cash flows, risks and dividends could be decoupling from old assumptions.
Monadelphous Group (ASX:MND)
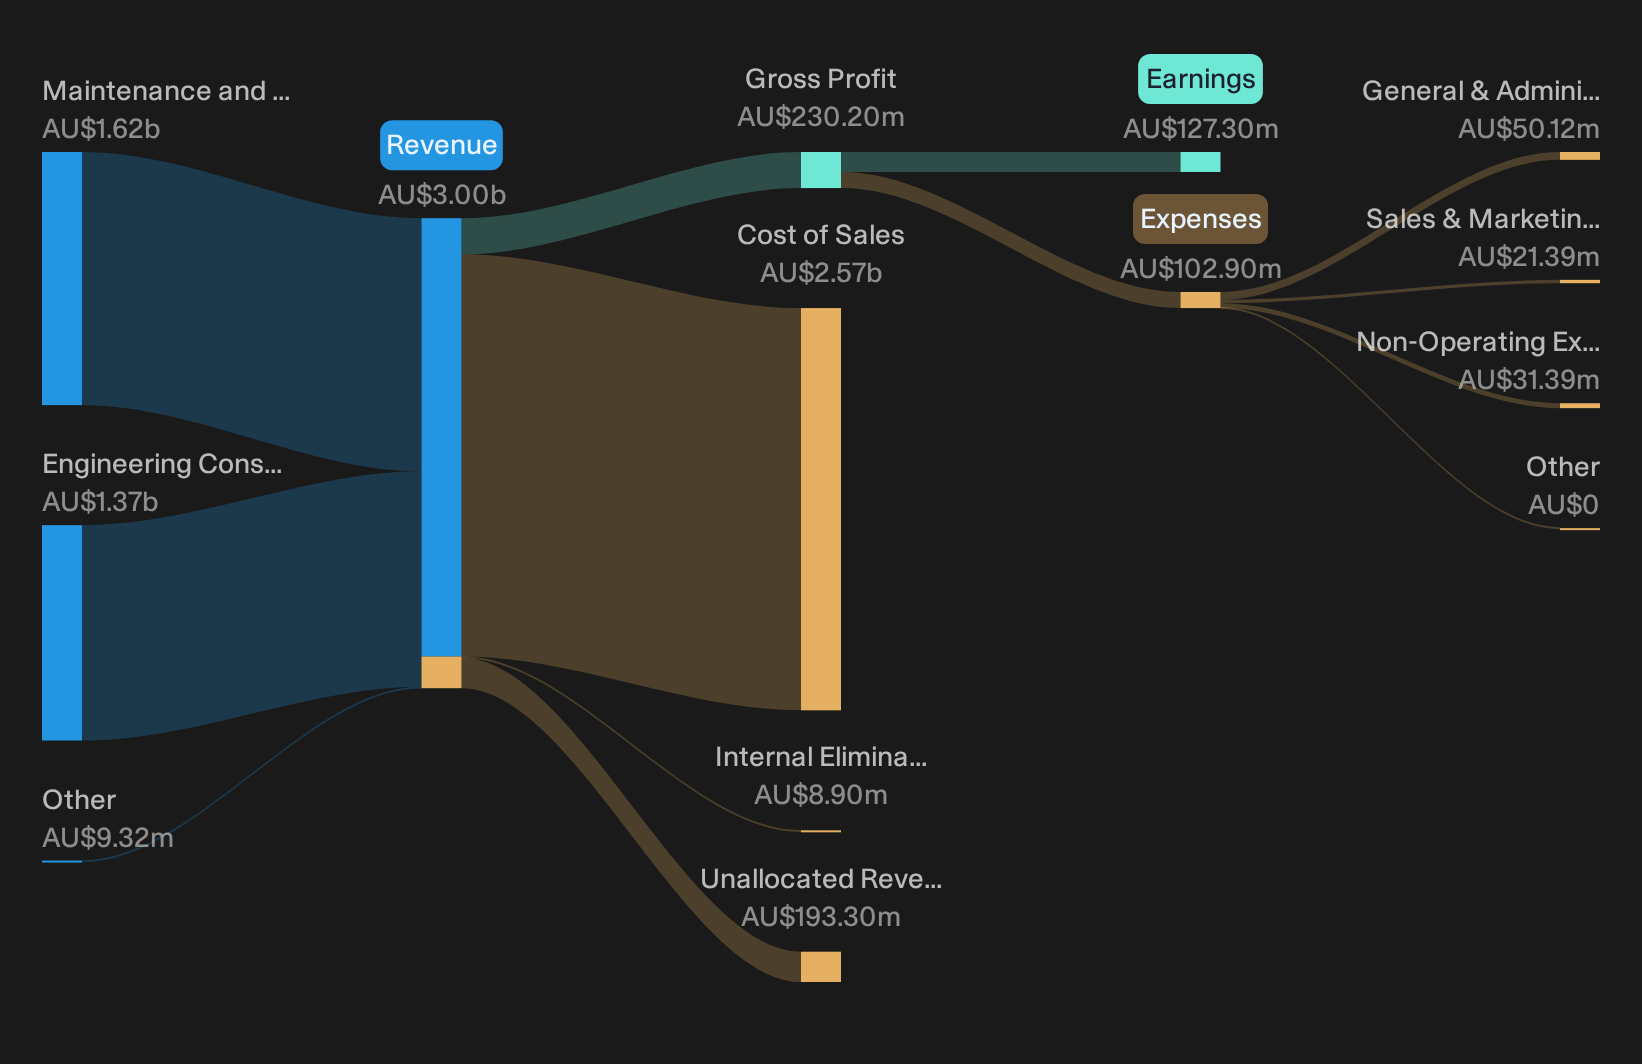
Overview: Monadelphous Group provides engineering construction, maintenance and industrial services for long term resources, energy and infrastructure projects, supporting recurring contract driven cash flows.
Operations: The group generates about A$1.37b from Engineering Construction and A$1.62b from Maintenance and Industrial Services, largely earned in Australia at A$2.73b.
Market Cap: A$3.0b
For income investors, Monadelphous Group links the Dividend Powerhouses theme to the real world of long dated energy and infrastructure projects, where recurring service work can underpin the cash needed for a 3%+ yield that aims to be both well covered and relatively predictable.
"Accelerating investment in decarbonisation and renewable energy infrastructure is now translating into tangible contract wins and a growing pipeline for Monadelphous Group, supported by more than A$2.7b of new awards and the build out of high voltage services."
The strength of that pipeline will only matter for your dividend outlook if one pressure on future execution and margins breaks the right way.
If that pressure point is what matters to you, the full narrative for Monadelphous Group shows how Monadelphous Group’s accelerating pipeline could still convert into durable dividends and contract strength.
Seeking Fresh Alternatives Beyond Dividends?
Some of the strongest future stories can start quietly, then break out as momentum builds and attention flies elsewhere. Screen these ideas before the crowd and act now.
- Spot potential turnaround stories early by scanning a curated pool of 14 high quality undiscovered gems that are still under the radar for now.
- Track where serious infrastructure money could be heading next by zeroing in on 41 power grid technology and infrastructure stocks supporting critical energy and grid upgrades.
- Ride the structural shift into machine intelligence by reviewing 40 profitable AI stocks that aren't just burning cash that already pair AI exposure with real earnings, not just promises.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com