


If you had looked at Sumitomo Chemical in late 2025, you would have seen clashing stories on paper. One bullish view framed a margin recovery and higher P/E support, while a bearish case warned that legacy petrochemicals and regulatory costs could drag value lower. Investors who held Sumitomo Chemical over the past year are up 23.1%, including dividends. If you were weighing those opposing forecasts back then, what exactly tipped the balance for you?
This theme extends beyond Sumitomo Chemical. See which of 33 best rare earth metal stocks may still merit a closer look.
The Argument You Would Have Been Weighing On Sumitomo Chemical
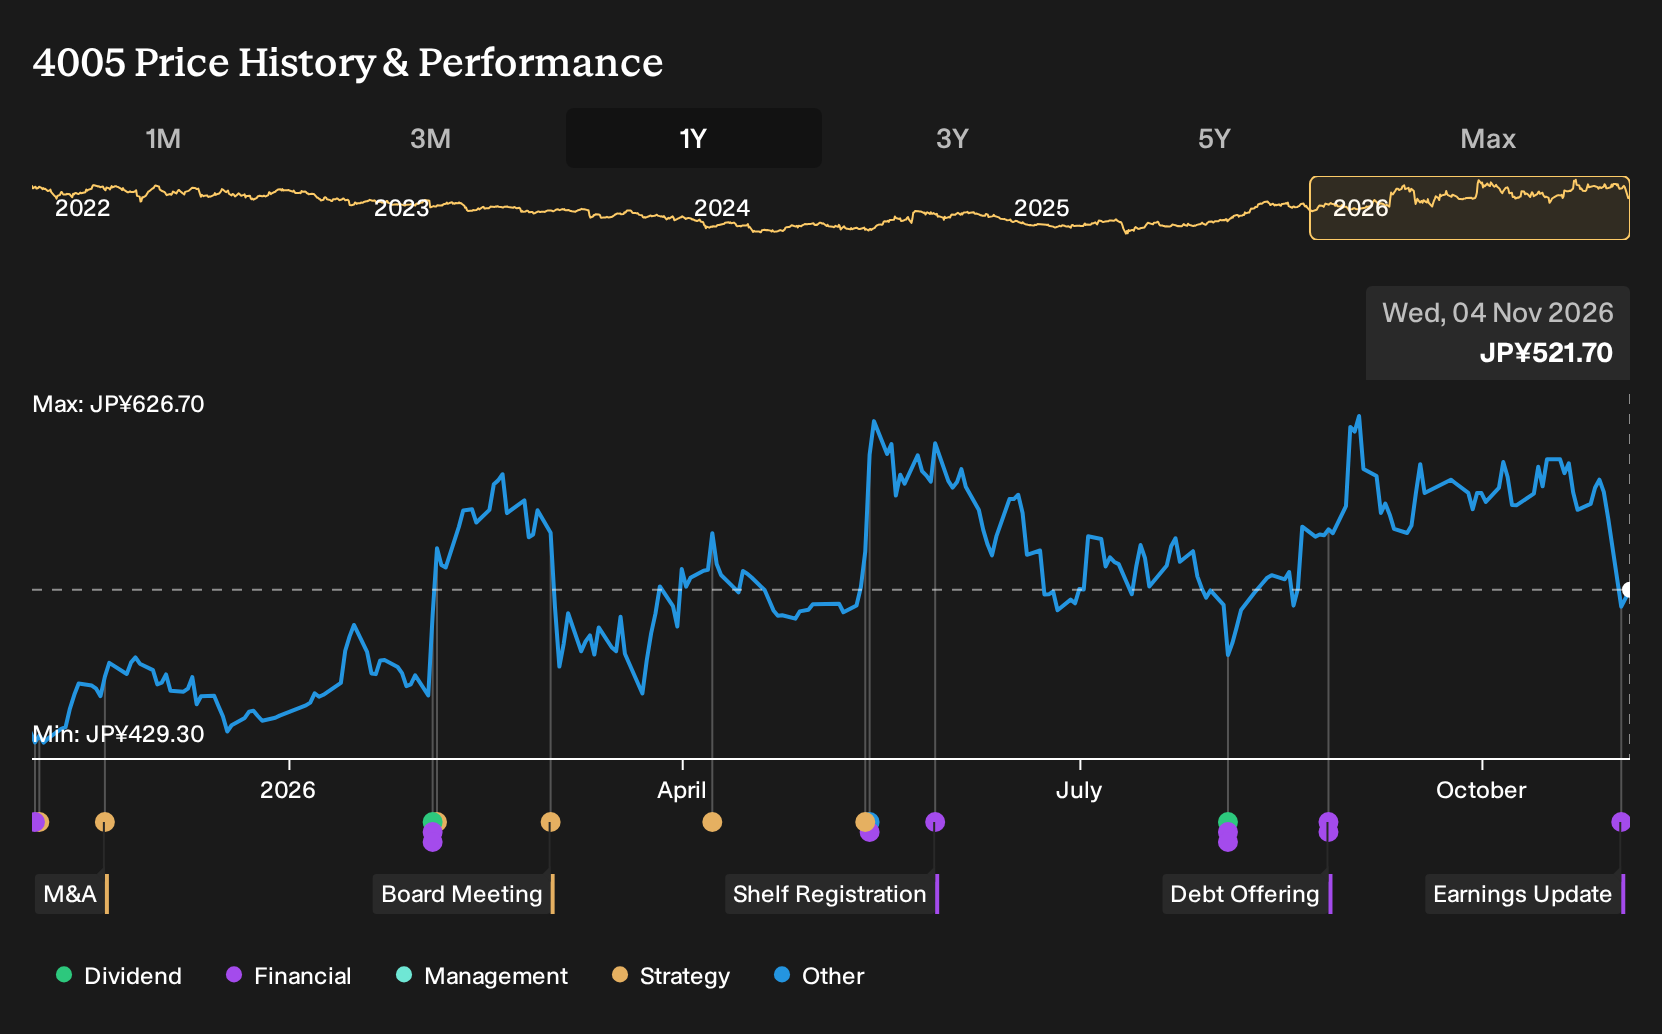
At the start of the period, Sumitomo Chemical shares cost ¥430, and investors were effectively choosing between two very different stories about where value might settle.
The optimistic camp pointed to a Fair Value of ¥497, a price implied by assumptions such as profit margins rising toward 3.4% and a future P/E of 12.1x, supported by better efficiency and portfolio streamlining.
The cautious view worked with a Fair Value of ¥320 and focused on legacy petrochemicals, where rising regulatory compliance costs and slower portfolio transition were seen as key risks.
What The Results Changed For Sumitomo Chemical
Sumitomo Chemical reported Q2 2027 revenue of ¥594,588m compared with ¥569,254m in Q2 2026, which backed the optimistic case that argued the top line could hold up. Profit told a softer story. Net income slipped from ¥44,222m to ¥42,093m and net margin moved from 7.8% to 7.1%, so the evidence cut both ways on the durability of earnings quality.
The lesson is simple. When a thesis leans on margin repair, focus on net income and net margin, not just sales. Apply the same check to any other stock where the upbeat story depends on profitability climbing, then see if reported margins actually move in that direction over time.
What Sumitomo Chemical's Price Now Asks You To Believe
With Sumitomo Chemical now at ¥519, the selected Narrative argues that its Fair Value sits above the current price and ties that gap to execution, not hype.
The focus is on shifting earnings toward Agro & Life Solutions and ICT & Mobility Solutions, underpinned by a stronger balance sheet. The live question is whether that portfolio transition can keep delivering higher quality cash flow.
"The main requirement is effective execution on the portfolio transition away from legacy petrochemicals into higher return IP centered materials and life sciences platforms, while keeping cash flow and the balance sheet on a solid footing."
One Narrative has put a figure on that disagreement. → See the Narrative with its higher Fair Value, assumptions and all
How Could You Get There Earlier?
The story behind this run has already been told. The next one could be taking shape somewhere else. Where could you start looking before it becomes the headline?
- Company 1 - 18% below our estimate - targets elevator maintenance contracts that become stickier as modernization work ramps.
- Company 2 - 49% below our estimate - leans into AI based security bundles that convert licenses into higher ARR.
- Company 3 - 42% below our estimate - expands AI driven hiring and local services matching that deepens monetization per transaction.
That is three of the list. See all 22 companies with the balance sheet to back it up →
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com