


FormFactor (FORM) just delivered third quarter results and fresh guidance that put its recent performance and capacity build out in clear focus for investors watching semiconductor test demand.
Investors have treated FormFactor as a high momentum story this year, with a year to date share price return of 63.52% and a 1 year total shareholder return of 87.14%. However, the 30 day share price decline of 35.11% and 7 day drop of 9.42% suggest enthusiasm cooled ahead of these earnings and the Farmers Branch expansion update.
Scan beyond FormFactor and spot other semiconductor test and chip infrastructure players that our analysts have already filtered into a curated list of 53 AI infrastructure stocks.
FormFactor now trades well below the average analyst target, despite that sharp year to date climb and recent pullback. Is the current quote a reasonable reflection of fair value, or a gap that valuation work cannot ignore?
Most Popular Narrative: 37.1% Undervalued
Against the last close of $96.79, the most followed narrative for FormFactor points to a fair value of $153.89, so the gap between price and that estimate is wide and backed by detailed assumptions on growth, margins and discount rate.
Investments in new manufacturing capacity at Farmers Branch, Texas and the broader operational transformation are moving into the execution phase, with US$140 to 170m of 2026 capex, a US$24.2m grant and management attributing non GAAP gross margin progress toward 53.3% in Q2 2026 to volume, operational improvements and innovation. Together these factors are described as pointing to a path for structurally higher gross margin and net margin.
See why 19 investors see FormFactor as 37% undervalued.
Result: Fair Value of $153.89 (UNDERVALUED)
Still, the FormFactor narrative depends on AI test spending and HBM heavy demand holding up, and on recent gross margin strength proving durable rather than temporary.
Find out about the key risks to this FormFactor narrative.
Another View: FormFactor Through The Cash Flow Lens
That 37.1% gap between FormFactor's share price and the $153.89 fair value narrative is only one way to look at things. Our DCF model points in a different direction, with an estimated future cash flow value of $52.11, which frames the stock as expensive and raises the question of which set of assumptions you trust more.
For readers who want to understand how a cash based model can arrive at such a different conclusion from earnings and multiple driven narratives, Look into how the SWS DCF model arrives at its fair value.
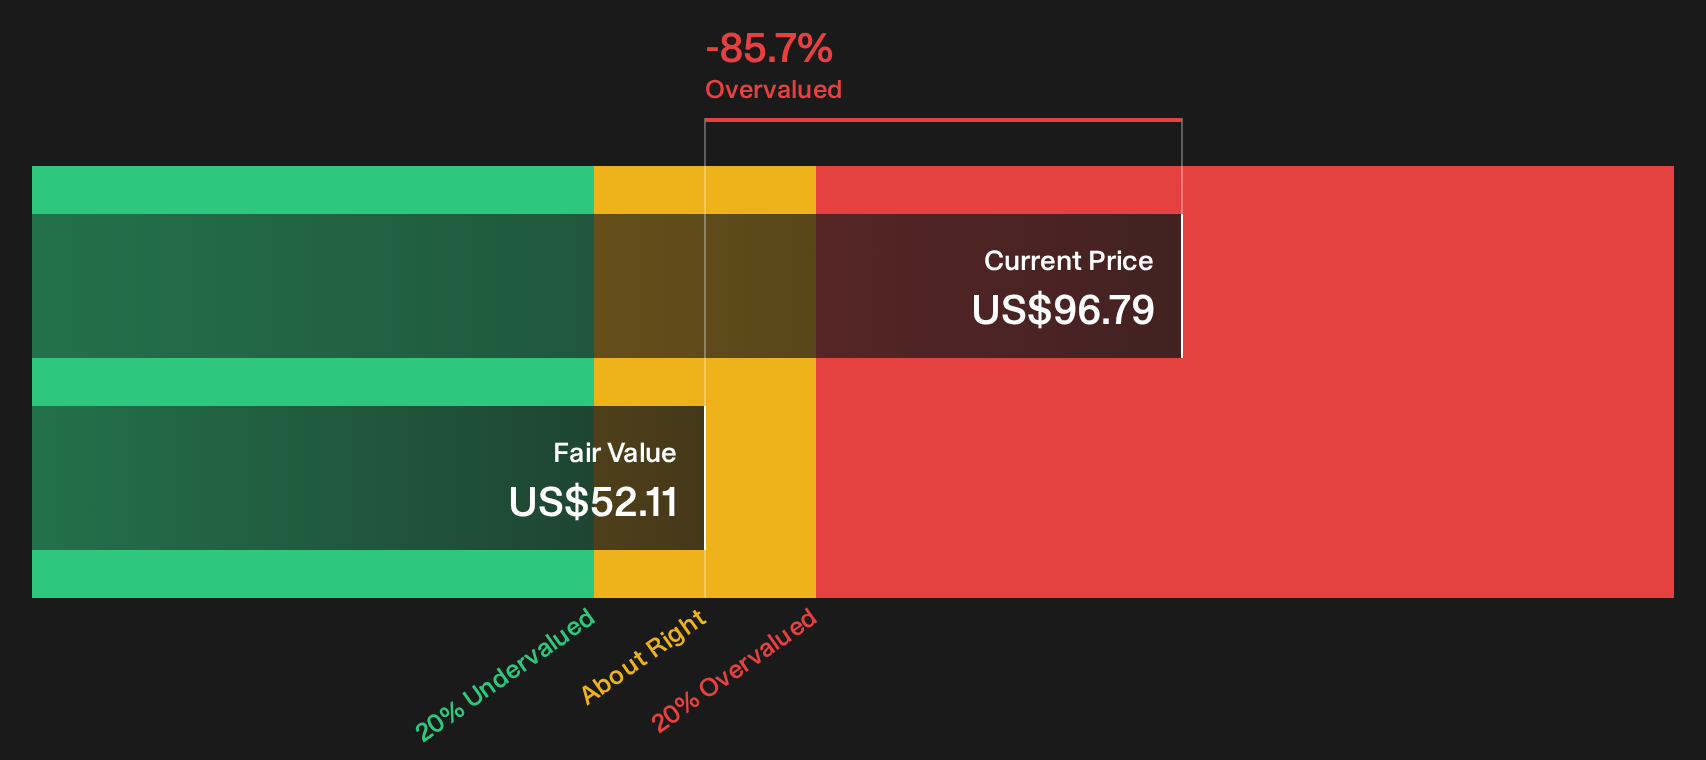
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out FormFactor for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 35 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
Mixed signals on FormFactor's value story can be energising rather than confusing, so move quickly, scrutinise the assumptions, and weigh both the 3 key rewards and 1 important warning sign
Looking for more investment ideas beyond FormFactor?
FormFactor's mixed signals can sharpen your thinking, so do not stop here when there are other opportunities that might better fit your plan.
Use the Simply Wall Street Screener to surface ideas that match your goals before the crowd locks them in.
- Target quality at a discount by tracking a curated 35 high quality undervalued stocks that filters for companies with solid fundamentals and appealing pricing.
- Prioritise resilience by scanning a focused 30 resilient stocks with low risk scores built around stocks with stronger balance sheets and milder risk scores.
- Broaden your opportunity set by reviewing a hand picked 19 high quality undiscovered gems that highlights businesses with strong financial traits yet limited attention.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com