


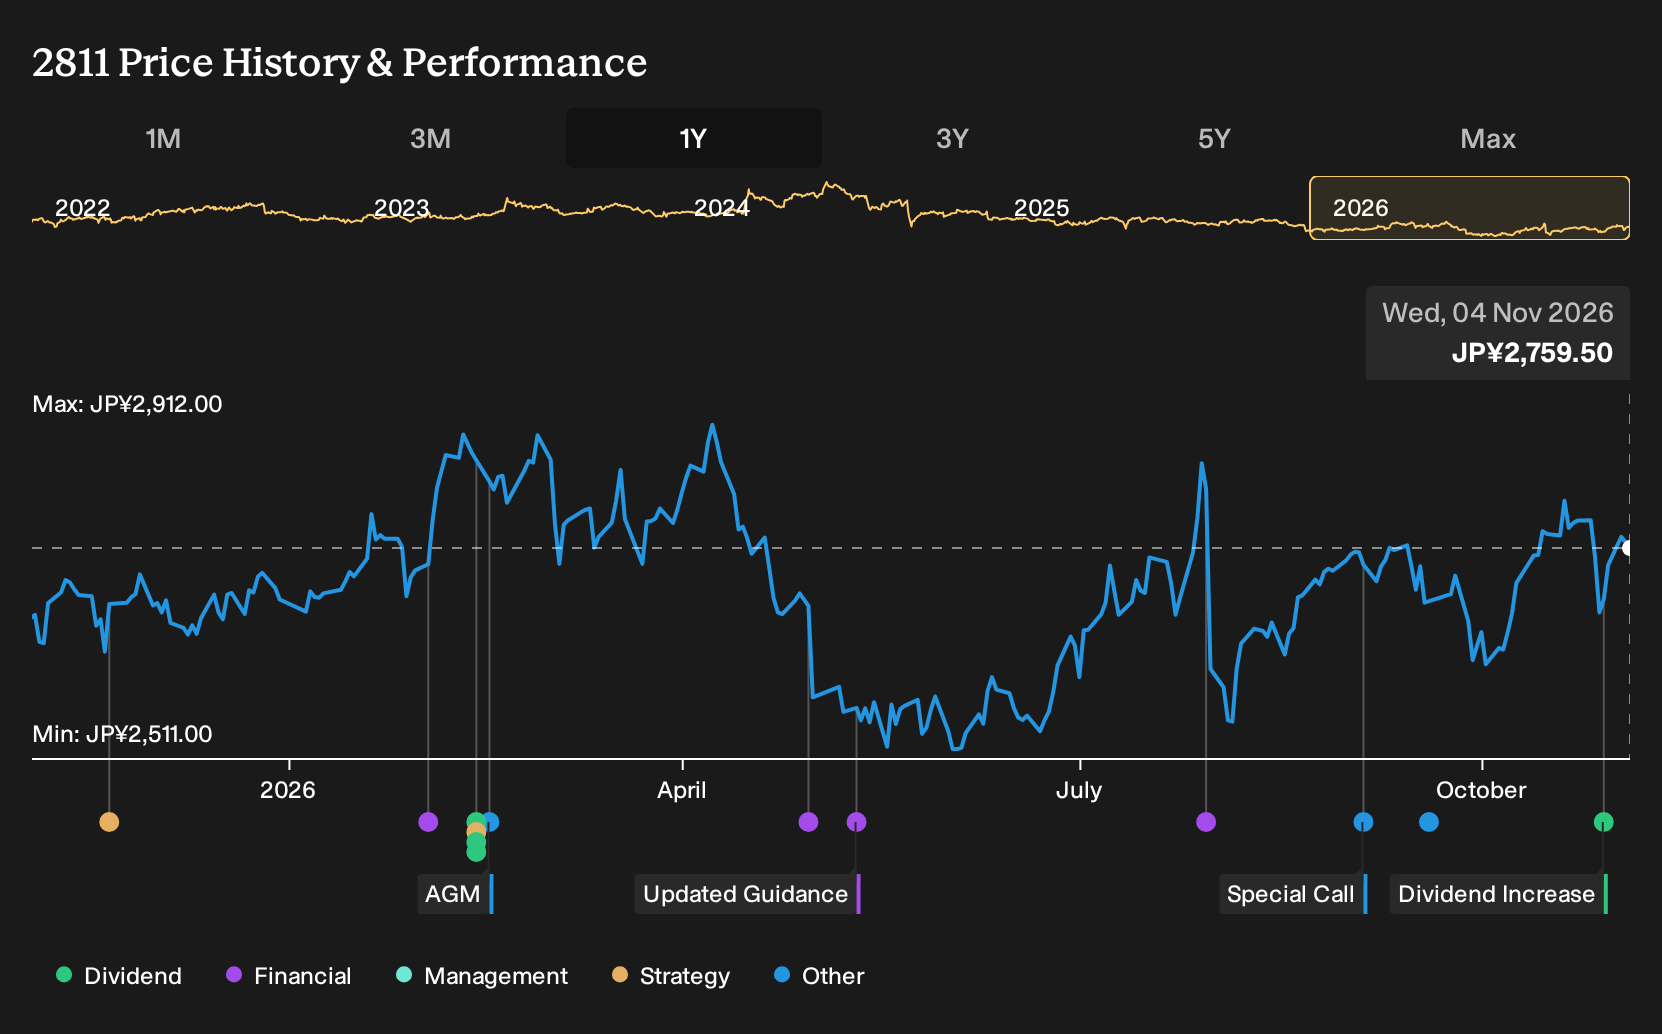
- Kagome Co., Ltd. has announced an annual dividend of JPY 58.0000 per share, with an ex-date on December 29, 2026, a record date on December 31, 2026, and payment scheduled for March 5, 2027.
- The declared payout and clear timetable underline how Kagome is prioritising direct cash returns to shareholders, which can matter for investors weighing income stability against other uses of capital such as reinvestment or debt reduction.
- The next point of interest is how Kagome's clearer cash return profile through this dividend plan may influence the broader investment narrative around the business.
What Is Kagome's Investment Narrative?
To own Kagome, you need to believe this is a steady, execution driven food producer that can keep selling tomato based products, seasonings and beverages at acceptable margins while reinvesting enough to stay relevant in both Japan and overseas. Operations are spread across domestic processed foods and international farming and processing, so the story is really about disciplined manufacturing, brand strength on the shelf and sensible capital spending rather than breakneck expansion.
The newly announced annual dividend of ¥58 per share adds another piece to that puzzle. A clear payout plan can support the case that Kagome is serious about consistent cash returns. At the same time, it raises the bar on cash generation when revenue growth is around 1.6% and earnings growth has recently cooled versus the 5 year trend. With a P/E above the broader food industry but some indicators suggesting undervaluation, execution on pricing, cost control and overseas projects matters more than ever.
Yet the more interesting tension only shows up once you consider ...
There's only one way to know the right time to buy, sell or hold Kagome. Head to Simply Wall St's company report for the latest analysis of Kagome's Fair Value.
Decide For Yourself
Don't just follow the ticker; dig into the data and build a conviction that's truly your own.
- A great starting point for your Kagome research is our analysis highlighting 4 key rewards that could impact your investment decision.
- See our latest analysis for Kagome. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Kagome's overall financial health at a glance.
Looking For More Investment Ideas Beyond Kagome?
Once you have formed a view on Kagome, it can help to compare it with other companies that match your income, quality or risk preferences. The Simply Wall St Screener can surface groups of stocks that share the traits you care about most.
- If you want income with resilience, focus on businesses that pair sizeable payouts with balance sheets built to withstand stress, starting with this 32 dividend fortresses.
- For investors who care most about paying a reasonable price for quality, target resilient businesses that score well on valuation and fundamentals using this 19 high quality undervalued stocks.
- If you prefer stability over drama, concentrate on companies with lower risk scores and steadier profiles by working through this 22 resilient stocks with low risk scores.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com