


Intapp (INTA) is back in focus after first quarter results on October 27 showed a narrower basic loss per share, new revenue guidance for 2027, and confirmation of a completed share repurchase program.
Intapp’s first quarter update landed after a strong run, with a 30-day share price return of 22.77% and a 90-day gain of 21.21%. The 1-year total shareholder return of 20.85% and 5-year total shareholder return of 52.54% point to momentum that has been building rather than fading.
Spot similar earnings momentum and buyback stories to Intapp by scanning a hand picked set of 35 high quality undervalued stocks that currently screen well on both cash flows and balance sheets.Bulls see Intapp’s sharper loss improvement and buyback as proof the recent jump still leaves upside. Skeptics point to ongoing losses and rich expectations. Which case does the current valuation actually support?
Most Popular Narrative: 8% Overvalued
At a last close of $44.80 against a widely followed fair value estimate of $41.57, Intapp is framed as trading at a premium that leans heavily on its longer term AI and workflow thesis.
Intapp's recent investments in AI capabilities, including the launch of Intapp DealCloud Activator and the transformed Intapp Time product, are designed to drive client engagement and operational efficiencies. These developments are expected to bolster revenue by enhancing product appeal and encouraging cloud adoption among existing and potential clients.
See why 15 investors see Intapp as 8% overvalued.
Result: Fair Value of $41.57 (OVERVALUED)
Still, the whole Intapp story hinges on partner delivered services and cloud migrations not slipping, since cost overruns or client churn could quickly challenge that AI fueled premium.
Find out about the key risks to this Intapp narrative.
Another View: Intapp Through a Cash Flow Lens
Analyst targets frame Intapp as about 8% overvalued at $44.80 versus the $41.57 fair value narrative. The SWS DCF model points in the opposite direction, with an estimated future cash flow value around $78.25 per share, implying the market price leaves a wide upside gap instead of a premium.
Both signals cannot be right at the same time. Which set of assumptions about growth, margins, and discount rates do you find more realistic?
Look into how the SWS DCF model arrives at its fair value.
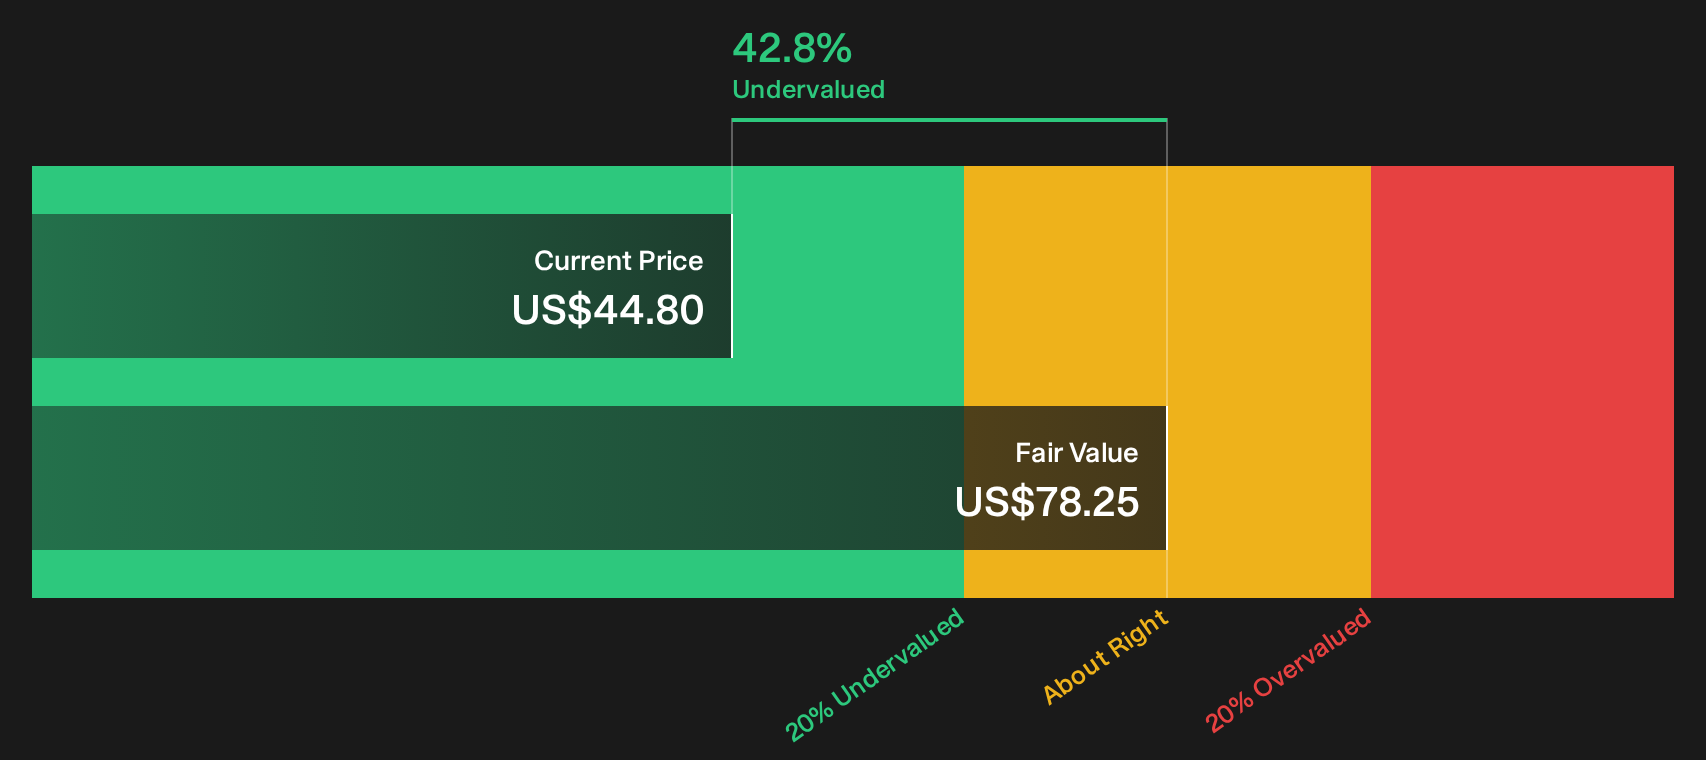
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out Intapp for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 35 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
Sentiment on Intapp is clearly split, so this is the moment to move fast, weigh the evidence yourself, and pressure test the upside story. To see what optimists are focusing on, review the 2 key rewards
Looking for more investment ideas beyond Intapp?
Do not stop with Intapp. Use the Simply Wall Street Screener to surface fresh opportunities that match your risk comfort, income goals, and balance sheet standards.
- Target potential upside by zeroing in on companies that currently look mispriced relative to their fundamentals using our 35 high quality undervalued stocks.
- Strengthen your income stream by focusing on businesses with generous payouts and resilient cash generation through the 4 dividend fortresses.
- Prioritize resilience by filtering for financially robust operators with conservative leverage and strong liquidity using the 30 resilient stocks with low risk scores.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com