


Altria Group (MO) reported stronger third quarter results and raised its full-year earnings outlook, while also putting a new universal shelf registration in place for potential funding.
Altria Group’s recent earnings beat and higher full-year guidance come after a strong run in the shares, with a 30-day share price return of 14.24% and a year-to-date share price return of 34.25% pointing to building momentum rather than a short-lived bounce. That move sits on top of hefty income and reinvested dividends, reflected in a 1-year total shareholder return of 43.33% and a 5-year total shareholder return of 152.23%. This suggests investors have been willing to re-rate the stock as the business funds smoke-free products, maintains high cash returns and now prepares for flexible future funding through the new universal shelf registration.
Compare Altria Group's momentum and income profile against a curated list of higher-yield peers using the 4 dividend fortresses as a starting universe.
After a 34% year to date climb and a richer earnings outlook, Altria Group now poses a simple timing question. Is it worth stepping in at this level, or does patience for a cheaper entry make more sense, as the valuation section shows?
Most Popular Narrative: 6% Overvalued
The most followed valuation view now puts Altria Group’s fair value at $72.55, slightly below the last close at $76.94. This frames the recent rally as stretching beyond that reference point.
Expansion of Altria Group's on! and on! PLUS nicotine pouch platform, with the category now close to 60% of oral tobacco volume and year to date shipment volume for on! up 5.1%, positions smoke free products to contribute more meaningfully to revenue and earnings.
Additional FDA marketing approvals for Helix nicotine pouches, bringing the total number of authorized pouch products to 30, create scope for broader distribution and future line extensions that can support oral tobacco revenue growth.
See why 267 investors see Altria Group as 6% overvalued.
Result: Fair Value of $72.55 (OVERVALUED)
Still, the narrative around Altria Group can shift quickly if trade down in cigarettes deepens or if legal and regulatory actions increase costs and uncertainty.
Find out about the key risks to this Altria Group narrative.
Another View On Altria Group’s Valuation
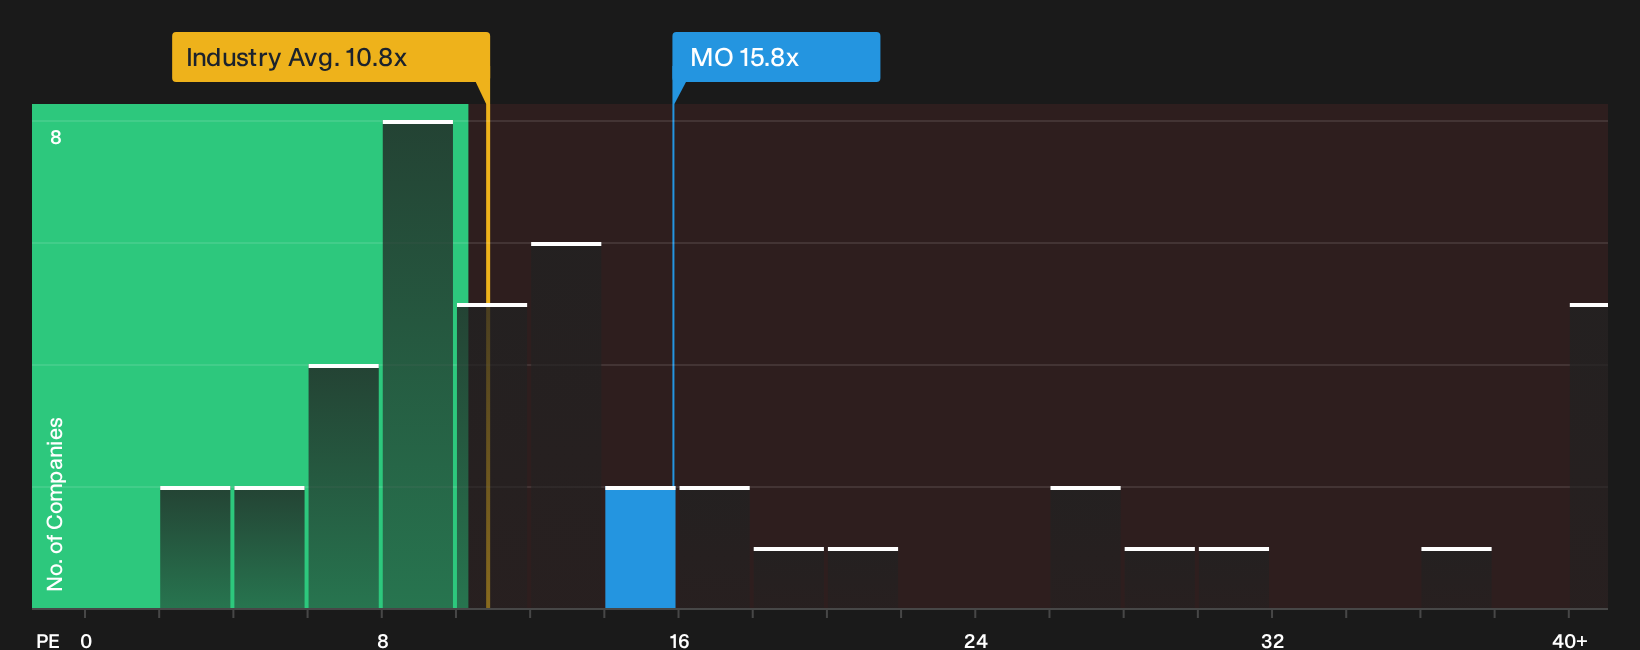
The first narrative paints Altria Group as roughly 6% overvalued against a $72.55 fair value. A different lens tells a sharper story. On Simply Wall St’s fair ratio, Altria trades on a P/E of 15.8x versus a fair ratio of 23.4x, which flags a sizeable valuation gap that could close either way.
That same P/E sits well above the Global Tobacco average of 10.8x, yet below a 31x peer average. Investors therefore face a mix of possible upside toward the fair ratio and downside if the market leans closer to the industry level. The key question is which benchmark you believe the stock will drift toward over time, and why.
See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Curious whether the mixed signals around Altria Group tilt you more toward caution or optimism? Act while the data is fresh and weigh both sides with the 3 key rewards and 1 important warning sign
Looking for more investment ideas beyond Altria Group?
If you stop with Altria Group, you only see one angle. Take a few minutes to scan wider and you might spot tomorrow’s opportunity before most investors.
- Target resilient compounding potential by reviewing companies with steady fundamentals and manageable debt using the list of solid balance sheet and fundamentals (23 results).
- Hunt for mispriced quality by scanning the 19 high quality undiscovered gems that combine robust financials with lower market attention.
- Lock in portfolio stability by comparing high-yield payers through the 4 dividend fortresses.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com