


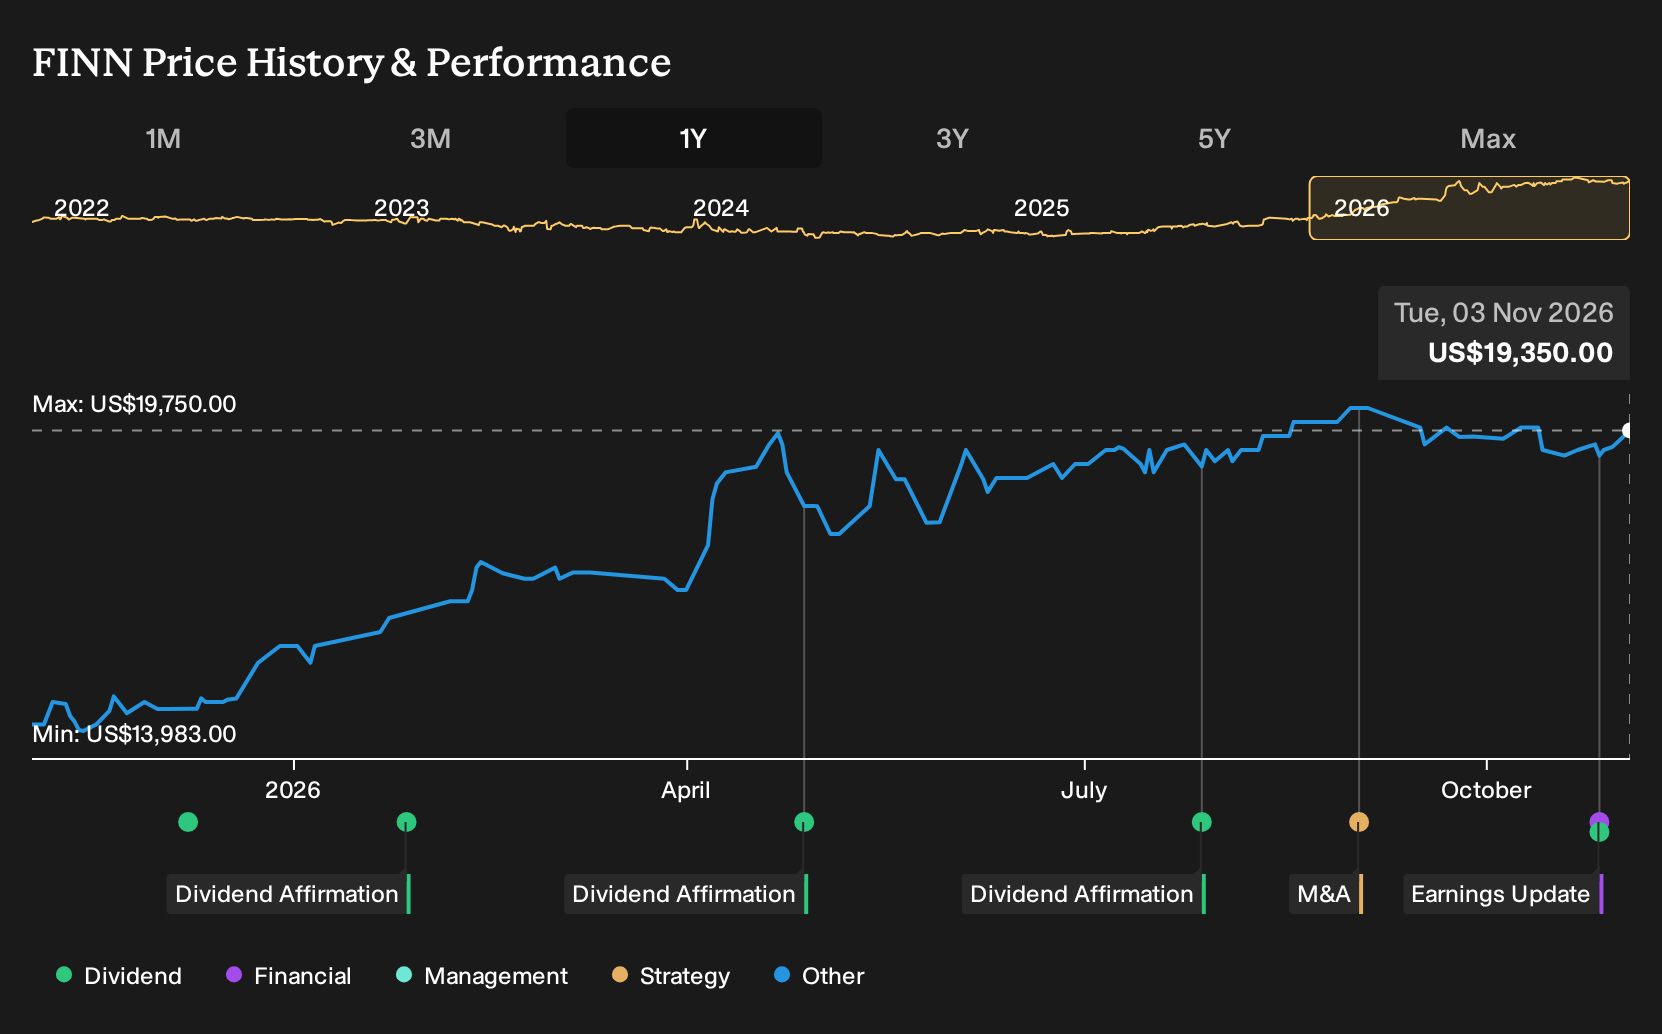
- First National of Nebraska reported third quarter 2026 net interest income of US$533 million and net income of US$175 million, with nine month net income of US$493 million, and affirmed a quarterly dividend of US$40.00 per share that was paid on November 23, 2026.
- The combination of higher net income for both the quarter and year to date and a maintained dividend points to a business model that currently funds shareholder payouts from ongoing banking operations rather than one off actions.
- This article examines how First National of Nebraska's higher quarterly net income shapes the investment narrative around its earnings quality.
What Is First National of Nebraska's Investment Narrative?
For a shareholder in First National of Nebraska, the core belief is that a privately controlled regional bank can keep turning solid banking spreads into cash earnings that support a premium share price and periodic dividends. The latest quarter fits that story. Net interest income of US$533 million and net income of US$175 million, alongside the affirmed US$40.00 dividend, point to a business that currently covers shareholder payouts through ongoing operations rather than one off actions.
In the short term, the key swing factors are fairly practical. You are essentially betting that First National of Nebraska can keep pricing loans and credit cards carefully enough to protect net interest income, while managing funding costs in a model that leans on higher risk wholesale liabilities rather than customer deposits. The fresh earnings numbers suggest the existing playbook is still working, although the history of an unstable dividend track record keeps the payout story from feeling entirely settled.
Yet there is one funding related pressure point that could matter a lot more if credit conditions shift and that is where ...
There's only one way to know the right time to buy, sell or hold First National of Nebraska. Head to Simply Wall St's company report for the latest analysis of First National of Nebraska's Fair Value.
Form Your Own Verdict
Don't just follow the ticker. Dig into the data and build a conviction that's truly your own.
- A great starting point for your First National of Nebraska research is our analysis highlighting 2 key rewards and 2 important warning signs that could impact your investment decision.
- See our latest analysis for First National of Nebraska. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate First National of Nebraska's overall financial health at a glance.
Looking For More Investment Ideas Beyond First National of Nebraska?
If you want to stress test your thinking and see how First National of Nebraska compares with other opportunities, broaden your watchlist using the Simply Wall St Screener. Pick a few different angles, then see which businesses keep showing up across multiple filters.
- For investors who like combining quality with value, scan for companies that pass our high quality filter in the 35 high quality undervalued stocks.
- If income resilience matters most to you, focus on stocks that feature in the 4 dividend fortresses.
- When capital preservation is a priority, start with companies that appear in the 30 resilient stocks with low risk scores.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com