


Hope Bancorp (HOPE) drew investor attention after releasing third quarter results and issuing full year 2026 guidance that points to double digit growth expectations in loans, revenue, and pre provision net revenue.
Recent trading tells a mixed story for Hope Bancorp. The share price has pulled back with a 7 day share price return of 5.55% and a 90 day share price return of 6.09%. At the same time, the year to date share price return sits at 19.40% and the 1 year total shareholder return is 29.59%, with a 3 year total shareholder return of 61.86% and a 5 year total shareholder return of 7.91%. This points to longer term holders still sitting on meaningful gains while near term sentiment cools following the latest earnings, guidance, higher net charge offs and the reaffirmed dividend.
Compare Hope Bancorp's guidance-driven story with other banks showing meaningful balance sheet strength and earnings momentum by scanning the curated list of solid balance sheet and fundamentals (23 results).
Hope Bancorp now pairs double digit growth ambitions with a share price that has cooled in recent weeks. Is that combination still offering you a fair deal, or has the valuation already caught up?
Most Popular Narrative: 15.4% Undervalued
Against the last close of $13.11, the most followed narrative on Hope Bancorp points to a fair value of $15.50, so the current price sits at a clear discount while investors weigh how durable the recent turnaround really is.
The valuation suggests that the market remains cautious about Hope Bancorp’s ability to turn current loan, revenue, and efficiency progress into stronger long term shareholder value, given its historically flat net interest income, declining EPS, and plateaued tangible book value per share.
See why 9 investors see Hope Bancorp as 15% undervalued.
Result: Fair Value of $15.50 (UNDERVALUED)
Still, if commercial real estate credit costs spike or California and Hawaii weaken, the bullish Hope Bancorp narrative could face significant pressure.
Find out about the key risks to this Hope Bancorp narrative.
Another View: What P/E Says About Hope Bancorp
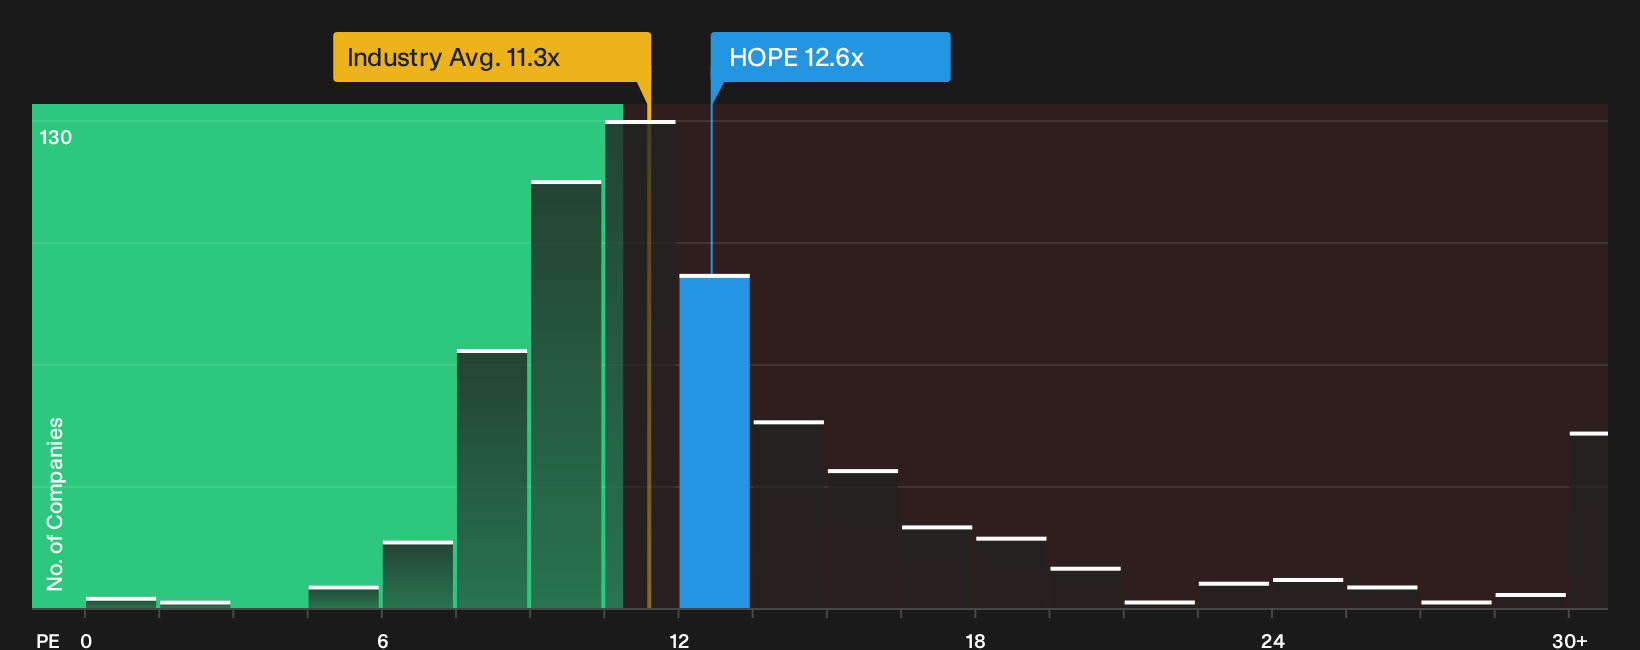
That 15.4% discount to a $15.50 fair value suggests upside on paper. Yet through a simple P/E lens, Hope Bancorp trades at 12.6x earnings. This is richer than the US Banks industry on 11.3x, even though it screens cheaper than peers on 17.1x and below a fair ratio of 14.5x the market could move toward. Is that gap a sign of limited upside from here or a pricing quirk you are comfortable with?
See what the numbers say about this price in our valuation breakdown, starting with the See what the numbers say about this price — find out in our valuation breakdown..
Next Steps
Sentiment around Hope Bancorp is mixed, and that is exactly when fresh eyes on the data can matter most for your portfolio. Before you decide what the recent guidance and valuation gap really mean, take a moment to see why investors are still highlighting 4 key rewards
Looking for more investment ideas beyond Hope Bancorp?
If Hope Bancorp has your attention, do not stop there. Broaden your watchlist now so you are not relying on a single story to drive returns.
- Spot potential value plays early by scanning the 35 high quality undervalued stocks that combine solid fundamentals with prices the market may not be fully appreciating yet.
- Strengthen the foundation of your portfolio by filtering for resilient balance sheets through the list of solid balance sheet and fundamentals (23 results) that can better handle tougher conditions.
- Hunt for future leaders off the beaten path by reviewing the 19 high quality undiscovered gems before the crowd turns its attention there.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com