


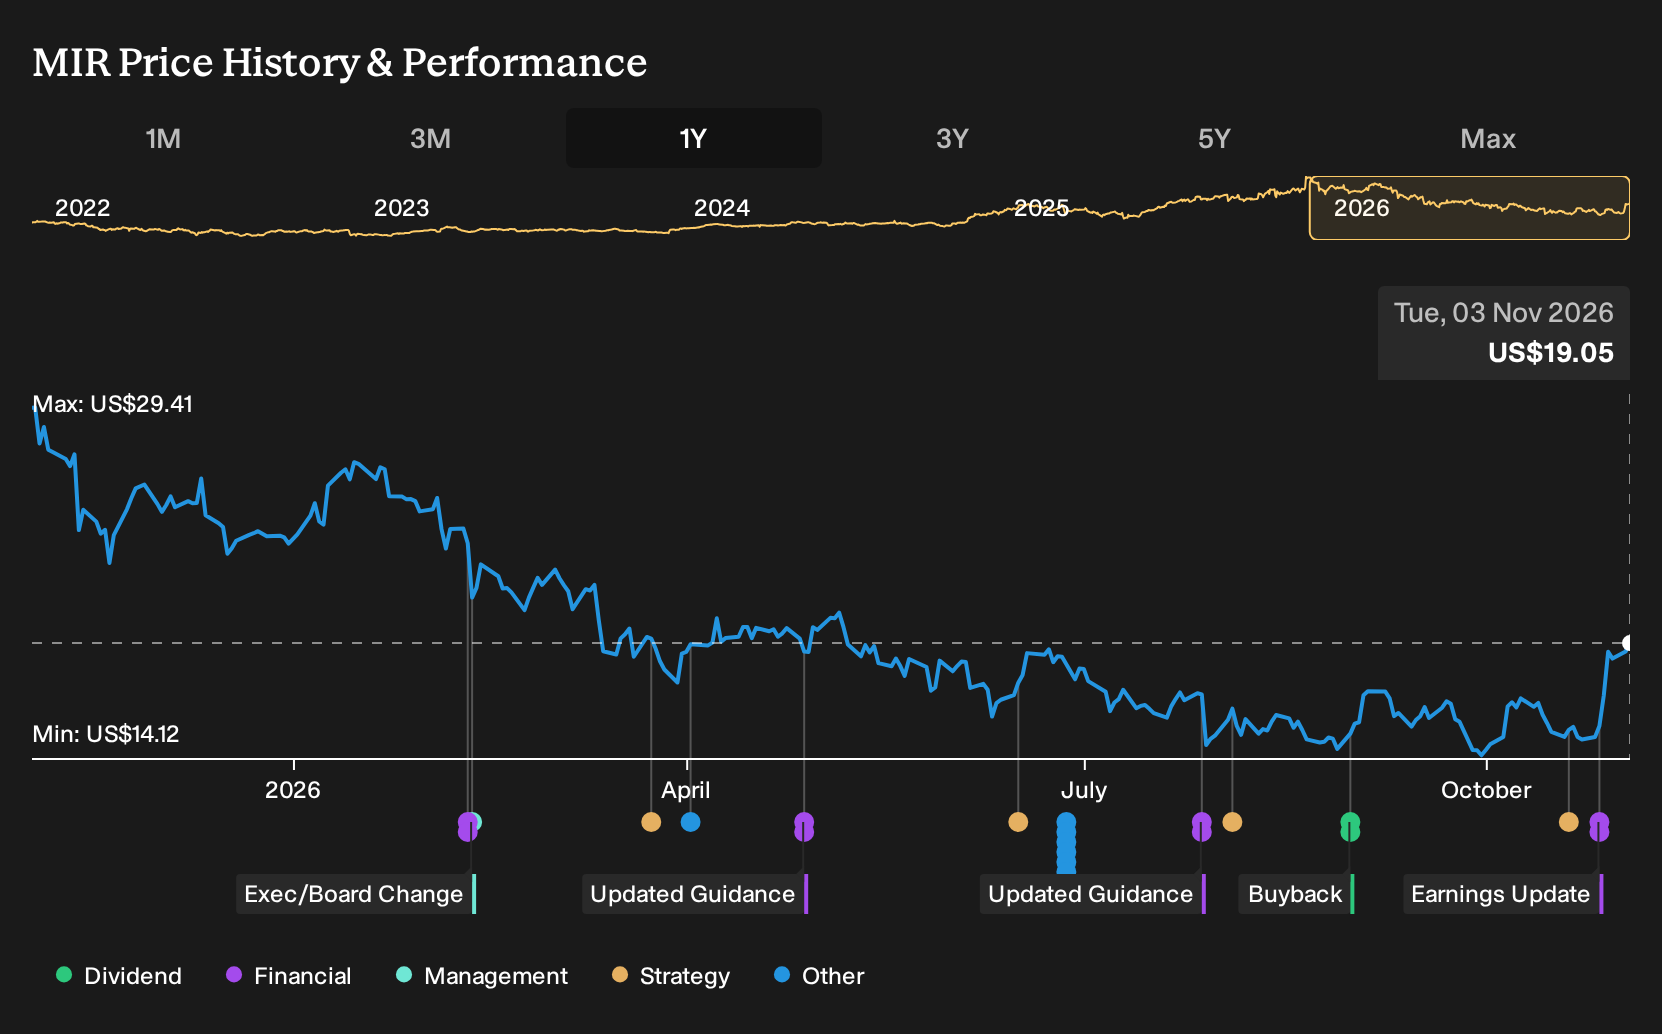
- Mirion Technologies reported third quarter 2026 revenue of US$277.8 million and net income of US$7.4 million, alongside updated full year 2026 guidance that now points to 24% to 25% revenue growth including foreign exchange and acquisition effects.
- The combination of higher quarterly earnings per share from continuing operations and a raised revenue outlook indicates that Mirion Technologies is balancing expansion and acquisitions with continued profitability rather than prioritizing scale at the expense of current earnings.
- We will now look at how Mirion Technologies' upgraded full year revenue growth guidance interacts with its existing investment narrative and risks.
Scan beyond Mirion Technologies and line up other potential beneficiaries of this kind of revenue momentum with a curated list of 16 nuclear energy infrastructure stocks.
Mirion Technologies Investment Narrative Recap
To own Mirion Technologies, you need to be comfortable with a radiation-focused equipment and software supplier that relies heavily on nuclear and healthcare demand, as well as acquisitions, to grow. The raised 2026 revenue growth guidance to 24% to 25% reinforces that the near-term story is about converting a strong order backdrop into higher sales while maintaining profitability.
The key short-term catalyst is continued execution on that higher revenue base while keeping earnings quality intact, particularly after large one-off items in the last 12 months. The biggest risk is that acquisition and integration costs, together with debt service that is not well covered by operating cash flow, limit margin and cash progress.
The most relevant update is Mirion Technologies lifting its 2026 revenue growth outlook to about 24% to 25%, including foreign exchange and acquisition effects. That target now sits against nine-month sales of US$802.2 million and net income of US$11.7 million, which are broadly flat on profit despite higher turnover.
This mix matters for catalysts. Stronger top-line guidance supports the idea that nuclear and medical demand remains healthy, while modest earnings so far highlight the execution risk around integration, cost control, and interest expense. In the short term, investors are likely to watch whether reported cash flow and margins start to better reflect the higher revenue base.
Mirion Technologies' current analyst narrative points to revenue of US$1.4b and earnings of US$162.6 million by 2029, based on forecast yearly top-line growth of 8.9%. That projection implies earnings rising by about US$133.6 million from US$29.0 million today, which is roughly a 5.6x increase in profit over the period.
Uncover why Mirion Technologies' fair value indicates a 24% potential upside to its current price, which could narrow quickly.
Exploring Other Perspectives
One bullish twist on Mirion Technologies focuses on the fast build up in nuclear and installed base backlog above US$1.1b. Prior to this earnings print, the most optimistic analysts were already penciling in roughly 10% yearly revenue growth and earnings of about US$158.4 million by 2029. You can treat this quarter and the raised 2026 growth outlook as fresh information that might reshape those optimistic expectations, and compare them with more cautious views before deciding which story feels more realistic to you.
Explore 3 other Mirion Technologies fair value estimates, including one that suggests there may be as much as 24% upside from the current price!
Decide For Yourself
Don't just follow the ticker. Dig into the data and build a conviction that's truly your own.
- A great starting point for your Mirion Technologies research is our analysis highlighting 4 key rewards and 2 important warning signs that could impact your investment decision.
- See our latest analysis for Mirion Technologies. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Mirion Technologies' overall financial health at a glance.
Looking For More Ideas Beyond Mirion Technologies?
Once you have a view on Mirion Technologies, it can help to set it alongside other opportunities with different risk and income profiles. A broad watchlist gives context for the growth, balance sheet and cash generation you see here.
- If you want to focus on financial quality and valuation together, scan a curated 35 high quality undervalued stocks that pair stronger fundamentals with prices that may not fully reflect them yet.
- For investors who care most about resilience and capital preservation, compare Mirion Technologies with a 30 resilient stocks with low risk scores that screen well on stability metrics.
- If balance sheet strength is your anchor, round out your shortlist with a list of solid balance sheet and fundamentals (23 results) that can help you stress test your portfolio against tougher conditions.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com