


MetLife (MET) heads into its upcoming third quarter earnings report, with investors zeroing in on premium trends, digital efficiency gains, underwriting results, and how policy benefits and expenses shape the insurer's overall health.
Recent trading reflects that anticipation. MetLife’s share price is up 25.34% year to date and the 1-year total shareholder return of 30.14% sits on top of an 84.31% total return over three years, indicating momentum has been building as investors position ahead of the earnings release.
Scan how MetLife stacks up against other insurers by weighing it alongside a curated list of 30 resilient stocks with low risk scores that have shown resilience when earnings expectations come into focus.
After a run that strong, the real tension is simple. Do you pay up for MetLife before earnings, or wait and see if the next swing offers a cheaper shot at the same story?
Most Popular Narrative: 6% Undervalued
MetLife’s most followed narrative pegs fair value at about $107 per share, a touch above the recent $100.67 close. This puts the current debate on how durable its growth and cash generation really are into focus.
Continued execution of the New Frontier program, which has already been associated with 10% EPS growth in 2025, a 17% adjusted ROE in the first half of 2026 and direct expense ratios at or better than target, suggests further scope to sustain earnings and free cash flow that underpin MetLife’s current valuation.
See why 29 investors see MetLife as 6% undervalued.
Result: Fair Value of $107 (UNDERVALUED)
Still, the MetLife narrative can wobble if fee based earnings at MetLife Investment Management stay pressured or if Retirement and Income Solutions spreads remain below guidance for an extended period.
Find out about the key risks to this MetLife narrative.
Another View: MetLife Through The P/E Lens
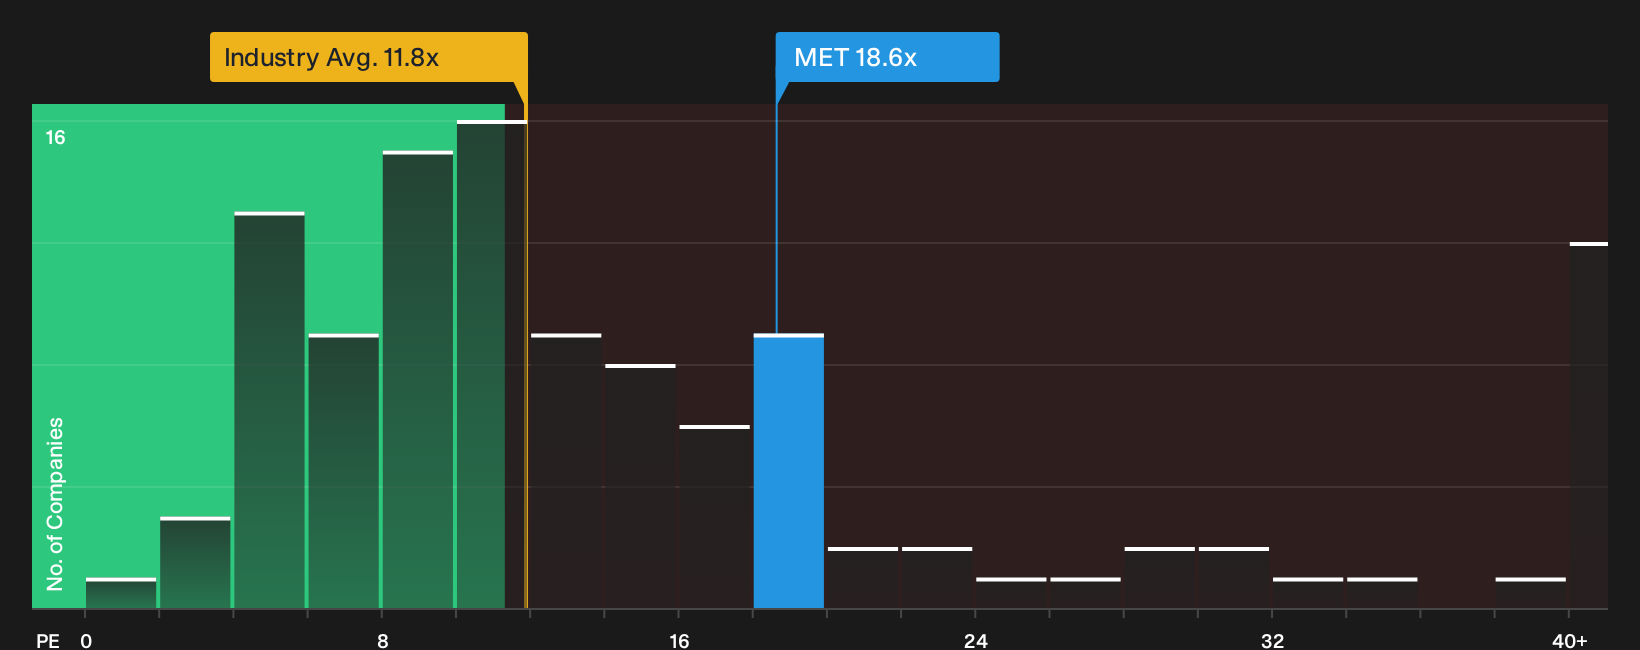
The SWS DCF model points to MetLife trading below an estimated future cash flow value of $172.53, yet the P/E story is less forgiving. At 18.6x earnings, the stock is priced well above the US Insurance industry at 11.5x, peers at 14x, and even its own 14.7x fair ratio. That richer tag can shrink the margin for error if earnings or sentiment slip. How much premium are you comfortable paying for this narrative?
See what the numbers say about this price, find out in our valuation breakdown See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Mixed messages rarely resolve themselves. With both risks and rewards on the table for MetLife, use the data, act early, and weigh the 3 key rewards and 1 important warning sign.
Looking for more MetLife sized investment ideas?
If MetLife has you thinking harder about where to put fresh capital, do not stop here. The right watchlist can start with one smart search.
- Target robust cash flows and pricing power by scanning a 35 high quality undervalued stocks that filters for quality businesses trading below their implied value.
- Focus on income potential by reviewing a curated 4 dividend fortresses that screens for higher yield opportunities with staying power.
- Build staying power into your portfolio by using a list of solid balance sheet and fundamentals (23 results) that highlights companies with stronger finances backing their stories.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com