


Acushnet Holdings (GOLF) just released third quarter results that showed relatively steady sales with small gains in profit and earnings per share. For the nine month period, both revenue and net income were higher year over year.
At a share price of $87.41, Acushnet Holdings has seen short term momentum pick up, with a 7 day share price return of 5.98% and a 30 day share price return of 4.49%, even though the 90 day share price return is down 15.26% as investors digest the latest earnings update. Over a longer stretch, total shareholder return of 17.41% over one year and 66.22% over five years points to investors being rewarded for staying the course despite recent volatility.
Compare Acushnet Holdings with other golfers-focused manufacturers by scanning hand-picked 35 high quality undervalued stocks that pair resilient cash generation with disciplined balance sheets.
After a sharp pullback over 90 days, Acushnet Holdings now trades at a discount to both analyst targets and some intrinsic value estimates. Is the market simply cautious, or is that wariness aligned with the fundamentals?
Most Popular Narrative: 12% Undervalued
On the most followed narrative, Acushnet Holdings screens below its implied fair value of about $99.67, while the last close is $87.41. That gap puts attention firmly on whether the golf specialist can turn its investments in capacity and systems into stronger long term cash generation.
The company’s focus on premium performance products and custom fitting across Titleist equipment and FootJoy, supported by first half 2026 growth in higher end clubs and improved FootJoy margins, points to further mix driven uplift in net margins and EBITDA.
Acushnet’s multi year expansion of golf ball manufacturing capacity in Massachusetts and Thailand, with plants currently running near full capacity and new cast urethane lines planned over the next one to two years, could allow the company to convert demand into higher sales and operating leverage.
See why 3 investors see Acushnet Holdings as 12% undervalued.
Result: Fair Value of $99.67 (UNDERVALUED)
Still, a few cracks matter here, including weaker free cash flow and insider selling, which could influence how investors view the Acushnet Holdings story.
Find out about the key risks to this Acushnet Holdings narrative.
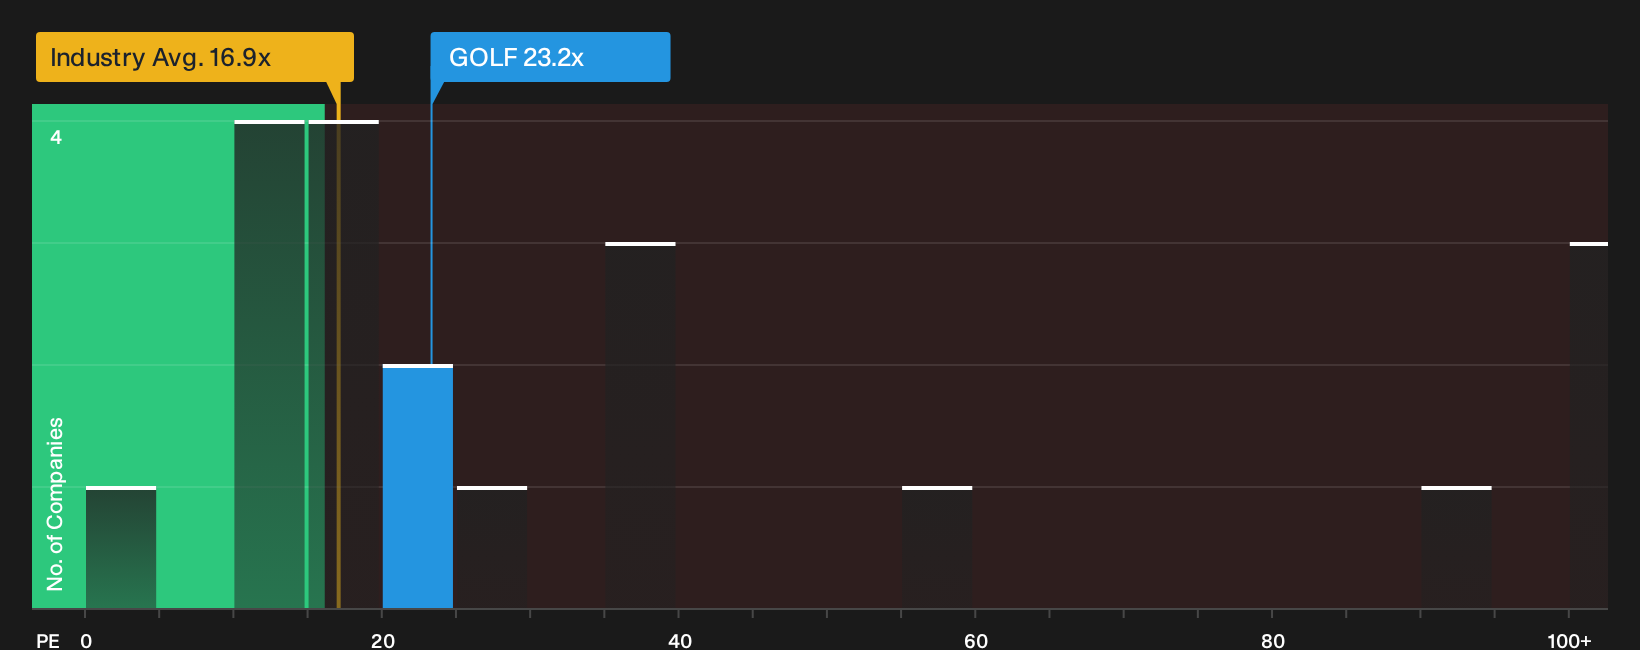
Another View: Acushnet Holdings Through The P/E Lens
Acushnet Holdings might look appealing on fair value models, yet the simple earnings multiple tells a tighter story. The current P/E of 23.2x is higher than both the peer group at 22.3x and the fair ratio estimate of 16.7x. That gap suggests investors are already paying up. If sentiment cools, the share price could potentially move closer to those lower reference points.
See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Mixed signals on Acushnet Holdings so far. If you want to move fast and build your own view from the ground up, start by weighing the balance of 2 key rewards and 1 important warning sign
Looking for more investment ideas beyond Acushnet Holdings?
Round out your research by lining up a few fresh contenders. The right watchlist today can give you options when market sentiment shifts.
- Target higher potential upside with 10 elite penny stocks with strong financials that already back their story with real balance sheets and measurable fundamentals.
- Strengthen your core holdings through list of solid balance sheet and fundamentals (23 results) that pair durable finances with cleaner, less stressed capital structures.
- Get ahead of the crowd by reviewing 19 high quality undiscovered gems that combine quality metrics with relatively low market attention.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com