


Fresh attention on Origin Energy (ASX:ORG) has been triggered by analysis suggesting that rooftop solar and home battery uptake could pressure grid demand, margins, and the way the market values its retail and distributed energy exposure.
The current A$12.40 share price comes after a 30-day share price return of 13.97% and a 90-day gain of 14.50%. The 1-year total shareholder return of 9.28% and 5-year total shareholder return of 220.23% indicate that momentum has been strong over both short and long horizons as investors reassess how Origin Energy is priced against these rooftop solar and home battery shifts.
Compare Origin Energy's rooftop solar and battery theme with other grid exposed utilities by scanning our hand picked 41 power grid technology and infrastructure stocks now while this shift is front of mind.
After a strong run in Origin Energy over the past few months, the question now is whether the current A$12.40 price still leaves enough upside to compensate for rooftop solar and battery risks. The valuation work starts at this point.
Most Popular Narrative: 2% Overvalued
Against the A$12.40 share price, the most followed narrative puts Origin Energy's fair value at A$12.17 using a 7.18% discount rate, which implies the current quote already prices in a lot of rooftop solar and battery risk.
The capital intensive build out of 1.8 GW of grid scale batteries, progression of the 1.5 GW Yanco Delta wind farm and international expansion of Kraken and Octopus is already recognized in expectations for higher EBITDA. Execution on these projects and platforms still needs to support returns on capital and future earnings.
See why 54 investors see Origin Energy as 2% overvalued.
Result: Fair Value of A$12.17 (OVERVALUED)
Still, if Origin Energy turns Octopus, Kraken and the 1.6 GW virtual power plant into stronger recurring earnings, or if APLNG cash flow outperforms, that bearish fair value view could be challenged.
Find out about the key risks to this Origin Energy narrative.
Another View: Multiples Paint a Very Different Picture
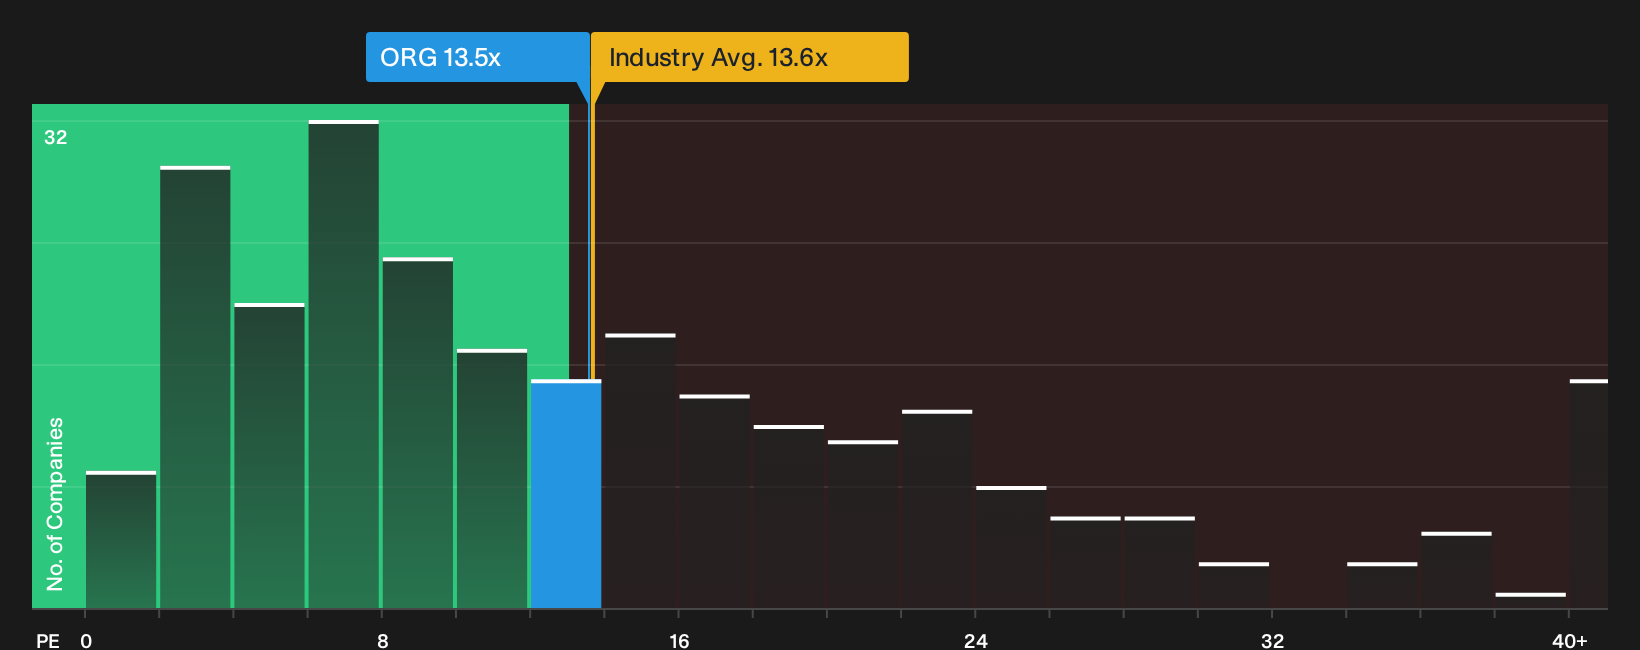
Analyst narratives suggest Origin Energy is roughly fairly priced around A$12.40, but the market ratios tell a different story. The stock trades on a P/E of 13.5x, compared with a fair ratio of 18.8x, the peer average of 32.8x and the global electric utilities mark of 13.6x.
That gap points to a market that prices Origin Energy more cautiously than both its fair ratio and many similar businesses, even after recent share price gains. The question for you is whether the rooftop solar and execution risks fully explain this discount, or if sentiment has moved too far.
See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Mixed views on Origin Energy's valuation and rooftop solar risk are clear. Move quickly, review the key numbers, and weigh both sides using 3 key rewards and 3 important warning signs
Looking for more investment ideas beyond Origin Energy?
If you stop with Origin Energy, you risk missing other opportunities that fit your style, your risk tolerance, and the kind of portfolio you actually want.
- Target stability and sleep-at-night holdings by scanning a 6 resilient stocks with low risk scores that focuses on resilience when conditions change.
- Hunt for potential mispricings by reviewing a 4 high quality undervalued stocks that blends solid balance sheets with healthy cash generation.
- Spot lesser known opportunities early by checking a 14 high quality undiscovered gems packed with companies that already show strong fundamentals.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com