


Tate & Lyle has delivered a strong share price run in recent months, which puts fresh attention on whether the current valuation still lines up with the earnings that support it. With the stock having moved sharply over the past year, the question now is how much of its earnings power is already reflected in today’s price.
- The share price is up 55.2% over the past year, which raises the stakes for anyone asking whether that performance is fully backed by the company’s profit profile.
- The group’s focus on ingredients and sweeteners means its earnings story is tied closely to pricing power, input costs and how efficiently it converts revenue into cash that can support the equity valuation.
- Your read on Tate & Lyle is one view; the desks covering it have another. See what analysts think Tate & Lyle's shares could be worth.
The stock’s next move may depend on whether Tate & Lyle’s current share price is appropriately aligned with what its earnings justify today.
To see how Tate & Lyle’s earnings question compares with others on your radar, scan a wider field of companies using the 15 high quality undervalued stocks.
Does Tate & Lyle Look Pricey on Earnings?
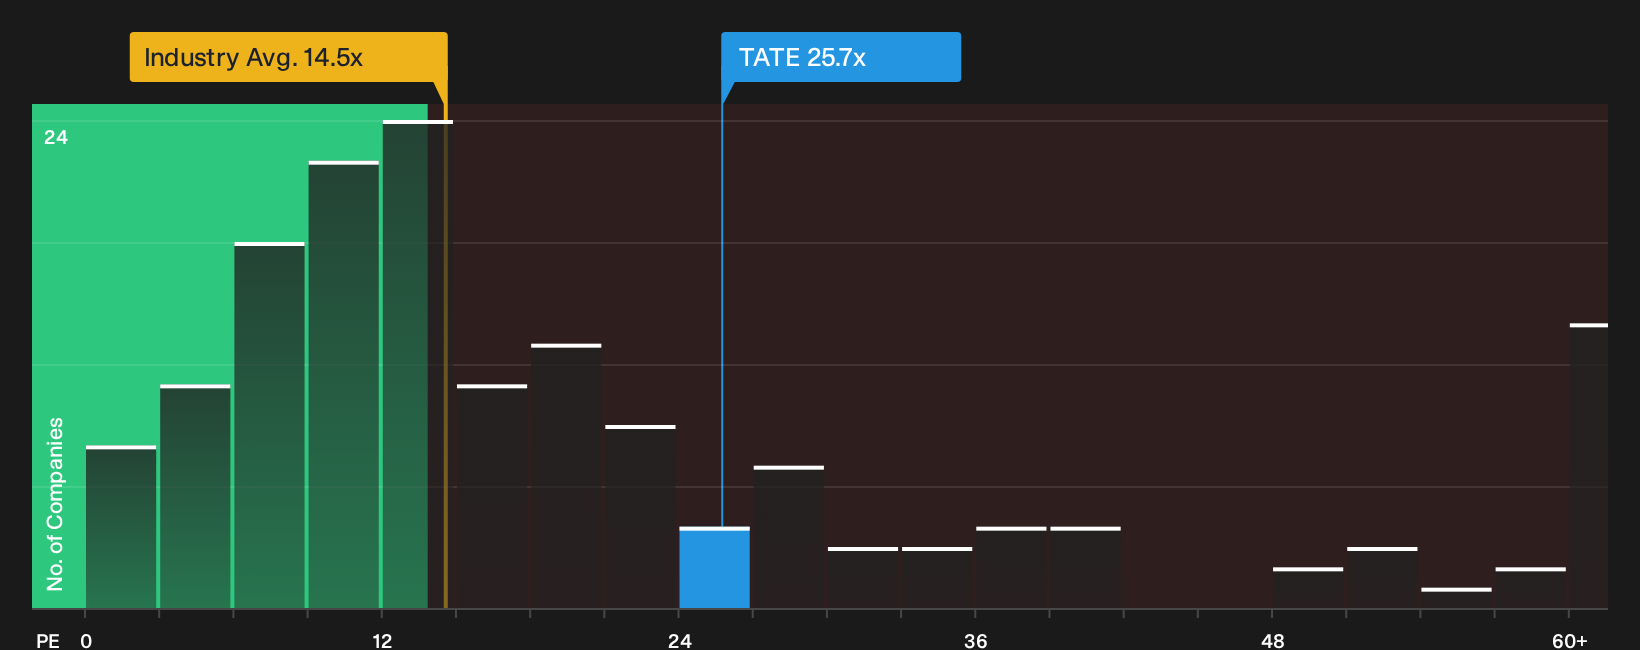
The P/E ratio suits Tate & Lyle because earnings sit at the centre of how investors think about an ingredients and sweeteners producer. The current P/E of 25.7x is well above both the food industry average of 14.5x and the wider peer group on 18.5x. This means buyers today are paying a richer price for each pound of profit than many comparable businesses.
Against a tailored fair multiple that weighs Tate & Lyle’s own growth profile, profitability and risk, the current P/E still screens on the expensive side rather than at a discount. That premium raises the question of whether the quality and resilience of future earnings are strong enough to justify paying more than both the industry and this internal yardstick suggest. Explore the numbers behind Tate & Lyle's P/E valuation.
The Tate & Lyle Narrative: What Would Justify Today's Price?
Simply Wall St Narratives pick up where Tate & Lyle's valuation puzzle leaves off. They spell out which assumptions on growth, margins and earnings would need to hold for the stock to be worth materially more or less than today’s price. Each one treats fair value as a thesis about the business that you can watch play out over time rather than a static snapshot, all housed on the Community page.
Community views on Tate & Lyle split between those who see extra upside from synergies and productivity and those who think the current tag already bakes most of that in.
Bull case: 8% undervalued
"The productivity programme has already produced $144 million of savings over 3 years and the 5 year target was raised from $150 million to $200 million…”
Discover why this Narrative puts Tate & Lyle at 8% undervalued.
Bear case: roughly fairly valued
"The earlier concern about revenue pressure from input cost deflation is now reinforced by the more recent 3% like for like decline in revenue and EBITDA…”
Explore why this Narrative puts Tate & Lyle at roughly fairly valued.
Before acting on Tate & Lyle's valuation, one more piece of the puzzle matters
The figures only tell part of the story, because the people steering Tate & Lyle and the way their rewards line up with your interests can tilt the whole investment case. See who runs Tate & Lyle and how they are paid.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com