


Enphase Energy has swung sharply in recent years, and with fresh earnings news still in investors’ minds, the key question is whether the current share price can be explained by the profits the business is generating today.
- Over the past 5 years, Enphase Energy has fallen 86.9%, which puts the focus squarely on whether its present earnings can still support the market value investors are paying now.
- Recent earnings came in below market expectations and management outlined softer demand in its core residential solar activity, which can influence how investors think about the durability and timing of future profit growth.
- Your read on Enphase Energy is one view; the desks covering it have another. See what analysts think Enphase Energy's shares could be worth.
For investors, the debate is whether Enphase Energy’s current market price is adequately backed by the cash earnings the business is producing today and is expected to produce over time.
Given how sharply Enphase Energy has swung around its earnings story, it can help to compare this setup with other companies screened for 53 AI infrastructure stocks
Does Enphase Energy Look Pricey on Earnings?
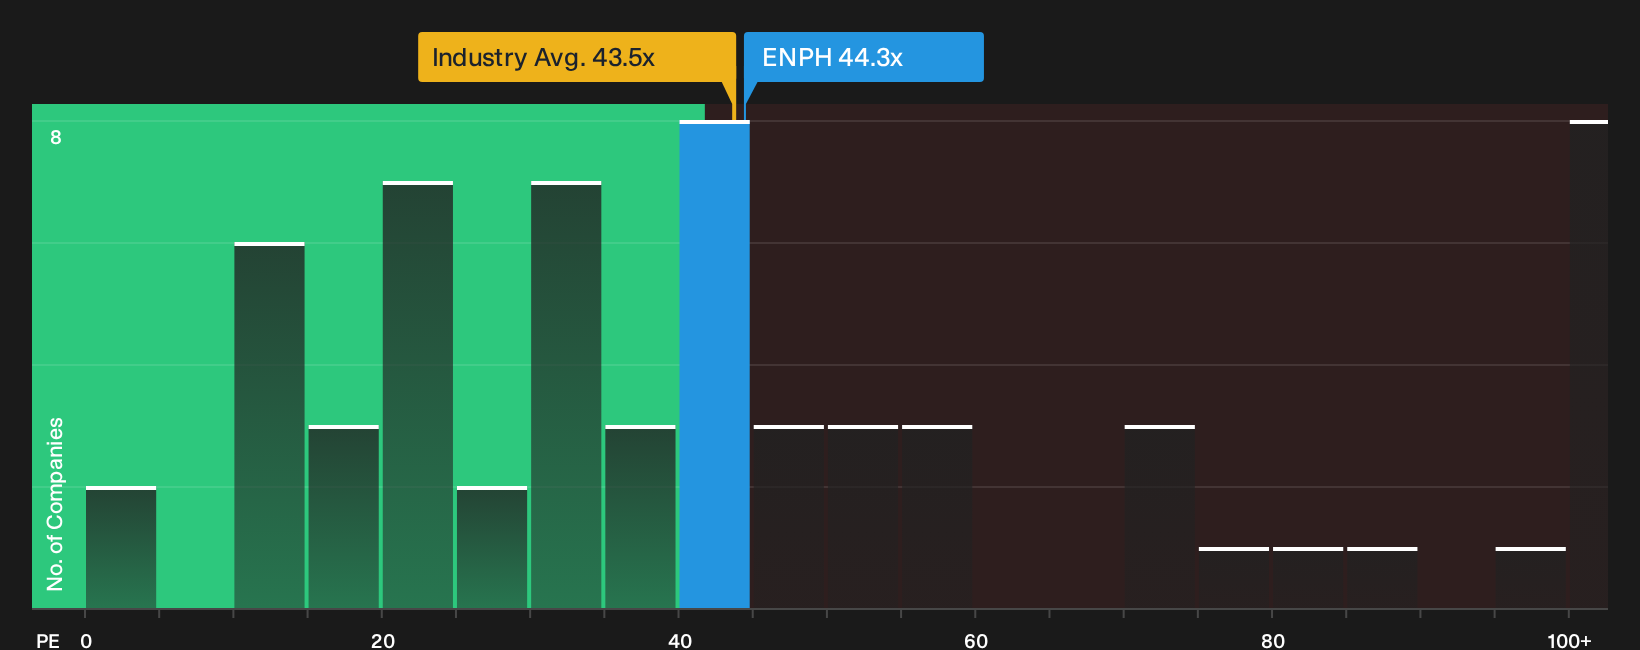
The P/E ratio suits Enphase Energy because earnings are still the main anchor investors use to think about its value. The stock currently trades on a P/E of 44.3x, which is very close to the wider semiconductor sector on 43.5x and below the peer group average of 67.0x. On this simple snapshot, the share price is not being pitched as the most expensive option in its peer set, but it is also not at a bargain level relative to the broader industry.
A tailored fair P/E that blends Enphase Energy’s margins, growth profile, size and risk suggests the current 44.3x level is on the expensive side. Because the latest results brought an earnings miss and a softer outlook for residential solar, the premium multiple asks you to pay up for delivery against those headwinds rather than getting paid for the recent uncertainty. For anyone tracking the valuation gap in more detail, the underlying modelled fair multiple and implied upside or downside are set out in the interactive view. Explore the numbers behind Enphase Energy's P/E valuation.
The Enphase Energy Narrative: What Would Justify Today's Price?
Narratives for Enphase Energy pick up where the P/E debate leaves off. They outline the earnings, margin and growth paths that would need to align for Enphase Energy's valuation to move meaningfully higher or lower than today's price. Where a single ratio or model gives you one outcome, these storylines unpack the future that outcome relies on so you can watch how reality compares over time. Narratives sit on Simply Wall St's Community page and provide context to the numbers without replacing your own judgment.
Community views on Enphase Energy pull in opposite directions, with one camp leaning into future product cycles and another focused on residential softness and policy risk.
Bull case: 38% undervalued
"Upcoming launches of next generation hardware including the IQ Battery G5 with roughly 50% higher energy density at about 40% lower cost per kWh…"
Discover why this Narrative puts Enphase Energy at 38% undervalued.
Bear case: 27% overvalued
"The narrative that Enphase Energy is overvalued rests on the view that the current share price already reflects strong margins, large safe harbor commitments, and future multi gigawatt opportunities in storage and AI data center power…"
Explore why this Narrative puts Enphase Energy at 27% overvalued.
One more angle on Enphase Energy that could change the picture
Analyst projections for Enphase Energy over the next few years give you a separate reference point to line up against today’s valuation and earnings story, and that comparison is waiting for you to explore. Explore where analysts expect Enphase Energy to be in a few years.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com