


UK energy policy is shifting fast as the government moves to outlaw new North Sea drilling, which puts future fossil fuel supply under a brighter spotlight and pushes investors to focus harder on cash reliability today. Companies that already generate solid cash and still trade below estimated fair value can look more interesting when long term uncertainty rises. This article highlights three undervalued British stocks where discounted cash flows do much of the heavy lifting.
The three stocks covered below are only a starter set, and the full screen on Simply Wall St surfaces 19 more companies with equally compelling cash flow stories that are not included here. To go straight to the source and identify, analyze, and prioritise your highest conviction ideas, head into the Undervalued Stocks Based On Cash Flows screener
Morgan Sindall Group (LSE:MGNS)
Morgan Sindall Group leans on a mix of construction, regeneration and fit out work, but the Partnership Housing arm is the clearest match with this cash-flow-focused screen, because long-term social and affordable housing programmes can anchor contract-backed income across cycles.
Morgan Sindall Group generates most of its revenue from Fit Out at about £1.9b, with Infrastructure at around £900 million and Partnership Housing contributing roughly £800 million, within a diversified UK-focused portfolio, and the business carries a market value of about £1.9b.
"Continued expansion of Morgan Sindall Group’s long-term regeneration and housing partnerships, including secured and preferred-bidder pipelines on multi-decade schemes and a housing pipeline of about 55,000 homes, can convert the existing visible workload into future revenue and earnings as schemes move from planning into build phases."
What happens to margins and cash conversion if a single pressure point in that capital-heavy housing roll out shifts the balance of risk and reward?
If that risk-reward balance is what you are weighing up, the full narrative for Morgan Sindall Group explains how Morgan Sindall Group’s contract mix and housing exposure could be reflected in its valuation.
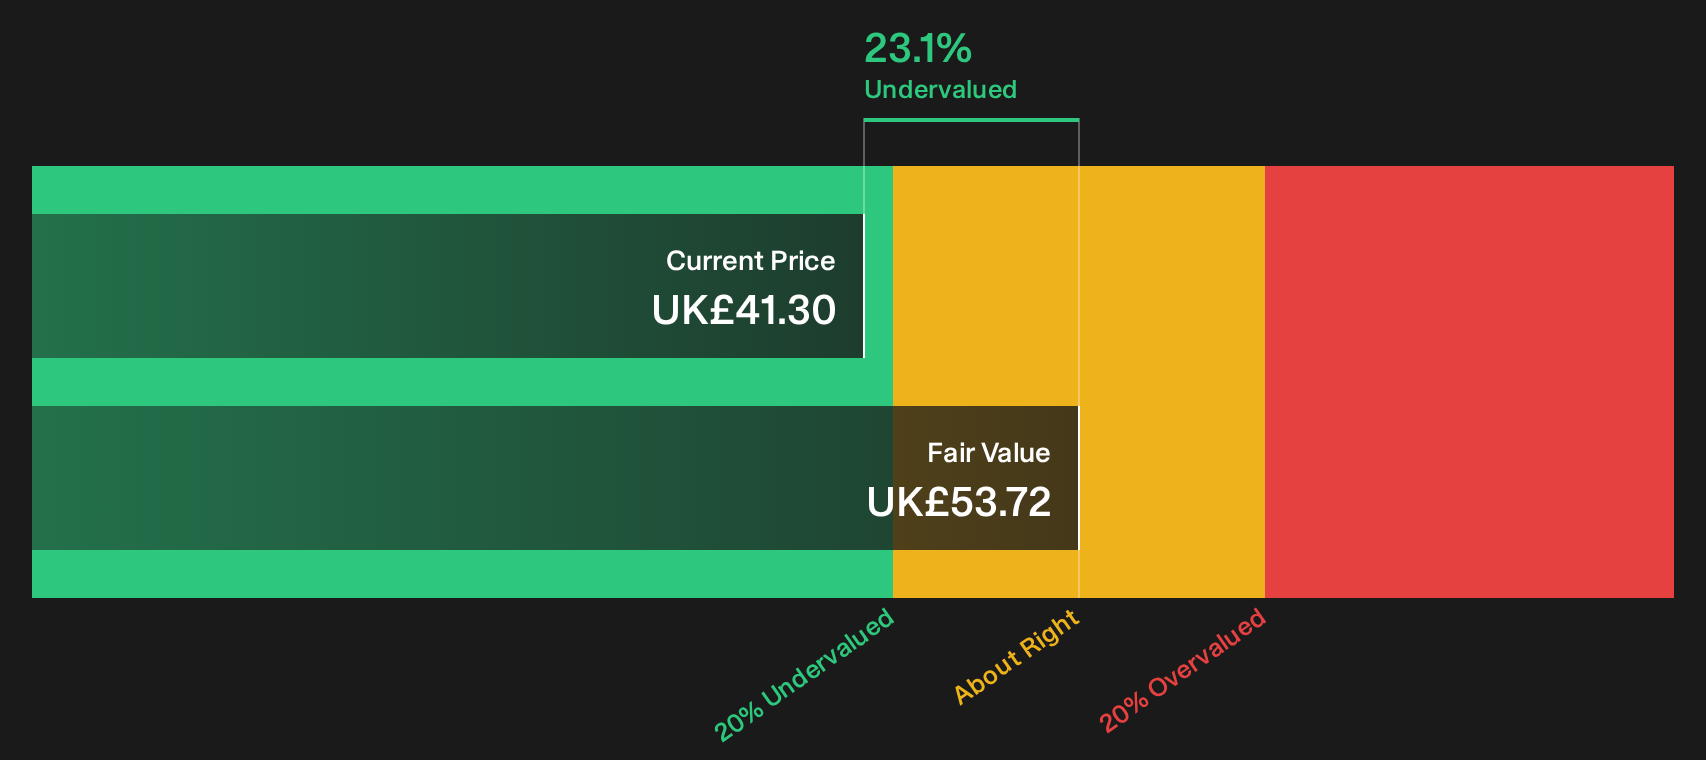
Premier Foods (LSE:PFD)
Premier Foods leans heavily on its branded ambient grocery lines like Mr Kipling, Ambrosia, Bisto and Sharwood’s, where repeat purchases through mainstream retailers help underpin the cash flow profile that puts it into this DCF driven undervaluation screen.
Premier Foods manufactures branded and own label foods, with about £860 million from Grocery and £315 million from Sweet Treats, anchored in the UK and smaller overseas sales, and carries a market value of roughly £1.8b.
For a value focused investor, Premier Foods offers something simple but powerful. Everyday cupboard staples that keep selling, a branded grocery engine that throws off cash across cycles, and an investment story where operational execution matters as much as headline growth.
"Planned step up in annual CapEx to a range of £55 to £60m in FY27, directed at automated cake lines, insourced sauce capacity, new process plants and energy projects such as efficient boilers and solar arrays, is intended to lower unit costs and improve factory recovery which can support gross margin and trading profit progression."
The bigger question for Premier Foods is what happens to that cash flow story if one key assumption about future branded momentum no longer holds.
If that branded momentum ever stalls, the full narrative for Premier Foods shows how cash generation, CapEx and pricing power could still reshape Premier Foods’ valuation story.
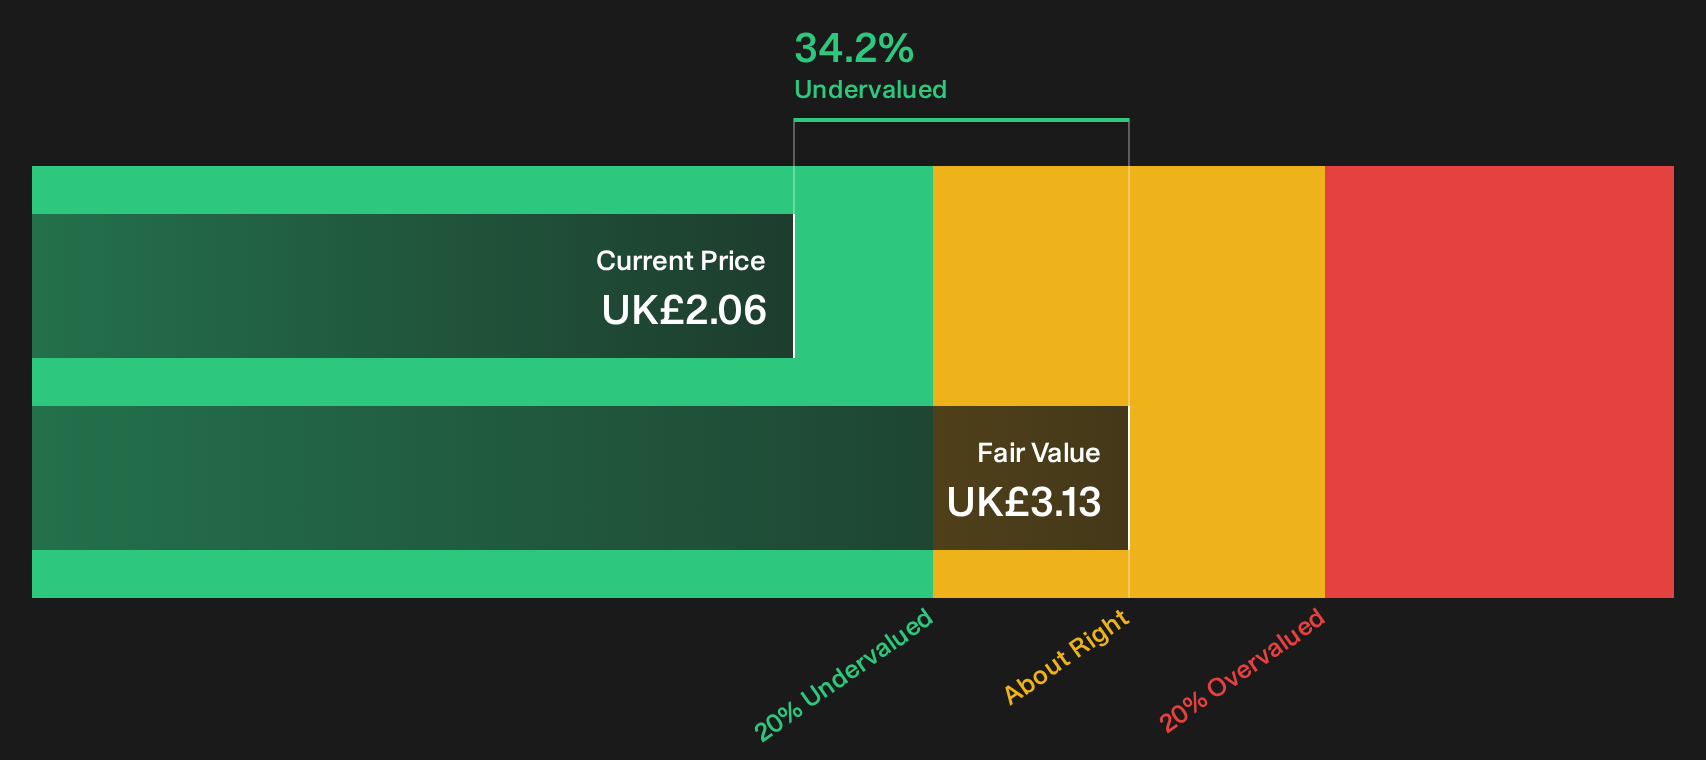
Autotrader Group (LSE:AUTO)
Autotrader Group fits this cash flow focused screen because its online marketplace model leans on recurring fees instead of one off deals. This gives value oriented investors a clearer line of sight on the cash that underpins any DCF based estimate.
Autotrader Group runs an automotive marketplace in the UK where subscriptions and listing fees on the Autotrader platform generate about £585 million of £624 million revenue, with Autorama contributing £39 million, and the business carries a market value of around £4.3b.
"Auto Trader Group's continued rollout of Deal Builder, with inquiries and Buying Signals leads converting at least twice as well as average inquiries and around half of deals occurring outside traditional hours, points to further monetisation of higher quality leads that can support retailer revenue and Auto Trader's own ARPR and earnings over time."
The real test for Autotrader Group is what happens to that cash rich model if a single assumption about retailer appetite quietly shifts.
If that assumption starts to shift, the full narrative for Autotrader Group explains where Autotrader Group’s cash engine could continue accelerating and where retailer demand risks might quietly be masking opportunity.
Seeking Fresh Alternatives Before They Fly?
Fresh ideas often move first. Breakout stories can gain momentum while they are still under the radar, and slow research can get caught flat footed. Scan the next wave and consider getting in early.
- Spot steady payers that might keep cash flowing even when sentiment drops by scanning the 4 dividend fortresses while yields still look appealing.
- Track early movers in artificial intelligence infrastructure and monitor that building momentum before pricing moves further by filtering through the 53 AI infrastructure stocks.
- Zero in on resilient balance sheets that can sometimes hold up when volatility spikes using the curated list of solid balance sheet and fundamentals (10 results).
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com