


John Salama, CMT
ETF Market Strategist & Derivatives Trader | CMT | Author, Physical Over Digital Alpha | Featured Author, Barchart | 500+ Institutional Subscribers
November 4, 2026
Yesterday I had the privilege of attending the ETF Investor Forum at Terminal Warehouse as a guest of Anthony Pompliano.
I walked away with one clear takeaway: the education gap between what these products can do and what retail investors actually understand is the single biggest distribution challenge in the ETF industry right now.
Heard it directly from Jan van Eck, Ryan O’Connor at Global X, Drew Pettit at Roundhill, Bilal Little at Direxion, and Wes Mathews, CFA at NEOS. Every single one of them said it in different words.
That gap is exactly what Physical Over Digital Alpha exists to close.
Grateful for the access. Now back to work.
Wednesday’s session delivers a decisive, risk-on relief trade: equity derivatives and cash flow aggressively re-allocated into domestic value, financials, and consumer cyclicals as midterm election certainty resolved overnight. Crude energy and volatility collapsed in an absolute multi-sigma unwind. The market didn’t wait for commentary. It priced the outcome before the opening bell finished.
Democrats flipping both chambers removes the dominant tail risk that had been bid into volatility, energy, and defensive positioning for weeks. The Iran war premium, the geopolitical floor under crude that had sustained USO’s elevated print and kept energy equities at all-time highs, liquidated immediately and completely. Capital rotated hard into domestic stability themes: financials, healthcare, housing, airlines, retail.
The five-day window tells the full story: ITB +13%, JETS +9%, XRT +8% to 52-week highs on the upside; SOXX -13%, USO -12%, ARKG -11% on the downside. Domestic cyclicals and rate-sensitive quality breaking out simultaneously while semiconductors and energy absorb historic distribution. The rotation is not subtle.
SIGMA MOVERS
Multi-standard deviation displacements driving today’s price action:
Upside:
(IHI) +6.7% Medical Devices delivering a single-session sigma move of this magnitude on a midterm relief day is a direct statement from institutional capital. Healthcare is not just a defensive trade in this environment; it is a growth-with-quality allocation that benefits from political stability, regulatory clarity, and a domestic earnings outlook that doesn’t depend on geopolitical risk premiums. IHI printing +6.7% in a session where XLV simultaneously hits an all-time high confirms this is sustained conviction, not a one-day rotation bid.
(XLY) +4.5% Consumer Discretionary absorbing a single-session sigma move alongside IHI confirms the relief trade is broad. Capital is re-rating domestic consumer exposure with clarity on the policy environment. This is not a tactical bounce; this is institutional re-allocation into the beneficiaries of a stable domestic outlook.
(DIA) +2.9% The Dow Industrials (the most rate-sensitive, domestically-oriented large-cap index) gaining 2.9% in a session where financials, healthcare, and staples all hit all-time highs simultaneously confirms the structural story. Industrials benefit from lower energy input costs, clearer fiscal visibility, and the same domestic stability narrative driving the full rotation.
Downside:
(VXX) -9% The short-term VIX ETN collapsing 9% in a single session is the most important derivatives signal on today’s tape. When the dominant source of tail risk (election uncertainty compounded by geopolitical escalation) resolves in a single night, the demand for protective options craters. Implied volatility gets crushed. This is not a short-vol squeeze unwind; this is certainty pricing out fear premium in real time.
(USO) -9% Crude oil absorbing a 9-handle single-session collapse alongside a -12% five-day print confirms the Iran war risk premium is under significant pressure. Still seems to be a mean reversion within a bull trend. The geopolitical bid that sustained crude above its structural range is weakening.
(XLE) -6% Energy equities following crude lower with a -6% single-session print confirms the liquidation is across the complex, not isolated to futures. Energy had been one of the clearest regime beneficiaries of the geopolitical risk premium. That regime possibly just changed overnight.
Fresh All-Time Highs
(XLF) Financials printing a record on midterm certainty is the textbook regime shift signal. Rate-sensitive, high-quality balance sheets re-rating on political clarity and a reduced tail risk environment.
(XLP) Consumer Staples hitting an all-time high on a session where cyclicals are also ripping confirms this is a broad quality bid, not a defensive flight. Institutional capital is not hiding, it is repositioning into confirmed domestic strength.
(XLV) Healthcare delivering its all-time high alongside financials and staples on the same session. The Physical Over Digital Alpha defensive and life sciences thesis continues to compound.
(VTV) Vanguard Value printing a record alongside three sector ETFs on the same day is the structural confirmation. This is a factor rotation, not a sector call. Quality and value are being re-rated at the index level.
New 52-Week High: (XRT) (SPDR S&P Retail ETF)
VOL SURFACE WATCH: (SPY) | November 20 Expiry (16 DTE)
Metric Reading
IV ATM 13.9%
Historic Volatility 11.4%
IV Rank 19.9%
The vol surface is telling a nuanced story that the equity tape alone doesn’t capture.
ATM implied volatility at 13.9% is running above realized vol at 11.4%; the market is still paying a premium for protection. But IV Rank at 19.9% means implied volatility is in the bottom fifth of its recent range. The market is pricing calm. It is not screaming buy vol, but it is not the environment where you want to be aggressively short premium without understanding what you’re giving up.
For the derivatives audience: IV above HV with IV Rank sub-20 is a specific setup. The slight premium tells you event risk is not fully priced out; the market respects that certainty doesn’t mean smooth sailing. But the absolute level of vol is low enough that income-oriented structures like covered calls, defined-risk spreads, bull call spread diagonals across XLF and XLV, are collecting real but modest premium in a confirmed breakout regime.
Don’t reach for yield by selling naked premium here. Collect modest premium through structured overwrites on positions you want to hold. The edge in a low-IV breakout environment shifts toward defined-risk long structures, not aggressive premium selling.
Watch how the vol surface evolves through next week. If IV compresses toward HV without a catalyst, that’s the signal the relief trade has fully run... and the next vol expansion setup becomes the more interesting trade.
5-DAY LEADERBOARD
Top 3 Gainers (Rolling 5 Days):
ITB +13% Home Construction delivering the strongest five-day print on the leaderboard is the cleanest domestic stability trade on the tape. Lower energy input costs, a clearer rate path, and improved consumer confidence in a resolved political environment are all direct ITB tailwinds. The five-day sigma move confirms institutional accumulation, not momentum chasing.
JETS +9% Airlines absorbing a +9% five-day move as crude collapses is the most direct expression of the energy unwind beneficiary trade. Fuel is the dominant variable cost for airlines. USO down 12% over five days is a direct margin expansion event for the complex. JETS at +9% five-day is the market pricing that in real time.
XRT +8% — New 52-Week High Retail breaking to a 52-week high on the five-day window confirms the domestic consumer thesis. Political certainty, lower energy prices, and a stable rate outlook are the three inputs retail needs. The market is delivering all three simultaneously.
Top 3 Losers (Rolling 5 Days):
(SOXX) -13% Semiconductors absorbing a -13% five-day decline with multiple vectors of pressure converging simultaneously. AI memory and infrastructure spend recalibration, South Korea macro uncertainty feeding through to display and memory chip pricing, and the ongoing repricing of what the AI trade means for chip demand at the component level versus the infrastructure layer. The election adds a tariff policy wildcard; a Democratic sweep likely reads as less aggressive on China trade restrictions, a nuanced read depending on where in the semis value chain you sit. This is potentially not digestion within a bull trend. Watch whether SOXX finds support at prior breakout levels or confirms a deeper structural shift.
USO -12% Covered above. The Iran war premium is slipping out.
(ARKG) -11% Genomics absorbing distribution after its recent run is the cleaner story; high-beta growth unwinding as the relief trade concentrates into quality and value rather than speculative biotech. The five-day -11% print against IBB and XLV both near all-time highs confirms the rotation is discriminating: institutional healthcare and life sciences accumulation continues; speculative genomics exposure is being reduced.
Top 3 Active Tactical Trades (Past 5 Days)
SHORT SOXX (-13.6% five-day return) The semiconductor complex under multi-vector institutional pressure. Maintain.
LONG ITB (+13.2% five-day return) Domestic stability and energy cost tailwinds compounding into the housing complex. Maintain.
SHORT USO (-11.9% five-day return) Iran war risk premium liquidation confirming the structural energy thesis. Maintain.
THE CERTAINTY REGIME
Four simultaneous all-time highs (XLF, XLP, XLV, VTV) on a single session demands a direct statement: this is a regime shift, not a relief pop.
When four uncorrelated sectors break out together on the same catalyst, you are watching institutional allocation, not day-trader momentum. That takes weeks to fully express. The vol surface confirms it; IV Rank at 19.9% with ATM IV just above realized means the options market is not pricing the next leg down. It is pricing continued, moderate upside with low disruption risk.
The energy unwind may have further room. If the geopolitical de-escalation narrative continues to price in, crude faces additional compression and energy equities remain structurally challenged against a domestic cyclicals backdrop.
The market told you what it wanted today. Four all-time highs at once is not ambiguous.
TOP 3 CHARTS (1-Year, Barchart RSI 14)
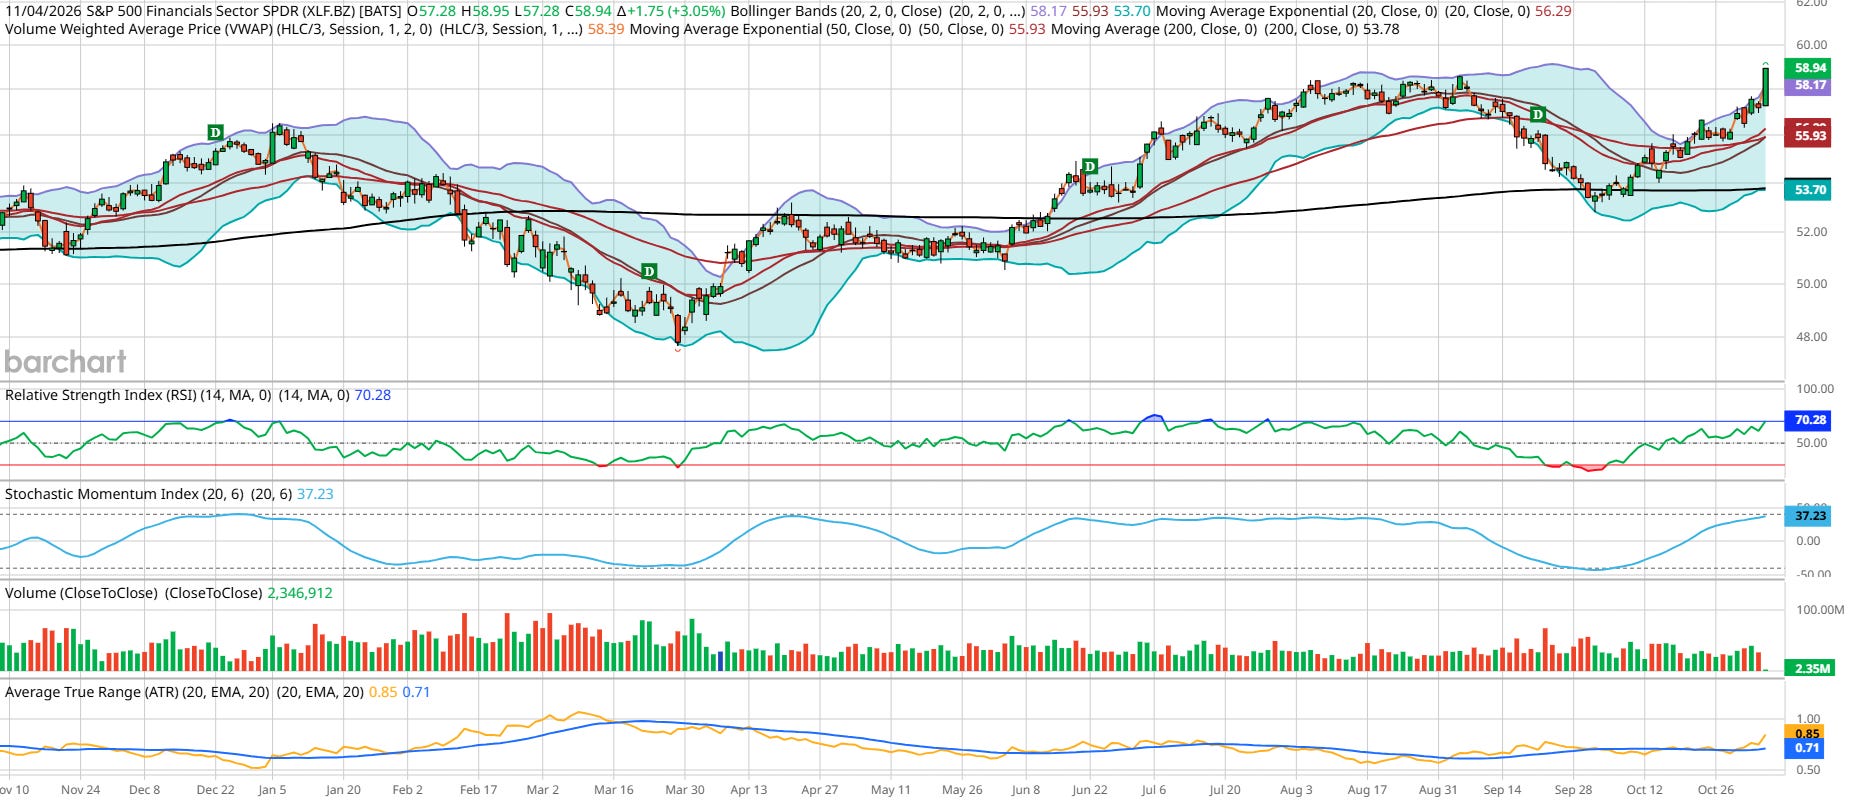
[Chart 1: XLF — quadruple ATH breakout session in context of the one-year trend]
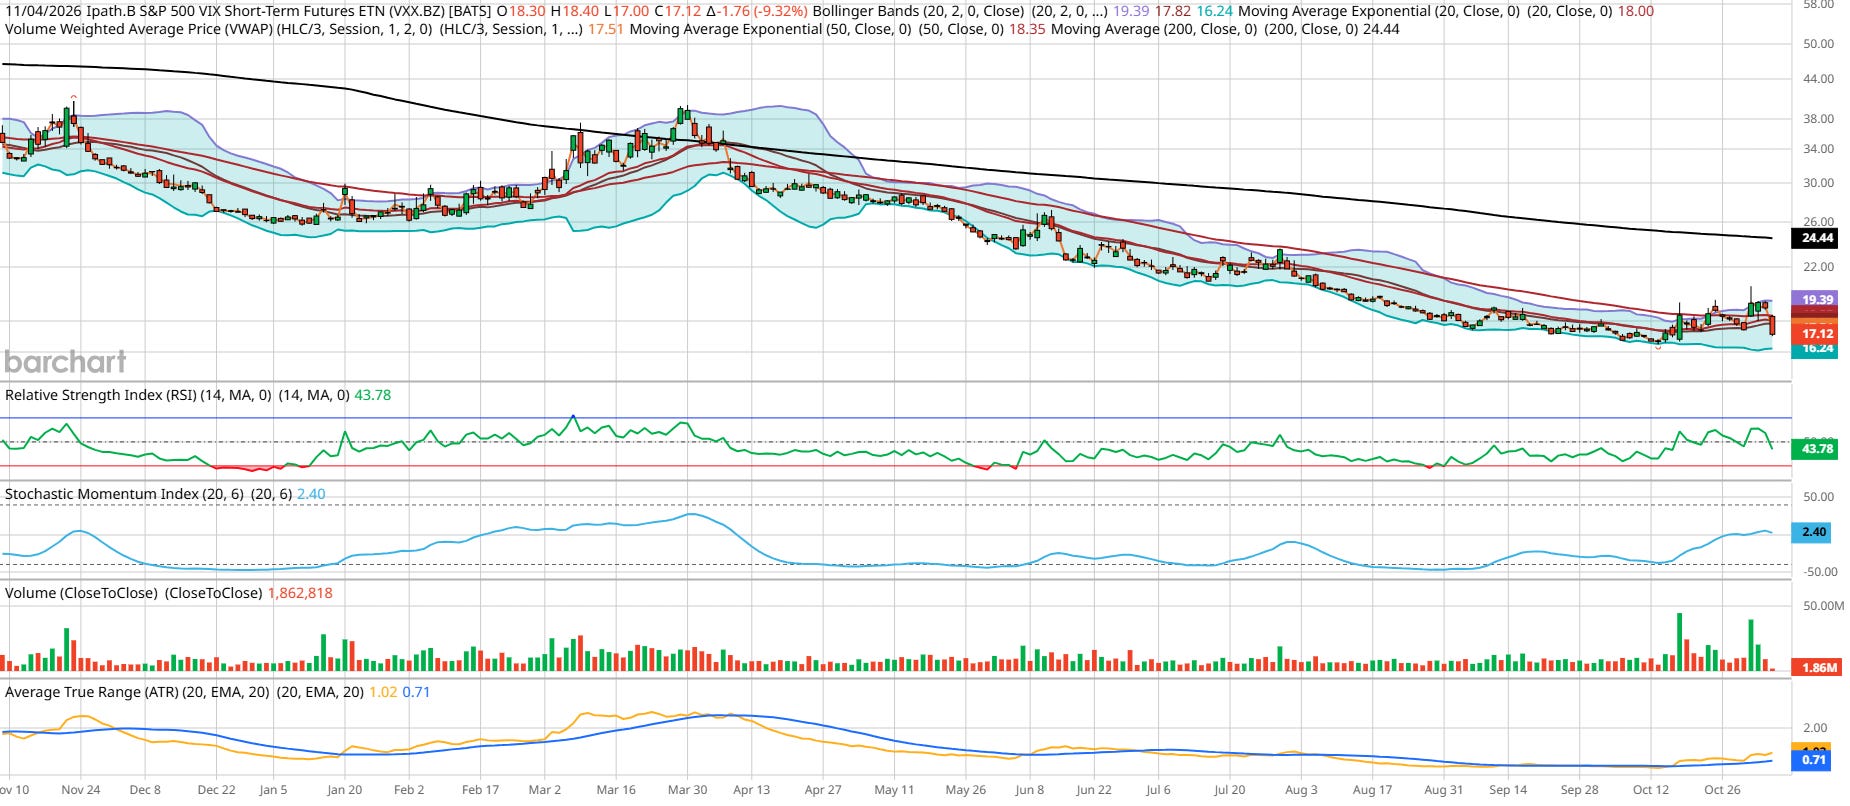
[Chart 2: VXX — single-session vol collapse and the certainty regime shift]
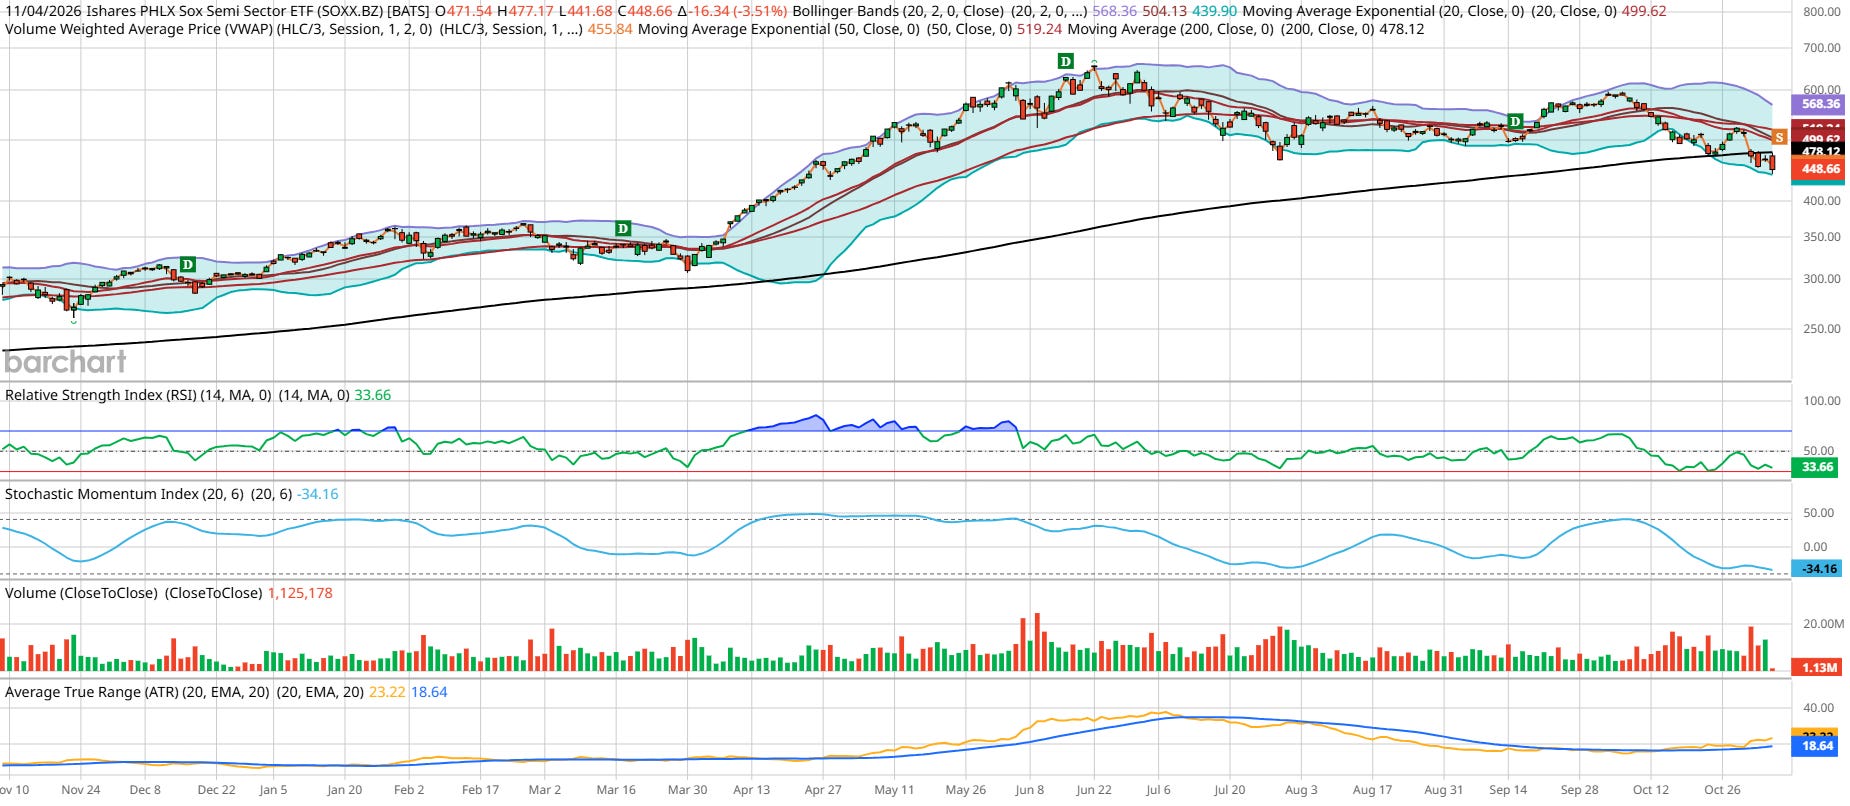
[Chart 3: SOXX — five-day -13.6% distribution within the 52-week structure]
Physical Over Digital Alpha publishes Tuesday and Thursday. Institutional ETF and market strategy for practitioners who trade what they write. Now a Featured Author at Barchart.com.
Use the same charts behind every Physical Over Digital Alpha breakdown — try Barchart Premier free: barchart.com/get-barchart-premier?fpr=h1fuww
— John Salama, CMT | Proprietary Equity Derivatives Trader, Maverick Trading