


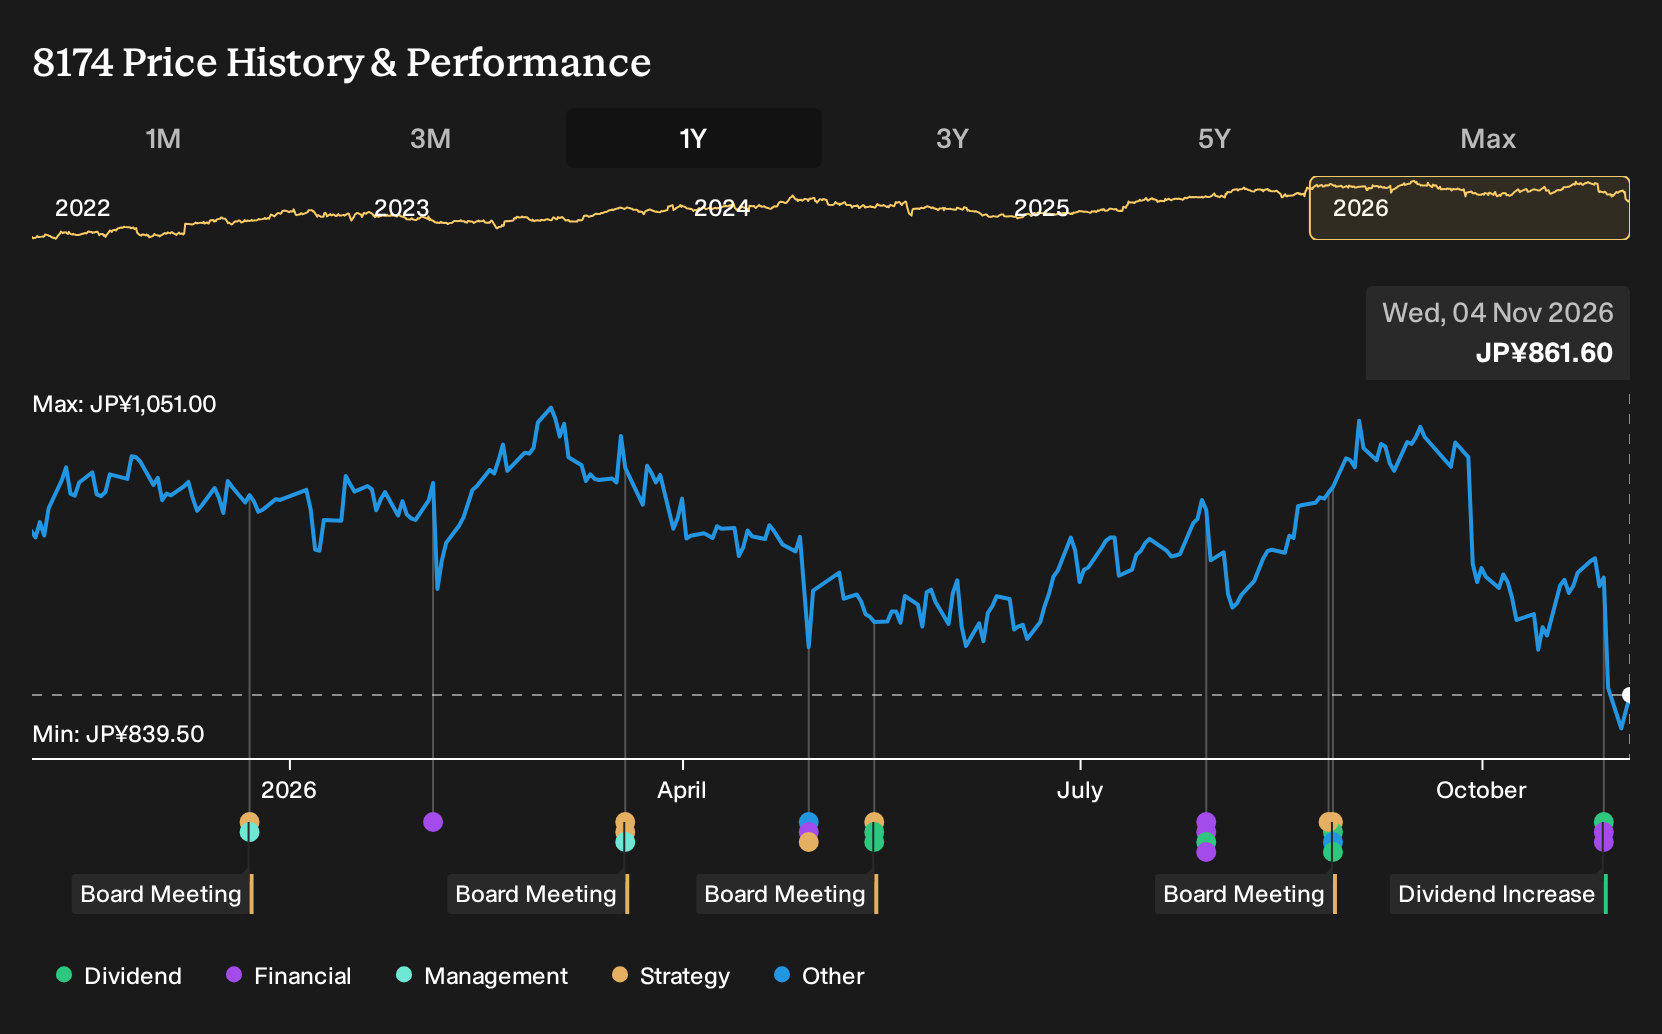
- Nippon Gas Co., Ltd. reported half year sales of JPY 97,585 million and net income of JPY 2,903 million, raised its second quarter dividend to JPY 55.00 per share from JPY 51.50 a year earlier, and issued full year guidance including expected operating income of JPY 20,000 million and EPS of JPY 44.09 for the fiscal year ending March 31, 2027.
- The combination of a higher interim dividend, a solid sales figure and forward guidance suggests Nippon Gas is prioritising investor visibility on cash returns and earnings power, even as profit for the half year came in lower than the JPY 3,439 million reported a year earlier.
- Attention now turns to how Nippon Gas's investment narrative could shift as the higher JPY 55 dividend intersects with detailed earnings guidance.
Scan how Nippon Gas's higher interim payout compares by lining it up against carefully filtered income ideas in our 32 dividend fortresses
What Is Nippon Gas' Investment Narrative?
Nippon Gas asks you to buy into a fairly simple story. This is a regulated utility style business built on LP gas, city gas and electricity sales in Japan, with meaningful capital needs and a customer base that tends to move slowly rather than in sudden bursts. The raised JPY 55 interim dividend and full year guidance for JPY 20,000 million in operating income and JPY 44.09 in EPS indicate that management wants to signal confidence in cash generation, even after half year profit and EPS came in below the prior period.
The key near term swing factors remain grounded in execution rather than sentiment. Investors are watching how Nippon Gas manages pricing against input costs, how capital spending for networks and equipment feeds into the high debt load, and whether earnings guidance proves realistic if demand or costs shift. The stock has fallen over the past month and year, while analysts still see upside to their targets. However, the more immediate question is how comfortably that higher dividend sits on top of an already leveraged balance sheet and an unstable payout history.
That said, before treating the richer dividend and guidance as a simple green light, there is one structural pressure point that continues to nag at the story.
There's only one way to know the right time to buy, sell or hold Nippon Gas. Head to Simply Wall St's company report for the latest analysis of Nippon Gas's Fair Value.
Decide For Yourself
Disagree with this assessment? Extraordinary investment returns rarely come from following the herd, so consider your own analysis and judgment.
- A useful starting point for your Nippon Gas research is our analysis highlighting 4 key rewards and 2 important warning signs that could impact your investment decision.
- See our latest analysis for Nippon Gas. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, which makes it easier to evaluate Nippon Gas' overall financial health at a glance.
Looking For More Investment Ideas Beyond Nippon Gas?
If you want to stress test what you see at Nippon Gas against other opportunities, it helps to scan a few focused shortlists rather than a sprawling universe of tickers.
- If you care most about income resilience, compare Nippon Gas with companies that feature in our 32 dividend fortresses and see how their payouts stack up on yield and stability.
- If quality at a sensible price is your priority, line up Nippon Gas beside candidates from our 19 high quality undervalued stocks to see which businesses pair fundamental strength with more modest expectations.
- If you want balance sheet strength front and center, contrast Nippon Gas with companies in our list of solid balance sheet and fundamentals (22 results) so you can judge cash flows alongside leverage and liquidity in one sweep.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com