


Upstart Holdings has seen its share price fall sharply in recent years, and that slide puts fresh focus on whether the current valuation still lines up with the earnings story. With the stock now trading near US$21, the real question is how much of its business performance is already reflected in that price.
- Over the past 5 years, the share price has declined about 93%, which puts a lot of weight on whether the remaining market value is adequately supported by the company’s earnings profile.
- Recent record contribution profit and progress in secured lending, along with plans to build its own bank, can influence how investors think about the durability and timing of future profitability.
- The analysts covering Upstart Holdings have run their own numbers. See what analysts think Upstart Holdings's shares could be worth.
The issue now is whether Upstart Holdings' current market value is justified by its earnings when measured against the Fair Ratio benchmark.
To cross-check what you see in Upstart Holdings against a wider set of AI-focused lenders and platforms, start with a focused screen of 41 profitable AI stocks that aren't just burning cash.
Does Upstart Holdings Look Fairly Valued on Earnings?
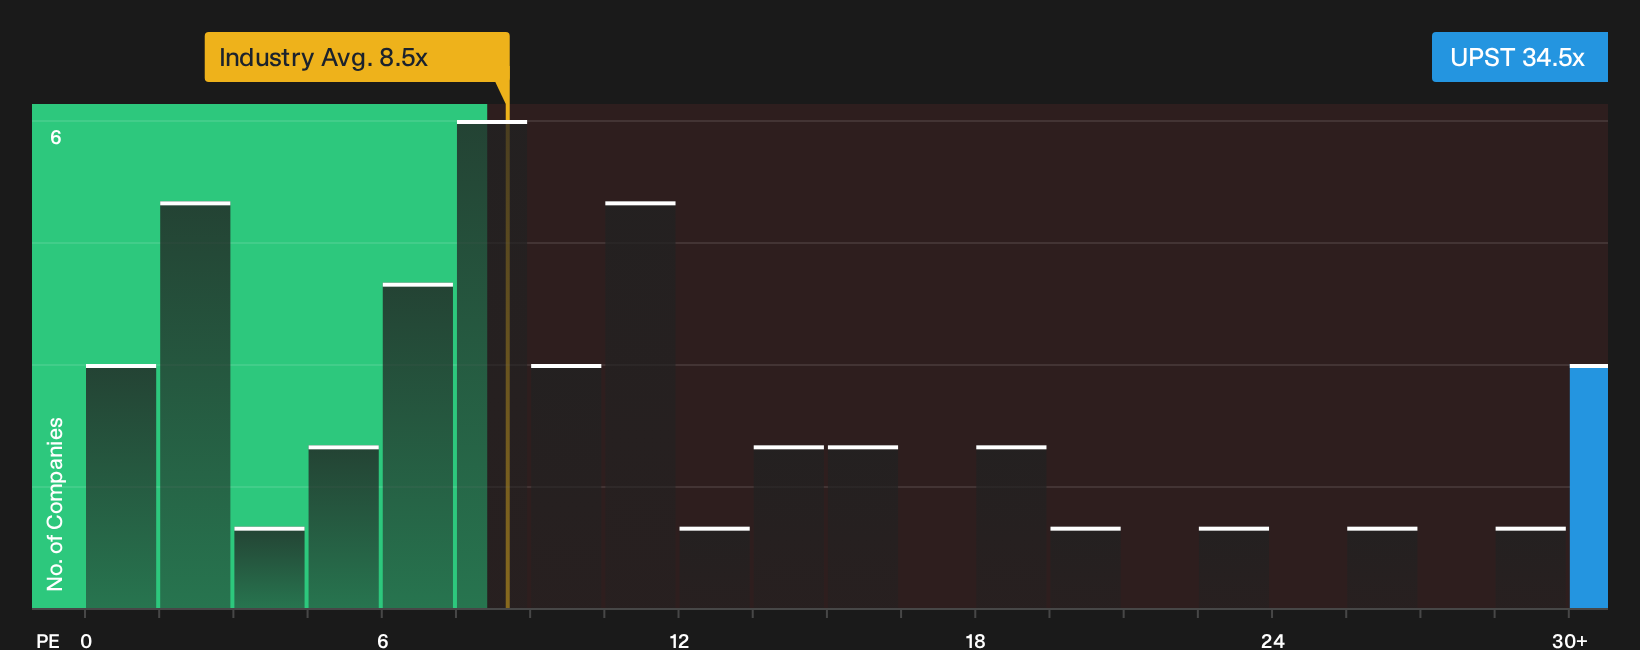
P/E is a useful yardstick for Upstart Holdings because earnings are the main driver of value in a lending platform once growth investment starts to convert into profit. The stock trades on roughly 34.5x earnings, compared with about 8.5x for the wider Consumer Finance industry and 11.5x for similar peers, so the valuation asks you to pay a clear premium for its AI focused model and earnings potential.
On the Fair Ratio framework, which blends expectations for growth, profitability, size and risk into a tailored benchmark, that 34.5x sits slightly above the level implied by Upstart Holdings' fundamentals and risk profile. Because the Q3 2026 report brought record contribution profit and progress in secured lending a quarter ahead of schedule, investors are currently accepting that higher multiple rather than pushing the shares closer to the modelled benchmark. Explore the numbers behind Upstart Holdings's P/E valuation.
The Upstart Holdings Narrative: What Would Justify Today's Price?
Narratives for Upstart Holdings pick up where the valuation puzzle leaves off by spelling out which paths for growth, margins and earnings would need to hold for the stock to be worth materially more or less than today’s price on Simply Wall St’s Community page. Rather than stopping at a single multiple or headline model result, each scenario lays out the key assumptions behind its view of fair value so you can track those against future numbers as they come through.
Community views on Upstart Holdings break into two clear camps, with one side seeing substantial upside and the other arguing the stock already prices in a lot of good news.
Bull case: 44% undervalued
"Expanding committed capital relationships, including up to US$10.8b of new capacity year to date, renewed institutional partnerships, recent securitizations and new credit union agreements, points to a deeper funding base that can support higher originations with limited balance sheet usage and potentially stronger contribution margins and earnings…"
Discover why this Narrative puts Upstart Holdings at 44% undervalued.
Bear case: 19% overvalued
"The move toward committed capital and co-invest structures, including about US$1.3b of cumulative co-invested capital and multi-year forward-flow deals, increases balance sheet exposure…"
Explore why this Narrative puts Upstart Holdings at 19% overvalued.
One more angle on Upstart Holdings that could change the picture
Everything here has focused on what Upstart Holdings looks like today. Yet there is a separate set of expectations from professional analysts that sketches where this business might be a few years from now. Explore where analysts expect Upstart Holdings to be in a few years.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com