


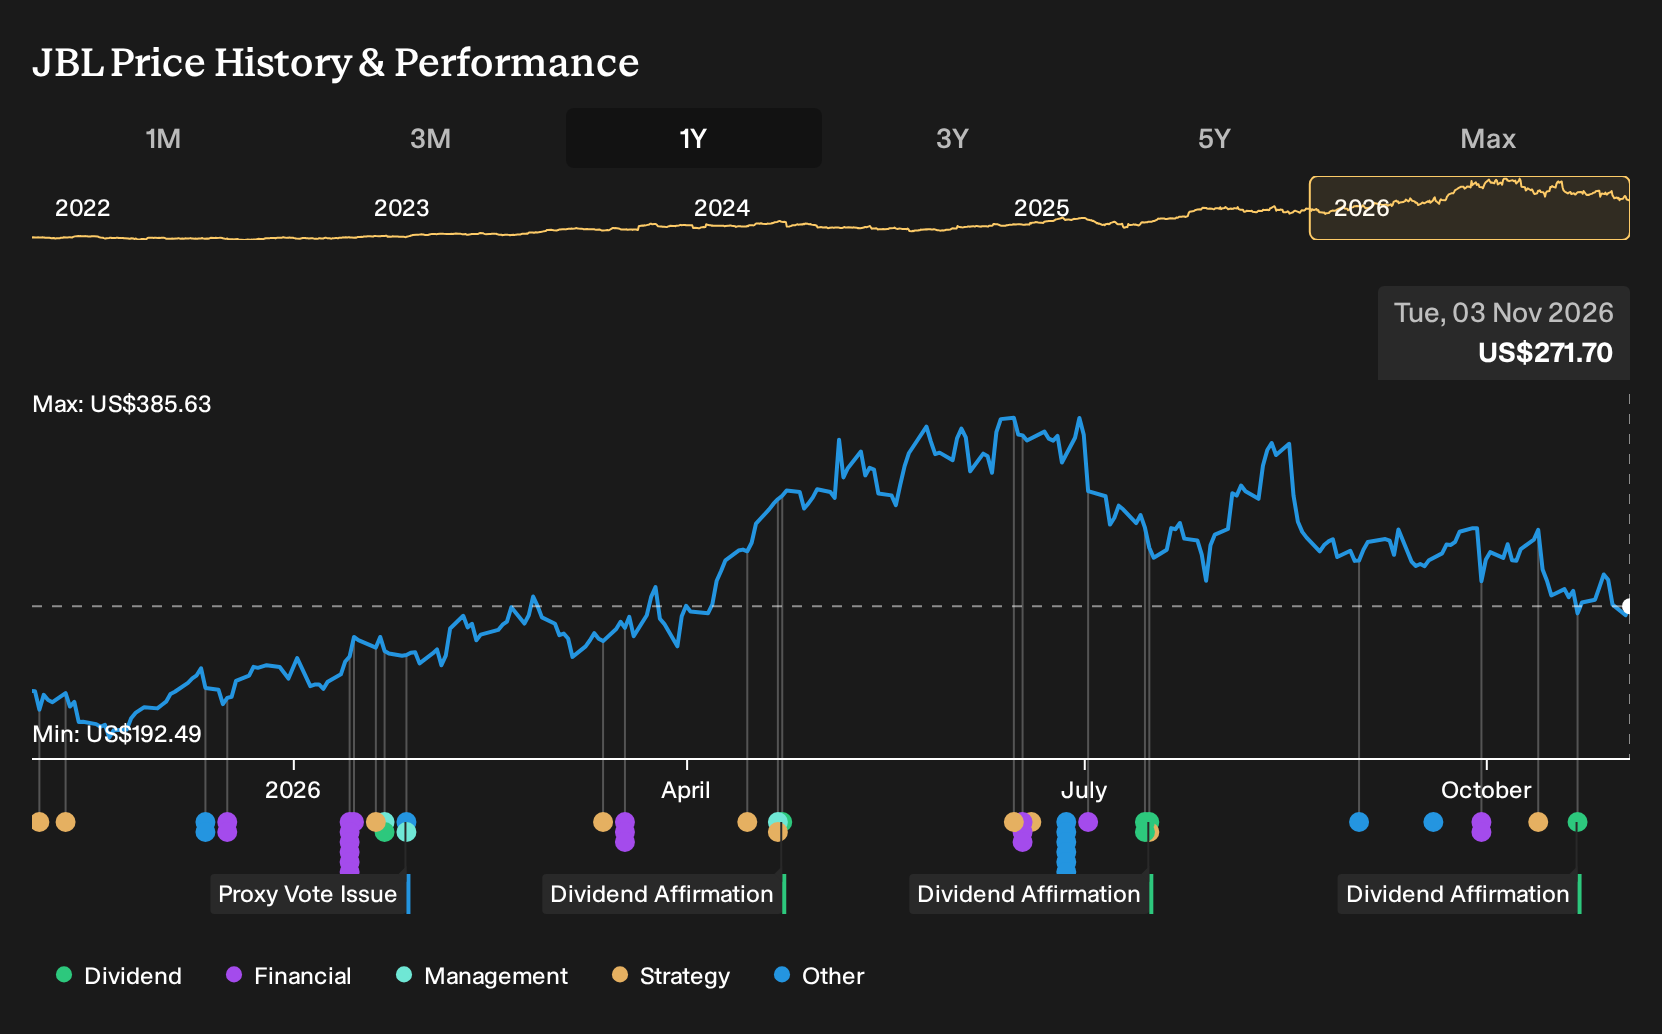
- Jabil declared a quarterly dividend of $0.08 per share, payable on December 2, 2026, to shareholders of record on November 16, 2026, reinforcing its current capital return approach.
- The affirmation of cash returns comes alongside management’s focus on AI infrastructure and Intelligent Infrastructure. Expanding hyperscale relationships and diversified end markets such as healthcare, automotive, and energy frame Jabil’s operating priorities.
- This article reviews how Jabil’s investment narrative is affected by its AI driven Intelligent Infrastructure outlook alongside the affirmed dividend.
Scan AI-focused infrastructure peers riding similar themes to Jabil with our curated 53 AI infrastructure stocks as a starting universe for your watchlist.
Jabil Investment Narrative Recap
To own Jabil, you need to be on board with a business built around AI driven Intelligent Infrastructure, regulated industries work and an asset light model that leans on strong free cash flow. The fresh US$0.08 dividend affirmation reinforces that management is not shifting priorities and does not materially change the near term story.
The real swing factor remains execution on large AI infrastructure programs and Intelligent Infrastructure revenue targets, while managing supply constraints and elevated inventories. The biggest current risk is that component tightness or slower inventory normalization ties up cash and restricts flexibility for buybacks and further investment.
The dividend announcement is the most relevant recent move for Jabil in this context. A maintained US$0.08 quarterly payout, with a clear schedule into December 2026, indicates that management is continuing cash returns while pursuing AI related projects and Intelligent Infrastructure build outs.
For you as a holder or watcher, the key question is whether that steady dividend sits comfortably alongside Jabil’s capital needs, including AI infrastructure, India expansion and healthcare and pharma solutions. Any sustained pressure from inventory levels or supply tightness could affect how easily the firm can support both investment and shareholder returns.
Jabil's narrative projects US$57.4b revenue and US$2.3b earnings by 2029. This aligns with analyst assumptions for 16.9% yearly revenue growth and implies earnings would need to more than double from about US$1.0b today to reach that US$2.3b level.
Uncover why Jabil's fair value indicates a 56% potential upside to its current price, which investors may see realized sooner than expected.
Exploring Other Perspectives
Some of the lowest Jabil forecasts lean on a very different catalyst. These analysts worry that AI data center projects could cool, with revenue in their models reaching about US$53.9b and earnings around US$2.1b by 2029. Those views were set before this dividend affirmation, so the story may yet shift.
Explore 2 other Jabil fair value estimates, including one that suggests it could be worth just $425.00!
Decide For Yourself
Don't just follow the ticker. Dig into the data and build a conviction that's truly your own.
- A great starting point for your Jabil research is our analysis highlighting 4 key rewards and 1 important warning sign that could impact your investment decision.
- See our latest analysis for Jabil. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Jabil's overall financial health at a glance.
Looking For More Ideas Beyond Jabil?
If you want to pressure test your view on Jabil against what else is out there, cast the net wider with a few focused stock shortlists built from the Simply Wall St Screener.
- For investors hunting for quality on sale, scan a curated set of companies through our 35 high quality undervalued stocks and see which ones merit a closer look.
- If capital protection is high on your list, narrow in on sturdier businesses by reviewing a 30 resilient stocks with low risk scores that may better fit your preferred risk profile.
- When balance sheet strength matters most, start your research with a list of solid balance sheet and fundamentals (23 results) that can anchor a more resilient portfolio.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com