


Capcom (TSE:9697) has drawn fresh attention after reporting half year sales of ¥120,887 million and net income of ¥43,083 million, alongside raising its second quarter dividend to ¥23 per share.
Capcom’s recent half year update and higher interim dividend come after a mixed price stretch, with the share price falling 8.8% over the past month but still showing a 9.8% year to date share price return and a 171% total shareholder return over five years, which indicates sustained longer term performance even as shorter term sentiment cools.
Spot 19 high quality undervalued stocks that, like Capcom after this dividend increase and earnings update, combine solid profitability with what could be more conservative pricing.Capcom shares now trade at a discount to analyst targets despite higher earnings and a richer interim dividend. Is that caution a warning sign or an opening on valuation grounds?
Most Popular Narrative: 6% Undervalued
Capcom last closed at ¥4,025, while the most followed valuation narrative pegs fair value at ¥4,300. That gap is small but meaningful, and it frames how some investors are thinking about both the higher dividend and the current share price.
The move decomposes cleanly, which reassures me. From ¥3,049 in mid-May to roughly ¥4,130 now, trailing twelve-month EPS went from about ¥130 to ¥159, a 21.8% increase, while the trailing multiple expanded from 23.4x to 26.0x. Around two-thirds of the rally is earnings that actually landed, one-third is the market paying more for them. That is a materially healthier composition than a sentiment melt-up, and it is the reason I am comfortable adjusting my estimate upward rather than concluding the stock has run away.
See why 13 investors see Capcom as 6% undervalued.
Result: Fair Value of ¥4,300 (UNDERVALUED)
Still, any break in Capcom’s flagship release schedule or a weaker reception for its premium titles could quickly challenge this view of the shares as undervalued.
Find out about the key risks to this Capcom narrative.
Another View on Capcom’s Valuation
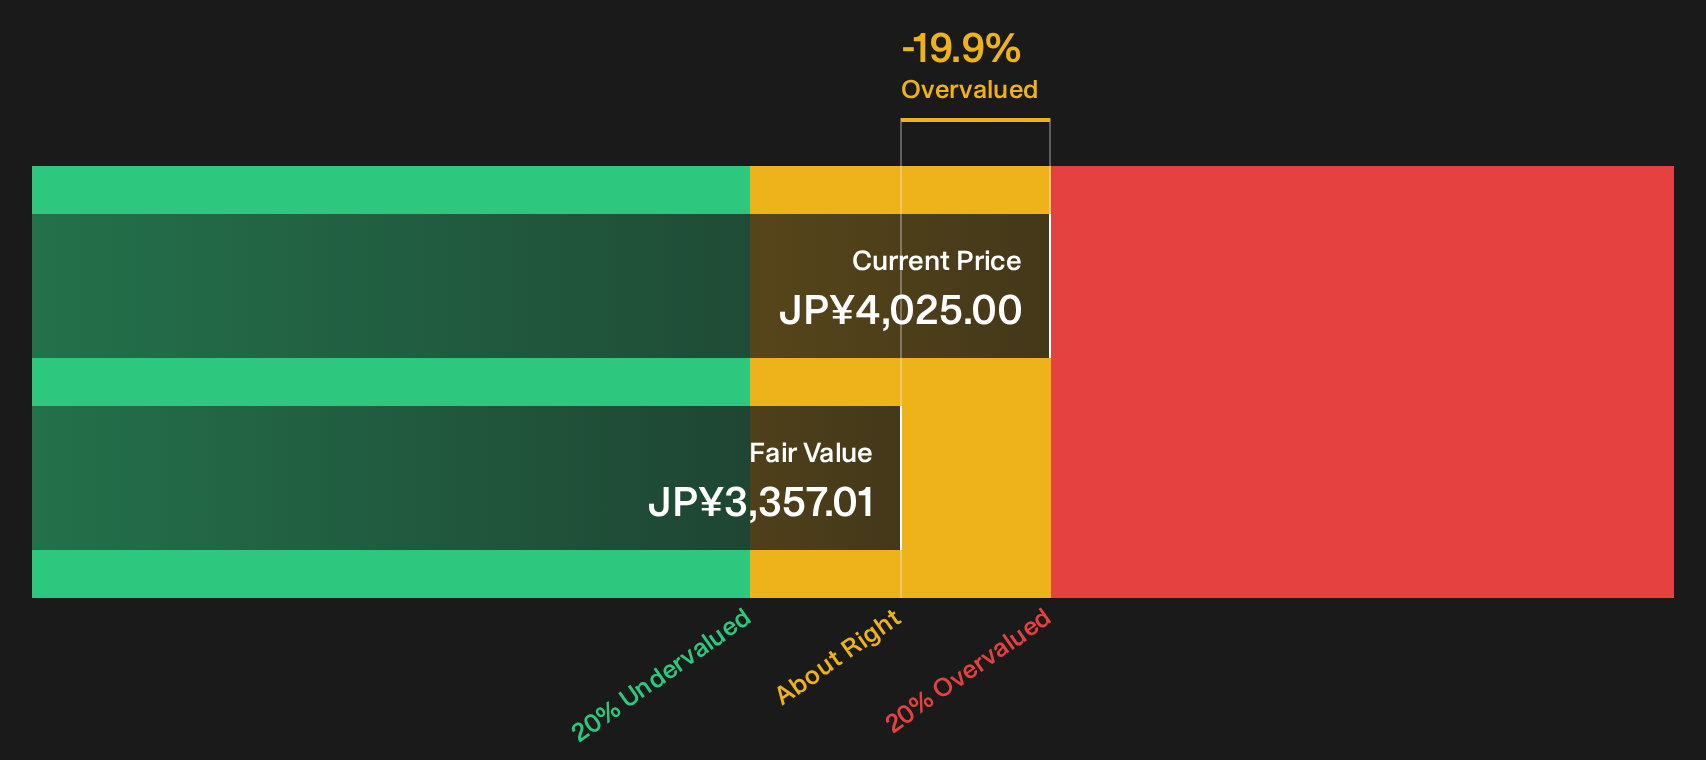
The popular narrative has Capcom at a fair value of ¥4,300 and therefore 6% undervalued at ¥4,025. Our DCF model tells a different story. On that approach, the estimated future cash flow value is ¥3,357, which leaves the shares looking expensive rather than cheap.
This gap between a cash flow based estimate and a sentiment driven fair value raises a simple question: Is the current price reflecting durable earnings power or investors leaning too hard on recent results and franchise strength?
Look into how the SWS DCF model arrives at its fair value.
Next Steps
Mixed signals on Capcom so far. For a clear takeaway, move quickly from headline impressions to the underlying numbers and compare both the 2 key rewards and 1 important warning sign.
Looking for more investment ideas beyond Capcom?
Capcom’s story is only one option. Broaden your watchlist now so you are not relying on a single theme or opportunity set.
- Target potential mispricings by scanning a focused 19 high quality undervalued stocks that filters for quality businesses trading on what may be more cautious expectations.
- Build a sturdier core to your portfolio with a list of solid balance sheet and fundamentals (22 results) that can help you focus on companies carrying less financial strain.
- Get ahead of the crowd by surfacing 74 high quality undiscovered gems that combine stronger fundamentals with limited current attention from the wider market.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com