


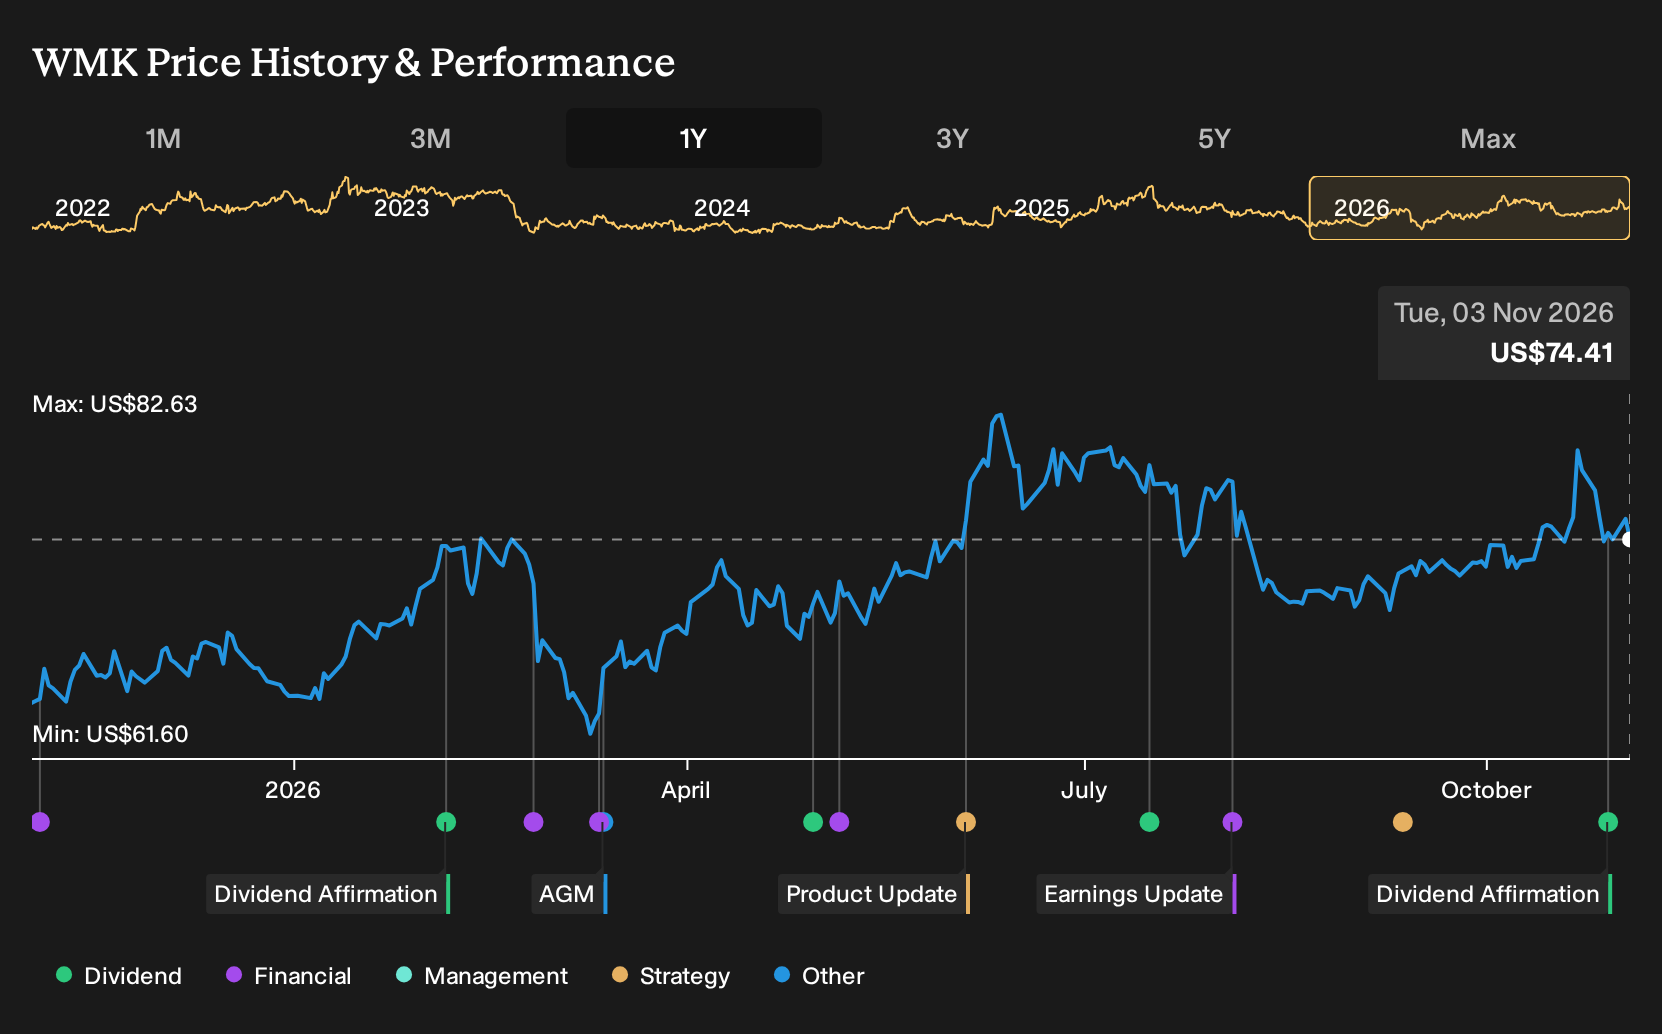
- Weis Markets reported third quarter 2026 revenue of US$1,279.09 million and net income of US$22.21 million, with basic and diluted EPS from continuing operations of US$0.90, along with continued quarterly dividends of US$0.34 per share.
- The supermarket operator paired rising earnings with an amended unsecured revolving credit facility of up to US$100 million in total availability. This facility supports liquidity while tying management to specific debt covenants and a minimum trailing twelve month EBITDA of US$175 million.
- We will now look at how Weis Markets' higher quarterly earnings and updated credit facility may influence the broader investment narrative.
Scan how Weis Markets' earnings, dividend and fresh credit capacity stack up against 30 resilient stocks with low risk scores that pair resilient cash generation with conservative financing profiles.
What Is Weis Markets' Investment Narrative?
Weis Markets appeals to shareholders who want a fairly simple story. You are backing a regional supermarket chain that depends on steady foot traffic, tight cost control, and disciplined capital use rather than big acquisitions or heavy leverage. The third quarter print fits that script. Revenue and earnings rose compared with last year, and nine month EPS from continuing operations reached US$2.95. That is the kind of grind it out execution that tends to matter more for a grocer than any one quarter’s market reaction.
The amended revolving credit facility to 2030, largely undrawn and tied to a US$175 million EBITDA covenant, adds flexibility around working capital, fuel operations, and store projects without forcing near term principal repayments. The dividend at US$0.34 per share continues to signal a focus on cash returns. The tension for investors is that Weis Markets has a history of declining earnings over five years and a P/E above the Consumer Retailing average, so the thesis now leans on management turning better recent performance into something more durable.
Even so, before treating this as a simple “safe grocer” idea, there is one structural pressure on Weis Markets that rarely shows up in headline numbers.
There's only one way to know the right time to buy, sell or hold Weis Markets. Head to Simply Wall St's company report for the latest analysis of Weis Markets's Fair Value.
Form Your Own Verdict
Disagree with this assessment? Extraordinary investment returns rarely come from following the herd, so go with your instincts.
- A great starting point for your Weis Markets research is our analysis highlighting 2 key rewards and 1 important warning sign that could impact your investment decision.
- See our latest analysis for Weis Markets. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Weis Markets' overall financial health at a glance.
Looking For More Investment Ideas Beyond Weis Markets?
If you want to stress test your view on Weis Markets against other opportunities, the Simply Wall St Screener can help you quickly filter for different types of businesses that match your risk appetite and income goals.
- If capital preservation is your priority, you can start with companies that pair durable earnings with measured leverage by reviewing the 30 resilient stocks with low risk scores.
- If you want income to play a bigger role in your portfolio, you may consider stocks that combine higher yields with balance sheet support through the 4 dividend fortresses.
- If you are hunting for quality that is not yet widely followed, you can look at fundamentally sound opportunities on the 19 high quality undiscovered gems.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com