


DoubleVerify Holdings (DV) is back in focus after releasing third quarter 2026 results, with sales of US$205.64 million and net income of US$15.93 million attracting fresh attention from investors.
At a share price of US$13.54, DoubleVerify Holdings has seen a 90 day share price return of 12.93% and a year to date share price gain of 24.68%. The 1 year total shareholder return of 21.44% contrasts with a 3 year total shareholder return that has declined 54.10%, which hints that recent earnings strength is only beginning to rebuild confidence after a much weaker longer term experience for holders.
Spot fresh momentum in ad tech and then broaden your watchlist with a curated set of 41 profitable AI stocks that aren't just burning cash that pair real earnings with exposure to AI driven advertising and automation.For DoubleVerify Holdings, this rebound could be a simple rerating after a harsh three year slide, or a cleaner reflection of improving earnings power. The next step is testing whether the current price matches those fundamentals.
Most Popular Narrative: 0% Overvalued
On the most followed narrative, DoubleVerify Holdings screens as roughly in line with a fair value of $13.48 against the latest close at $13.54. That story frames the recent rebound as a price catching up to fundamentals rather than a clear bargain or excess.
The main thing that has to go right is that DoubleVerify scales its verification, activation and measurement tools across walled gardens and CTV while preserving high gross margins as AI driven efficiencies are executed.
The current valuation and agreed US$13.60 per share takeout price imply the market is pricing DoubleVerify as fairly valued, with a bullish skew on the durability of its growth and margin profile.
See why 28 investors see DoubleVerify Holdings as 0% overvalued.
Result: Fair Value of $13.48 (ABOUT RIGHT)
Still, DoubleVerify Holdings faces real pressure if social and CTV partners tighten data access or if sales investments outweigh AI efficiency gains and stall margin progress.
Find out about the key risks to this DoubleVerify Holdings narrative.
Another View: Cash Flows Paint A Different Picture
The fair value story on DoubleVerify Holdings shifts when you move from earnings multiples to cash flows. Our DCF model points to a value of about $22.88 per share versus the current $13.54, which suggests the market is pricing DV well below those projected cash flows. If earnings look expensive but future cash generation screens cheap, which signal do you trust more?
Before leaning on either method too heavily, it helps to see exactly how this cash flow view is built out in practice, step by step, through the SWS DCF model. Look into how the SWS DCF model arrives at its fair value.
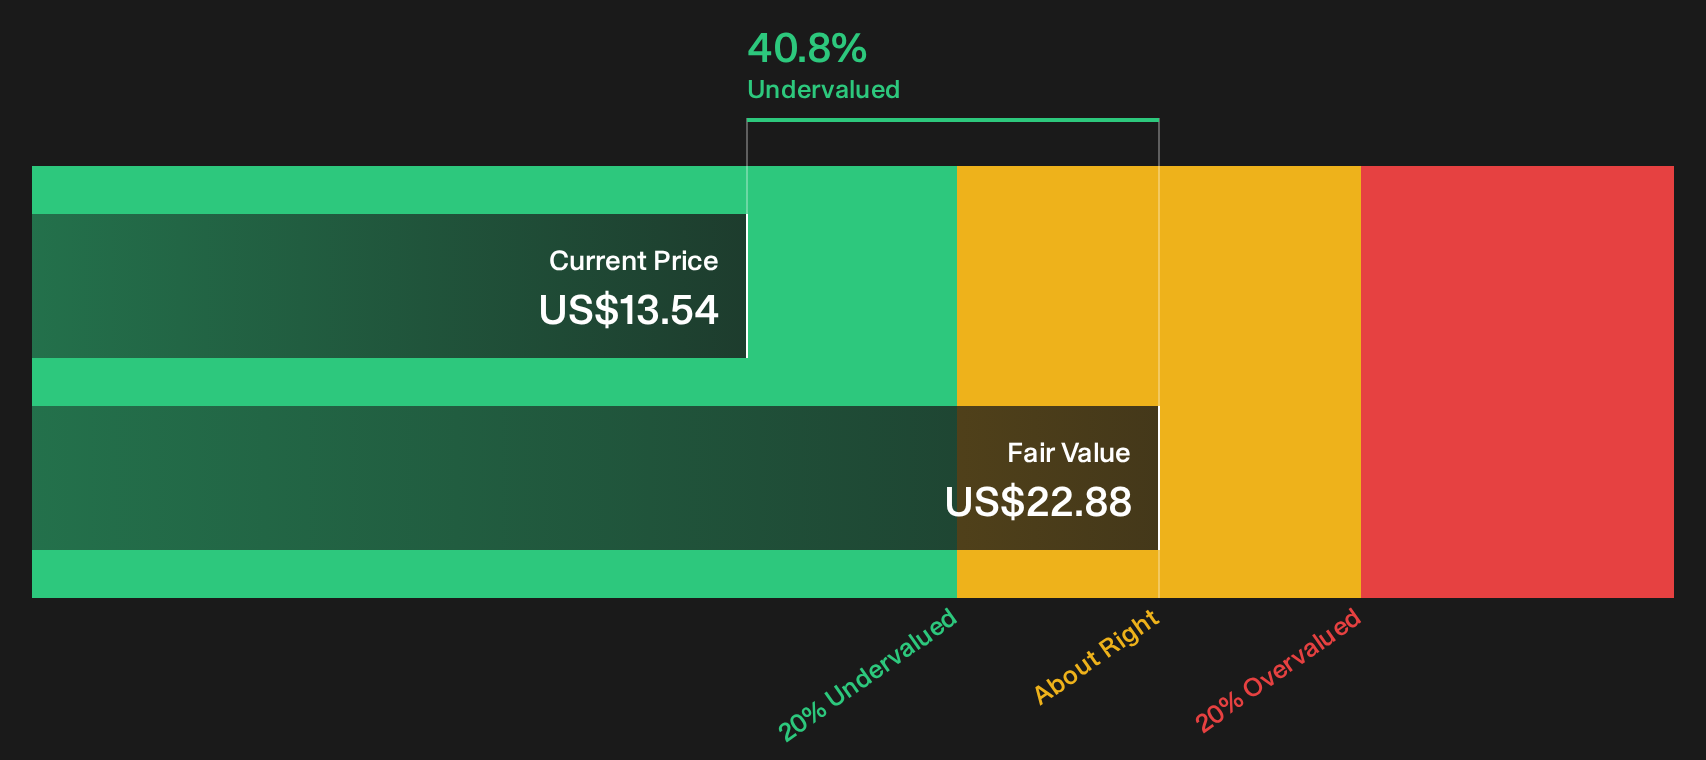
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out DoubleVerify Holdings for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 35 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
Is the market accurately valuing DoubleVerify Holdings, or is it still catching up? If you want to stress test the optimism around this story, review the 3 key rewards.
Ready for more investment ideas beyond DoubleVerify Holdings?
If DoubleVerify has sharpened your focus, widen the lens. Fresh ideas often come from comparing a current holding with completely different types of opportunities.
Use the Simply Wall Street Screener to quickly surface three very different starting points for your next round of research.
- Target potential mispricing by scanning a curated 35 high quality undervalued stocks that could help you spot opportunities before attention fully returns to them.
- Prioritise resilience first and chase growth second by leaning on a 30 resilient stocks with low risk scores that screens for businesses with sturdier risk profiles.
- Hunt for future leaders early by working through a focused 19 high quality undiscovered gems that highlights companies with strong fundamentals yet limited market attention.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com