


The derivatives market is aggressively betting on a post-earnings decline in Airbnb (ABNB) stock. The vacation rental giant is set to report its Q3 results after the market closes on Nov. 5. Consensus is for ABNB to report $2.86 in earnings per share (EPS) for its third financial quarter, which would represent a 29.41% growth on a year-over-year basis.
Heading into the quarterly print, Airbnb shares are up more than 25% versus the start of this year.
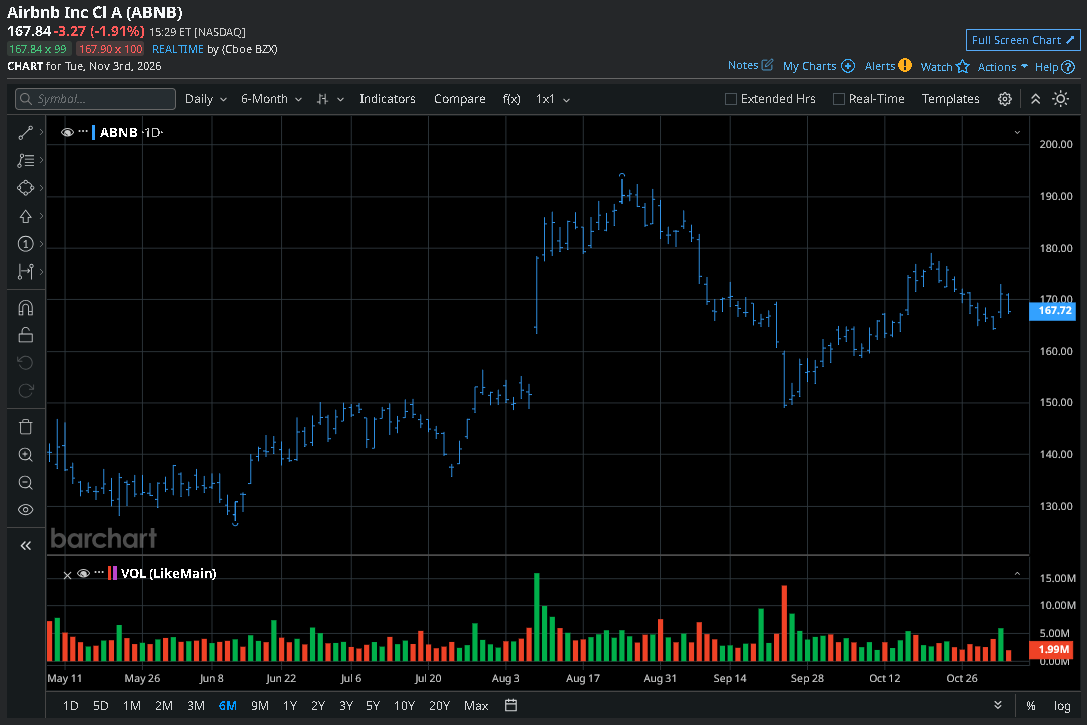
Where Options Data Suggests Airbnb Stock Is Headed
In the options market, when traders are betting increasingly on puts rather than calls, the data is seen as bearish.
For ABNB contracts expiring Nov. 13, the put-to-call ratio is currently set at a rather alarming 7.75x, with the lower price indicating potential downside of 3.43% to less than $163 by the end of next week.
Part of the bearish options market sentiment may be due to valuation concerns. Airbnb is currently trading at about 31x forward earnings, which makes it expensive for a hospitality company.
What Else Warrants Parting Ways With ABNB Shares
Historically, Airbnb stock ended November with a loss of 0.18% on average, followed by a gain of just 0.1% in December — a seasonal trend that further dulls its near-term appeal.
Investors should also note that insiders have predominantly unloaded company shares as their price continued to push higher, the optics of which are clearly bearish for ABNB.
Even from a technical perspective, Airbnb remains below its major moving averages (20-day and 50-day), reinforcing that bears remain in control for the near term.
All in all, Barchart’s options and technical data suggest much of the upside is already baked into Airbnb, and the path of least resistance appears to be lower from here.
How Wall Street Recommends Playing Airbnb
On the flip side, however, Wall Street analysts remain convinced that ABNB shares can rip higher through the end of this year.
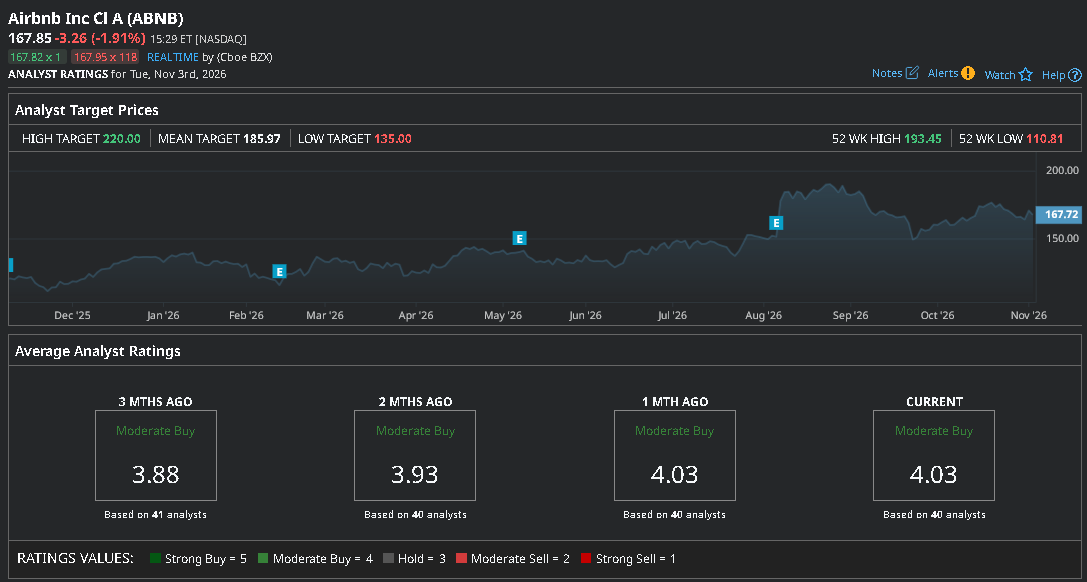
The consensus rating on Airbnb sits at “Moderate Buy,” with the mean price target of about $186 indicating the company’s share price rally is not out of steam just yet.
On the date of publication, Wajeeh Khan did not directly have a position in any of the securities mentioned in this article. All information and data in this article is solely for informational purposes. For more information please view the Barchart Disclosure Policy here.