


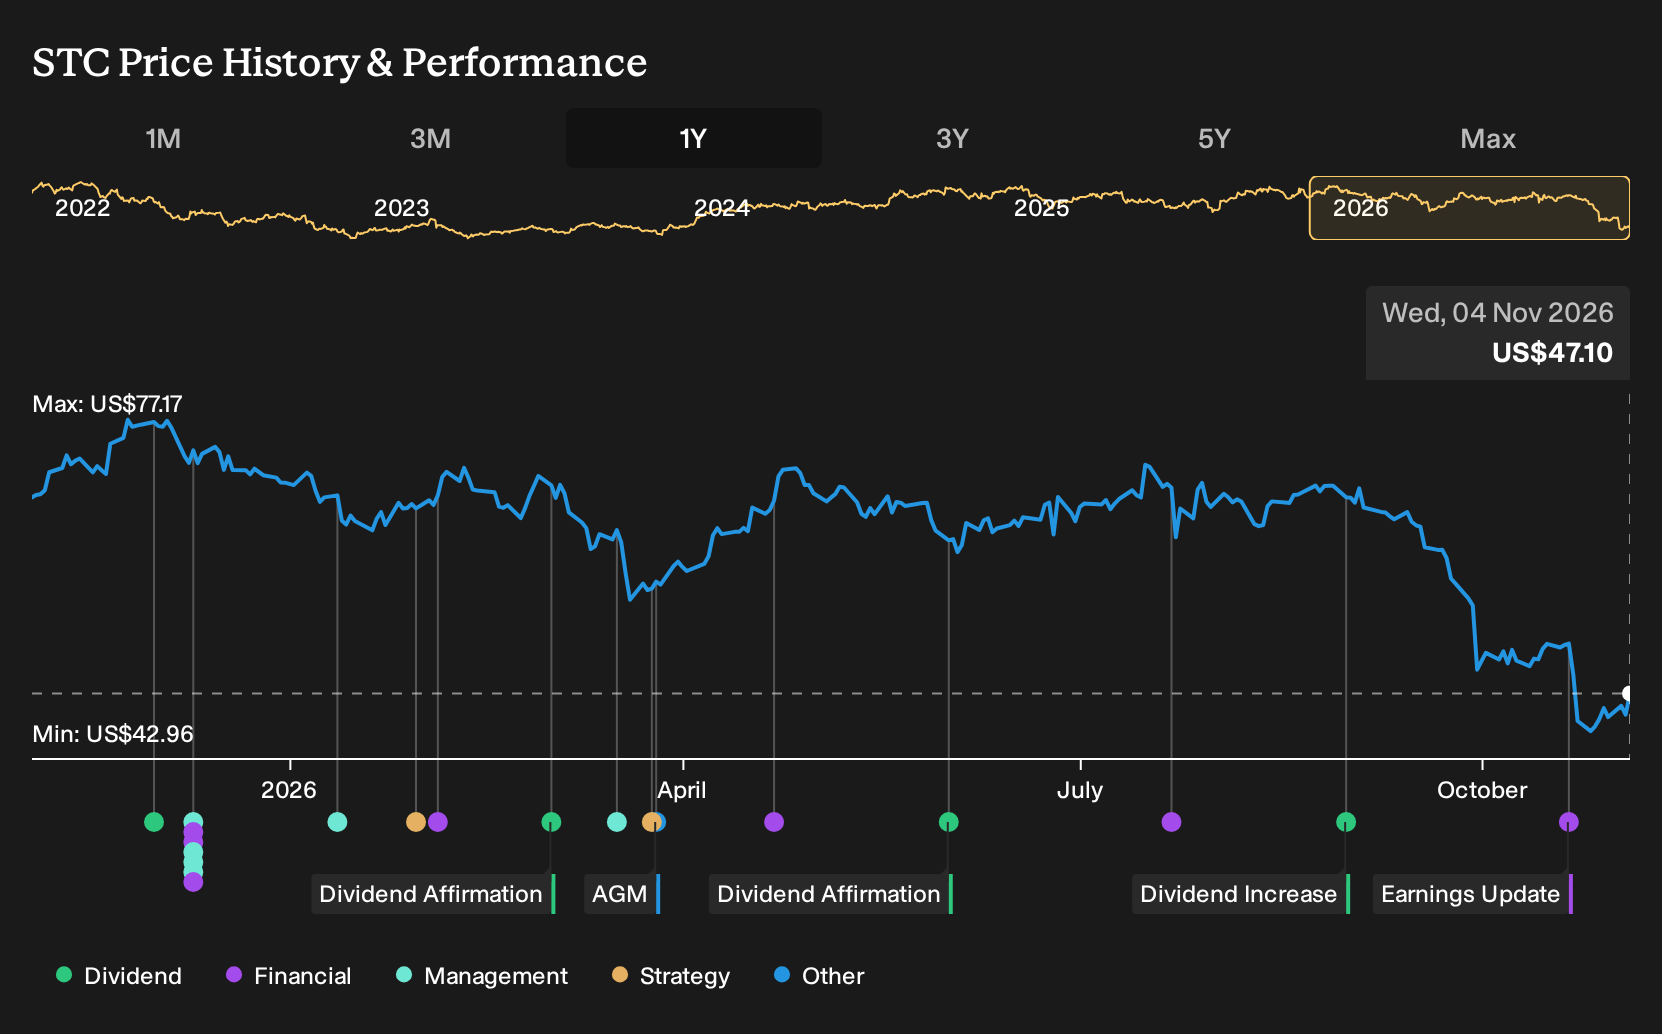
- Stewart Information Services reported Q3 2026 results, with revenue of US$900.68 million compared with US$796.92 million a year earlier, and diluted EPS from continuing operations of US$0.98 versus US$1.55.
- The nine month figures showed revenue of US$2.58b compared with US$2.13b and net income of US$84.5 million versus US$79.26 million, indicating higher sales alongside compressed earnings per share.
- We will now explore how Stewart Information Services' higher Q3 2026 revenue but softer quarterly earnings per share shape the existing investment narrative.
Scan beyond Stewart Information Services and compare this earnings pattern with hand-picked peers using the list of solid balance sheet and fundamentals (23 results) for ideas with resilient finances and steadier profit profiles.
Stewart Information Services Investment Narrative Recap
For an investor to stay with Stewart Information Services, the belief needs to be that higher quality commercial title, Real Estate Solutions and agency operations can gradually offset a sluggish US housing market and an elevated cost base. The latest quarter fits that story only partially. Revenue over the quarter and nine month period rose, but quarterly EPS and net income softened.
The key near term catalyst is still execution in the higher margin segments and in acquisitions, while keeping operating expenses in check. On that front, the Q3 2026 report does not look like a major break in the story. However, the lower quarterly earnings highlight how quickly profit can be squeezed if housing volumes or expense discipline disappoint.
The Q3 and nine month earnings release on October 21, 2026 matters most because it updates how the Real Estate Solutions and title operations are absorbing higher outside services, data and contractor costs. With the other operating expense ratio already flagged as a pressure point, the mix of higher sales but softer EPS keeps that risk very visible.
For catalysts, investors are still watching whether commercial title work in areas like energy and data centers, plus Real Estate Solutions growth, can support better adjusted margins. The latest figures show revenue scale is present, but the gap between top line progress and earnings per share keeps the focus on cost control and integration of past acquisitions rather than on new initiatives.
Stewart Information Services' current analyst script points to revenues of US$4.1b and earnings of US$190.2 million by 2029, based on an assumed 7.8% yearly revenue growth rate and an earnings increase of about US$55.5 million from US$134.7 million today.
Uncover how Stewart Information Services' fair value indicates a 62% potential upside to its current price before the market closes that gap.
Exploring Other Perspectives
One alternate view focuses squarely on Stewart Information Services’ cost base. The most cautious analysts were assuming only 5.7% yearly revenue growth to roughly US$4.0b by 2029 and earnings of about US$138.4 million. Those forecasts came before this Q3 release, so use them as a reference point and compare several viewpoints before deciding what you think might change.
Explore another Stewart Information Services fair value estimate, including one that suggests as much as 23% downside from the current price.
Decide For Yourself
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so go with your instincts.
- A great starting point for your Stewart Information Services research is our analysis highlighting 5 key rewards that could impact your investment decision.
- See our latest analysis for Stewart Information Services. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Stewart Information Services' overall financial health at a glance.
Looking for more investment ideas beyond Stewart Information Services?
Once you have a view on Stewart Information Services, it helps to broaden your watchlist with companies that match the kind of balance sheets, income streams and risk profile you prefer.
- For steadier balance sheets and fewer financing surprises, start with a list of solid balance sheet and fundamentals (23 results) that filters for stronger financial foundations and cleaner fundamentals.
- If value is your priority, consider a 34 high quality undervalued stocks focused on quality businesses that screen cheaply on fundamentals and may warrant a closer look.
- Income focused investors can shortlist potential yield candidates by reviewing a 4 dividend fortresses that highlights higher payout opportunities with robust underlying metrics.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com