


Ninety One Group (LSE:N91) has drawn fresh attention after releasing new research on commodities, arguing that the old China driven super cycle has given way to tighter supply and geopolitical fragmentation.
Ninety One Group's own stock has had a mixed run, with a 1-day share price return of 1.38% and a 7-day gain of 1.98% offering a short burst of positive momentum. However, the 90-day share price return declined 7.47% and, year to date, the move is down 5.17%, while the 3-year total shareholder return of 51.75% and 5-year total shareholder return of 13.36% point to a stronger longer term record.
Spot emerging beneficiaries of the same AI driven power and commodities squeeze that is shaping Ninety One Group's thesis by scanning our hand picked 53 AI infrastructure stocks.Ninety One Group now trades at £2.06 with analyst targets near £2.33 and an intrinsic value estimate that implies a smaller gap. Which of those anchors, if either, looks closest to fair value?
Most Popular Narrative: 13% Undervalued
The most followed narrative pegs Ninety One Group's fair value at £2.37, which sits above the last close of £2.06 and frames the current discount through the lens of long term earnings power and capital returns.
The business remains capital-light and margin-rich, has continued disciplined cost management, and regularly returns capital to shareholders via buybacks and dividends. These features support robust long-term earnings, cash flow generation, and return on equity, increasing the firm's long-term intrinsic value.
See why 16 investors see Ninety One Group as 13% undervalued.
Result: Fair Value of £2.37 (UNDERVALUED)
Still, if the Sanlam deal delivers stronger than expected AUM growth or AI investments improve efficiency faster than forecast, Ninety One Group's current discount could narrow.
Find out about the key risks to this Ninety One Group narrative.
Another View: Ninety One Group On Earnings Multiples
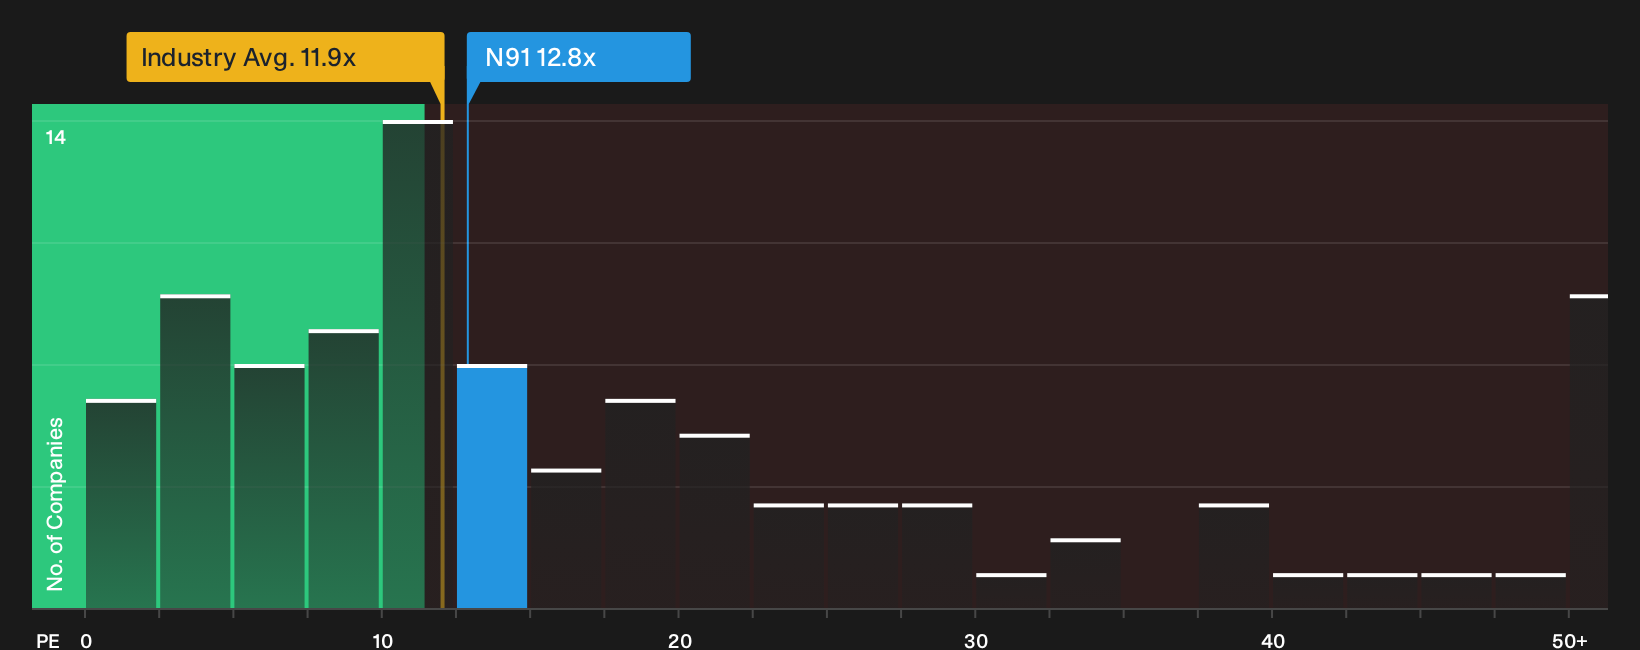
The narrative fair value for Ninety One Group suggests upside, yet the current P/E of 12.8x paints a more restrained picture. That figure is slightly above the UK Capital Markets industry on 11.9x, but a touch below the peer average on 13.5x and under the fair ratio of 13.2x that the market could drift toward.
In plain English, the stock is not screamingly cheap or wildly expensive on earnings. It trades close enough to both peers and the fair ratio that any move from here probably relies more on how margins, flows and fees evolve than on a simple re-rating. Which matters more for you: the discount to fair value, or the risk that the multiple already reflects a lot of the story?
See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
That mix of caution and optimism only gets you so far. The real edge comes from checking the numbers directly and pressure testing the story yourself using the 2 key rewards.
Looking For More Investment Ideas Beyond Ninety One Group?
If Ninety One Group has sharpened your thinking, do not stop there. Use the Simply Wall Street Screener to spot fresh ideas before the crowd catches on.
- Target resilient compounding by scanning a 3 dividend fortresses that can potentially keep income flowing even when markets feel choppy.
- Hunt for mispriced quality with a 5 high quality undiscovered gems that the broader market may not be paying full attention to yet.
- Prioritise capital preservation by filtering for a 5 resilient stocks with low risk scores that aims to limit downside while still keeping growth on the table.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com