


- Meliá Hotels International reported third quarter 2026 sales of €424.3 million and revenue of €659.6 million, with quarterly net income at €74.6 million. Nine month revenue reached €1,709.3 million and net income was €67.1 million.
- The nine month period showed higher sales and revenue than a year earlier, but net income fell sharply from €150.9 million to €67.1 million. This highlights pressure on profitability despite stronger activity levels.
- We will examine how Meliá Hotels International's investment narrative is affected by higher revenue alongside sharply lower nine month net income.
Scan how Meliá Hotels International compares with other hospitality players under earnings pressure by reviewing the hand picked list of solid balance sheet and fundamentals (195 results) for potential resilience.
Meliá Hotels International Investment Narrative Recap
For an investor to stay with Meliá Hotels International, there needs to be confidence that higher activity levels eventually translate into healthier earnings again. The latest report shows third quarter sales and revenue above last year while nine month profit is much lower, so the near term story hinges on how efficiently the group runs its resort heavy footprint and controls costs.
The key short term catalyst is simple. You want to see evidence that stronger demand, especially in Spanish and resort markets, filters into margins rather than being absorbed by labor, energy, and financing costs. The biggest risk remains that higher expenses, climate related disruption or weaker international markets keep net income under pressure even when top line trends look solid.
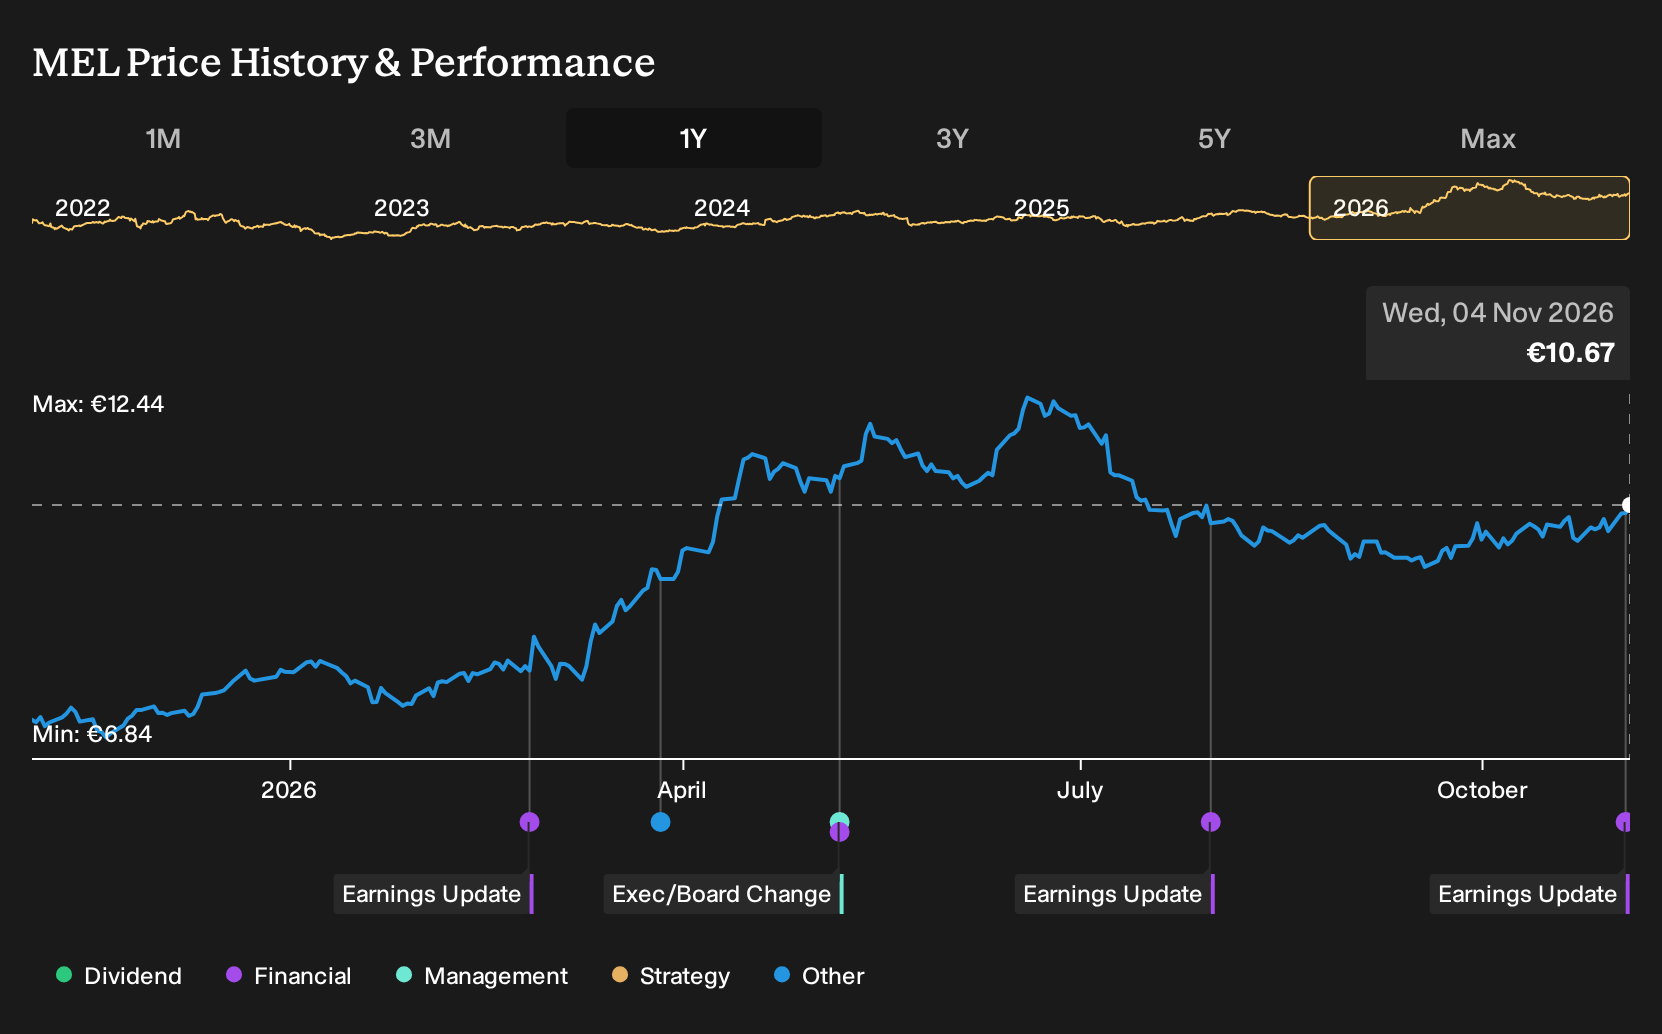
The third quarter and nine month earnings release is the main reference point right now. Meliá Hotels International reported nine month revenue of €1,709.3 million and net income of €67.1 million, compared with €1,595.2 million and €150.9 million a year earlier. That combination of higher activity with sharply lower profit forces you to focus on how sustainable the current cost structure really is.
For catalysts, the latest figures give you a real time test of the investment narrative around asset light growth, premium mix and digital direct booking. The numbers highlight that execution risk is not theoretical when debt is elevated and labor agreements are described as slightly worse than expected. In the short term, your attention is likely on whether upcoming quarters show any stabilisation in margins or further pressure on profitability.
Meliá Hotels International is currently framed by analyst expectations that revenues reach €2.3 billion and earnings come in at €189.0 million by 2029. This implies forecast revenue growth of 3.5% a year and an earnings increase of about €25.6 million from €163.4 million today.
Uncover why Meliá Hotels International's fair value indicates a 4% potential upside to its current price that could narrow quickly.
Exploring Other Perspectives
You see a very different story if you focus on cost inflation instead of revenue. The most pessimistic analysts were already assuming flat sales and earnings of about €159.5 million by 2029, compared with consensus forecasts of €189.0 million on roughly €2.3b of revenue. Those views, formed before this Meliá Hotels International earnings release, show how far opinions can spread. It can therefore help to explore the full range of scenarios before deciding how this latest report fits your own thesis.
Explore 3 other Meliá Hotels International fair value estimates, including one that suggests as much as 22% downside from the current price.
Decide For Yourself
Don't just follow the ticker. Dig into the data and build a conviction that's truly your own.
- A great starting point for your Meliá Hotels International research is our analysis highlighting 3 key rewards and 1 important warning sign that could impact your investment decision.
- See our latest analysis for Meliá Hotels International. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Meliá Hotels International's overall financial health at a glance.
Looking For More Investment Ideas Beyond Meliá Hotels International?
If this Meliá Hotels International earnings story has you rethinking your watchlist, it can help to scan wider across the market using focused stock lists built around clear traits, not hype.
- For investors who want income they can monitor closely, take a look at 215 dividend fortresses that may suit a yield focused approach.
- If capital preservation and steadier profiles matter most to you, consider reviewing 223 resilient stocks with low risk scores that fit tighter risk criteria.
- When you want quality that is not already crowded, scan 602 high quality undiscovered gems with stronger fundamentals that might not yet be widely followed.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com