


Versigent has delivered a sharp share price gain so far this year, and recent earnings headlines have kept attention firmly on the stock. The question for anyone looking at Versigent today is whether that higher price is adequately backed by its earnings power.
- With a year to date return of 39.0%, a lot now hinges on whether the current valuation can be supported by the profits the business is generating.
- Fresh results highlighted growth in net sales and Adjusted EBITDA, which may support investor expectations for stronger earnings and cash generation over time.
- Your read on Versigent is one view; the desks covering it have another. See what analysts think Versigent's shares could be worth.
The issue now is whether Versigent's present share price, after this run and the recent news, is justified by its earnings when compared with the Fair Ratio benchmark.
If you are weighing Versigent at its current earnings-based valuation, it can help to compare it with other companies by scanning 34 high quality undervalued stocks.
Is Versigent a Bargain on Earnings?
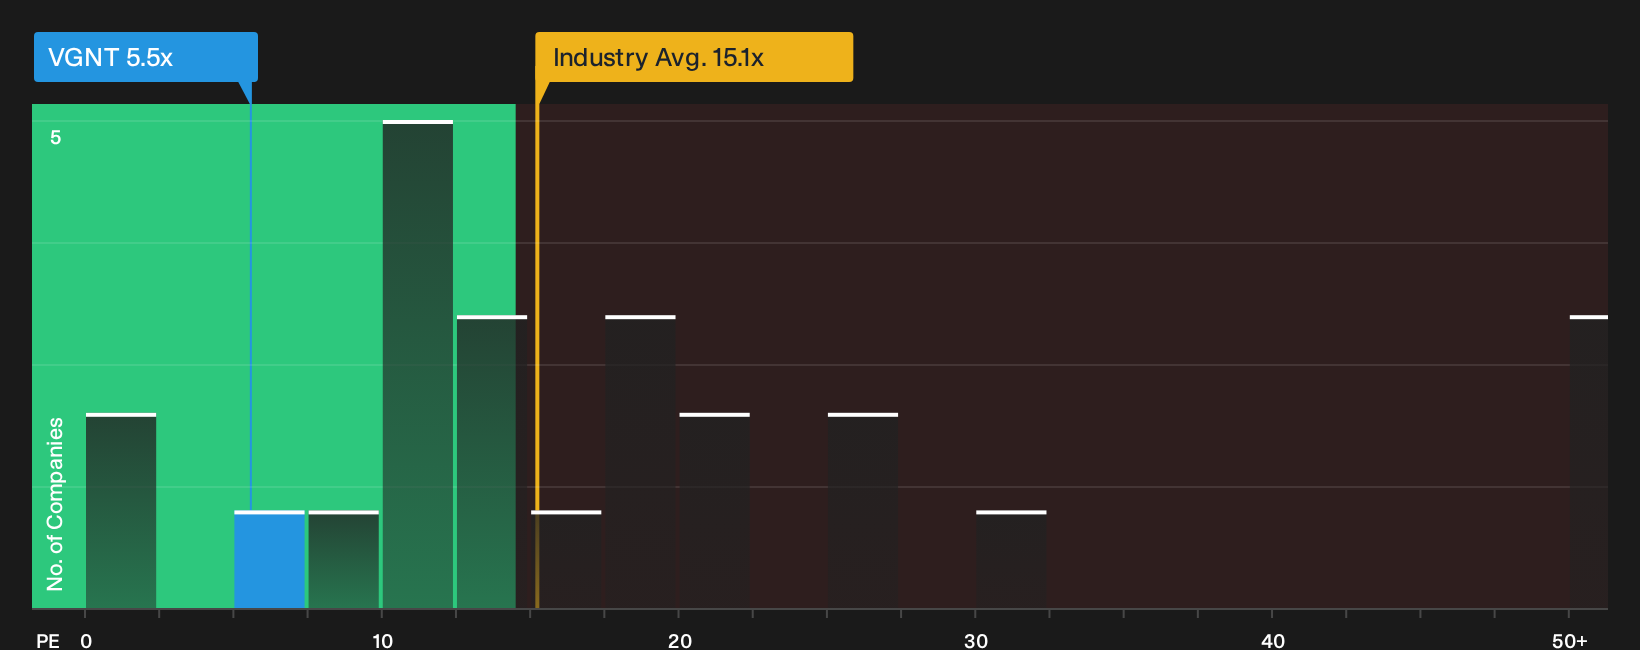
The P/E ratio suits Versigent because earnings are a key focus for this Auto Components business. On current figures, Versigent trades on a P/E of 5.7x, which is well below the Auto Components sector average of 15.1x and the wider peer group on about 13.9x. Against this backdrop, the Fair Ratio model, which blends factors like profitability, scale and risk profile, points to a higher earnings multiple than the market is currently paying. That gap suggests the stock screens as undervalued on this earnings yardstick.
Because management recently reported stronger net sales and double digit Adjusted EBITDA growth for the third quarter of 2026, this low P/E indicates the latest results have not closed the discount implied by the model. For anyone assessing Versigent today, the key question is whether the quality and durability of its profits justify the earnings multiple implied by the Fair Ratio rather than the one the market is assigning. Explore the numbers behind Versigent's P/E valuation.
The Versigent Narrative: What Would Justify Today's Price?
Versigent's fair value puzzle only starts with the P/E math. Narratives on Simply Wall St's Community page pick up where that leaves off by spelling out what would need to happen to future revenue, margins and earnings for the current share price to look high or low. Rather than relying on a single valuation output, each narrative lays out the assumptions behind its view so you can compare those assumptions with Versigent's reported numbers as they are released.
A clear, written Narrative on Versigent gives you a number driven view that spells out what assumptions need to hold for the current P/E and recent third quarter net sales, Adjusted EBITDA and free cash flow guidance to make sense. It creates a reference point you can test as new dividends, guidance updates and earnings results are reported over time.
Share your own Narrative for Versigent and set out the assumptions behind your valuation.
Versigent's price is only one piece of the decision
Before you weigh up Versigent purely on earnings and multiples, it is worth asking who is steering the business, how their incentives are structured and whether those rewards line up with your priorities as a shareholder. See who runs Versigent and how they are paid.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com