


- Timken reported third quarter 2026 sales of US$1,211.4 million and net income of US$93.8 million, with basic EPS from continuing operations of US$1.36.
- The nine month figures show higher sales of US$3,703.6 million alongside slightly lower net income and EPS, which points to mixed operating leverage beneath the headline growth.
- Next, the focus shifts to how Timken's stronger third quarter profitability influences the existing investment narrative around margins and portfolio mix.
Compare Timken's earnings profile with other industrials that have similar margin and balance sheet traits by scanning our hand picked list of solid balance sheet and fundamentals (23 results).
Timken Investment Narrative Recap
To own Timken, you need to believe that margin uplift from Elevate to Outperform and portfolio cleanup can matter more than modest top line growth. The latest quarter helps that case in the short run. Sales were US$1,211.4 million and net income reached US$93.8 million, so profitability improved even while nine month earnings stayed muted.
The key near term catalyst is execution on mix and cost work while handling slower organic growth that management itself had already guided lower. The biggest risk stays intact. Softer demand in solar and wind, higher aerospace costs and ongoing pricing and trade uncertainty could still squeeze margins if volumes soften again.
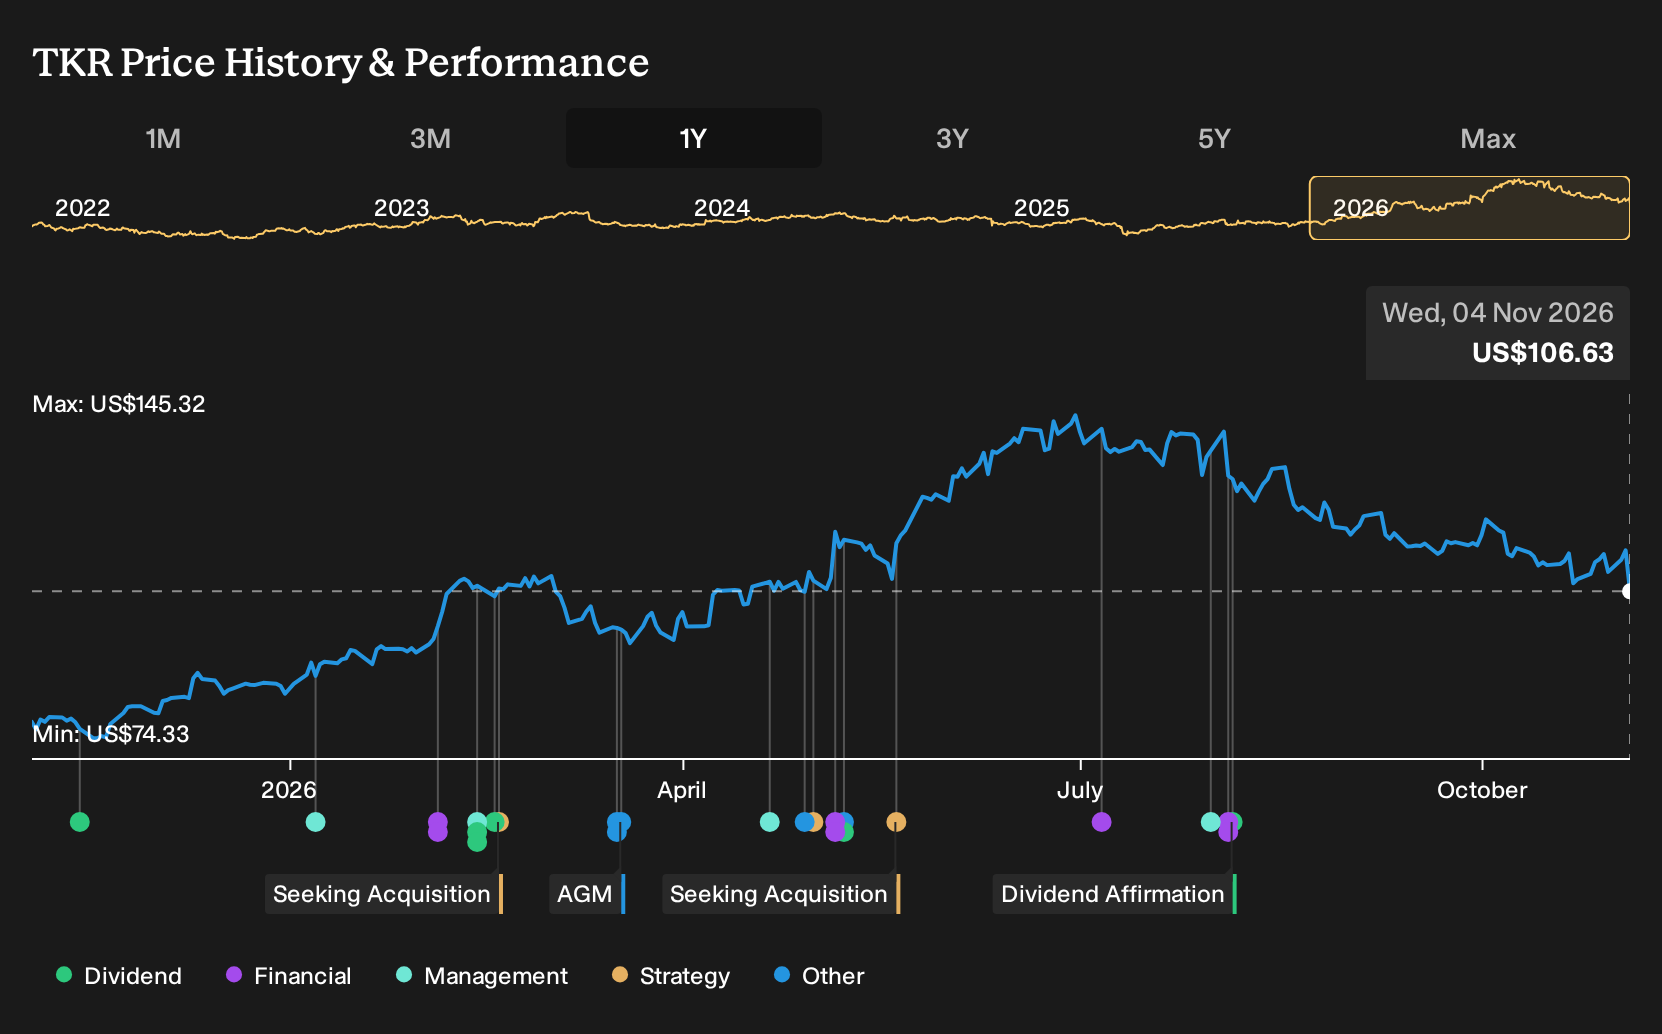
The most relevant fresh data point is the third quarter earnings release on 4 November 2026. Timken reported sales of US$1,211.4 million, up from US$1,157.1 million a year earlier, and basic EPS from continuing operations of US$1.36 versus US$0.99. That combination of higher revenue and stronger per share earnings gives investors a clearer read on current execution.
Across the first nine months, sales were US$3,703.6 million compared with US$3,470.8 million, while net income slipped to US$220.9 million from US$226.1 million and basic EPS from continuing operations edged down to US$3.18 from US$3.24. That contrast, healthier quarterly profitability against a flatter year to date picture, keeps the spotlight on whether cost programs and portfolio pruning can offset mix and demand headwinds.
Timken's current analyst narrative points to revenues of US$5.3b and earnings of US$626.4 million by 2029, based on 3.4% yearly revenue growth and an earnings increase of about US$367.7 million from US$258.7 million today.
Uncover why Timken's fair value indicates a 37% potential upside to its current price, which could materialize more quickly than many investors expect.
Exploring Other Perspectives
One alternate Timken angle you may want to test is the bullish call on Industrial Motion expansion. The most optimistic analysts were already modelling revenue of about US$5.5b and earnings near US$721.9 million by 2029, well above the consensus. This quarter’s earnings surprise could push those upbeat scenarios even further or prompt a rethink.
Explore 3 other Timken fair value estimates, including one that suggests a potential upside of as much as 68% from the current price.
Reach Your Own Conclusion
Don't just follow the ticker. Dig into the data and build a conviction that's truly your own.
- A great starting point for your Timken research is our analysis highlighting 3 key rewards and 3 important warning signs that could impact your investment decision.
- See our latest analysis for Timken. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Timken's overall financial health at a glance.
Looking for more investment ideas beyond Timken?
If Timken is on your radar, it can help to benchmark it against other businesses with different income profiles, balance sheets and return potential using the Simply Wall St Screener.
- For investors who want income to do more of the heavy lifting, consider dividend payers with higher yields and sturdy fundamentals through the 4 dividend fortresses.
- If your focus is on quality at a sensible entry price, scan for stronger balance sheets and attractive valuations with the 34 high quality undervalued stocks.
- When capital preservation sits higher on your checklist, sort for companies with more resilient risk profiles using the 30 resilient stocks with low risk scores.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com