


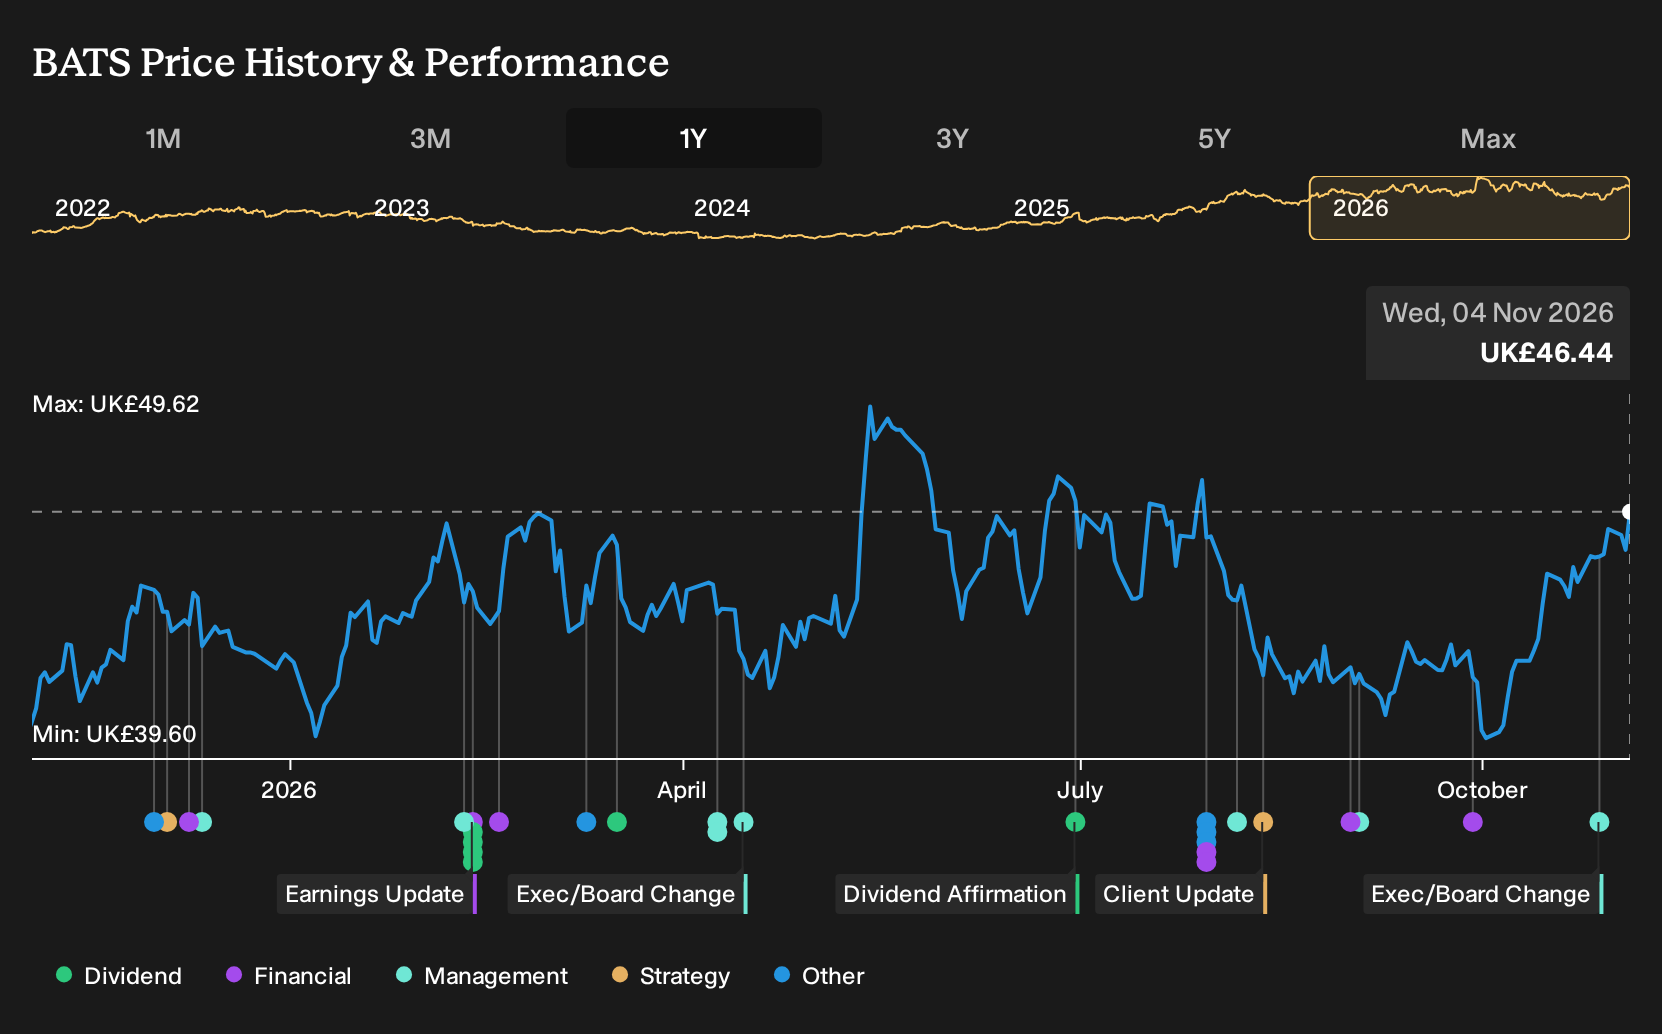
- British American Tobacco announced that Bruce Sewell, formerly General Counsel at Apple and Intel, will join its Board in January 2027 and sit on the Audit and Nominations Committees, alongside refreshed Audit and Remuneration Committee line ups that adjust non executive director responsibilities from late 2026.
- The appointment brings deep global legal, compliance and governance experience into British American Tobacco at a time when the group is investing in new nicotine products and managing complex regulation. This could influence how the business balances risk, oversight and capital allocation across both combustibles and New Categories.
- We will now look at how British American Tobacco's investment narrative could be influenced by growing New Categories momentum highlighted by Goldman Sachs.
British American Tobacco Investment Narrative Recap
To own British American Tobacco, you need to believe the group can keep shifting more revenue and profit toward smokeless products while holding enough pricing power in traditional cigarettes to fund that transition. In the near term, the key swing factor is whether New Categories such as Vuse, glo and Velo can keep building scale without eroding group margins.
The biggest immediate risk still sits in regulation and illicit trade, which can quickly hit reported volumes and pricing, especially in markets such as Brazil and South Africa. The board refresh around Bruce Sewell and committee changes appears directionally supportive for governance but does not fundamentally change those near-term operational drivers.
The recent Goldman Sachs upgrade that highlighted momentum in Vuse vapour and Velo Max nicotine pouches aligns closely with what matters most here. British American Tobacco needs New Categories to contribute a larger share of revenue over time, given pressure points in combustibles and the capital intensity of running parallel product portfolios.
For you as a shareholder, the focus is on how far that smokeless mix shift and programs such as Fit2Win can support earnings and cash generation, especially with a history of higher debt and a dividend payout that reached 91% of free cash flow in 2025. Execution on reduced-risk products and cost savings is likely to matter more to the overall story than the board changes alone.
British American Tobacco's current analyst script points to revenues of £28.6 billion and earnings of £8.7 billion by 2029, based on an assumed 3.5% yearly revenue growth rate and an increase in earnings of about £2.4 billion from £6.3 billion today.
Uncover why British American Tobacco's fair value indicates an 11% potential upside to its current price that could narrow quickly.
Exploring Other Perspectives
Some of the lowest British American Tobacco forecasts lean hard into the risk that cigarette volume pressure and new vaping taxes squeeze returns, which they saw capped at about £28.2b of revenue and £7.5b of earnings by 2029. You might read those projections as cautious anchors. Board changes, such as Bruce Sewell’s arrival, could eventually shift these narratives. Treat this as a cue to compare several viewpoints rather than settle on a single story.
Explore 5 other British American Tobacco fair value estimates, including one that suggests there could be as much as 9% downside from the current price.
Form Your Own Verdict
Don't just follow the ticker; dig into the data and build a conviction that's truly your own.
- A great starting point for your British American Tobacco research is our analysis highlighting 3 key rewards and 2 important warning signs that could impact your investment decision.
- See our latest analysis for British American Tobacco. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate British American Tobacco's overall financial health at a glance.
Looking for more British American Tobacco investment ideas?
If British American Tobacco has sharpened your interest in how different business models handle risk, cash flow and capital allocation, it can be useful to line it up against a wider watchlist before making any decisions.
- For investors who want potential upside combined with financial resilience, start with a curated set of 5 high quality undiscovered gems that pair stronger fundamentals with cleaner balance sheets than many widely followed stocks.
- If income is your priority and British American Tobacco caught your eye for its payouts, broaden your options with a focused group of 3 dividend fortresses that clear higher yield and quality hurdles than the broader market.
- When capital preservation ranks highest on your checklist, reduce the noise and concentrate on a filtered pool of 5 resilient stocks with low risk scores that screen well on stability and risk metrics, not just headline growth stories.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com