


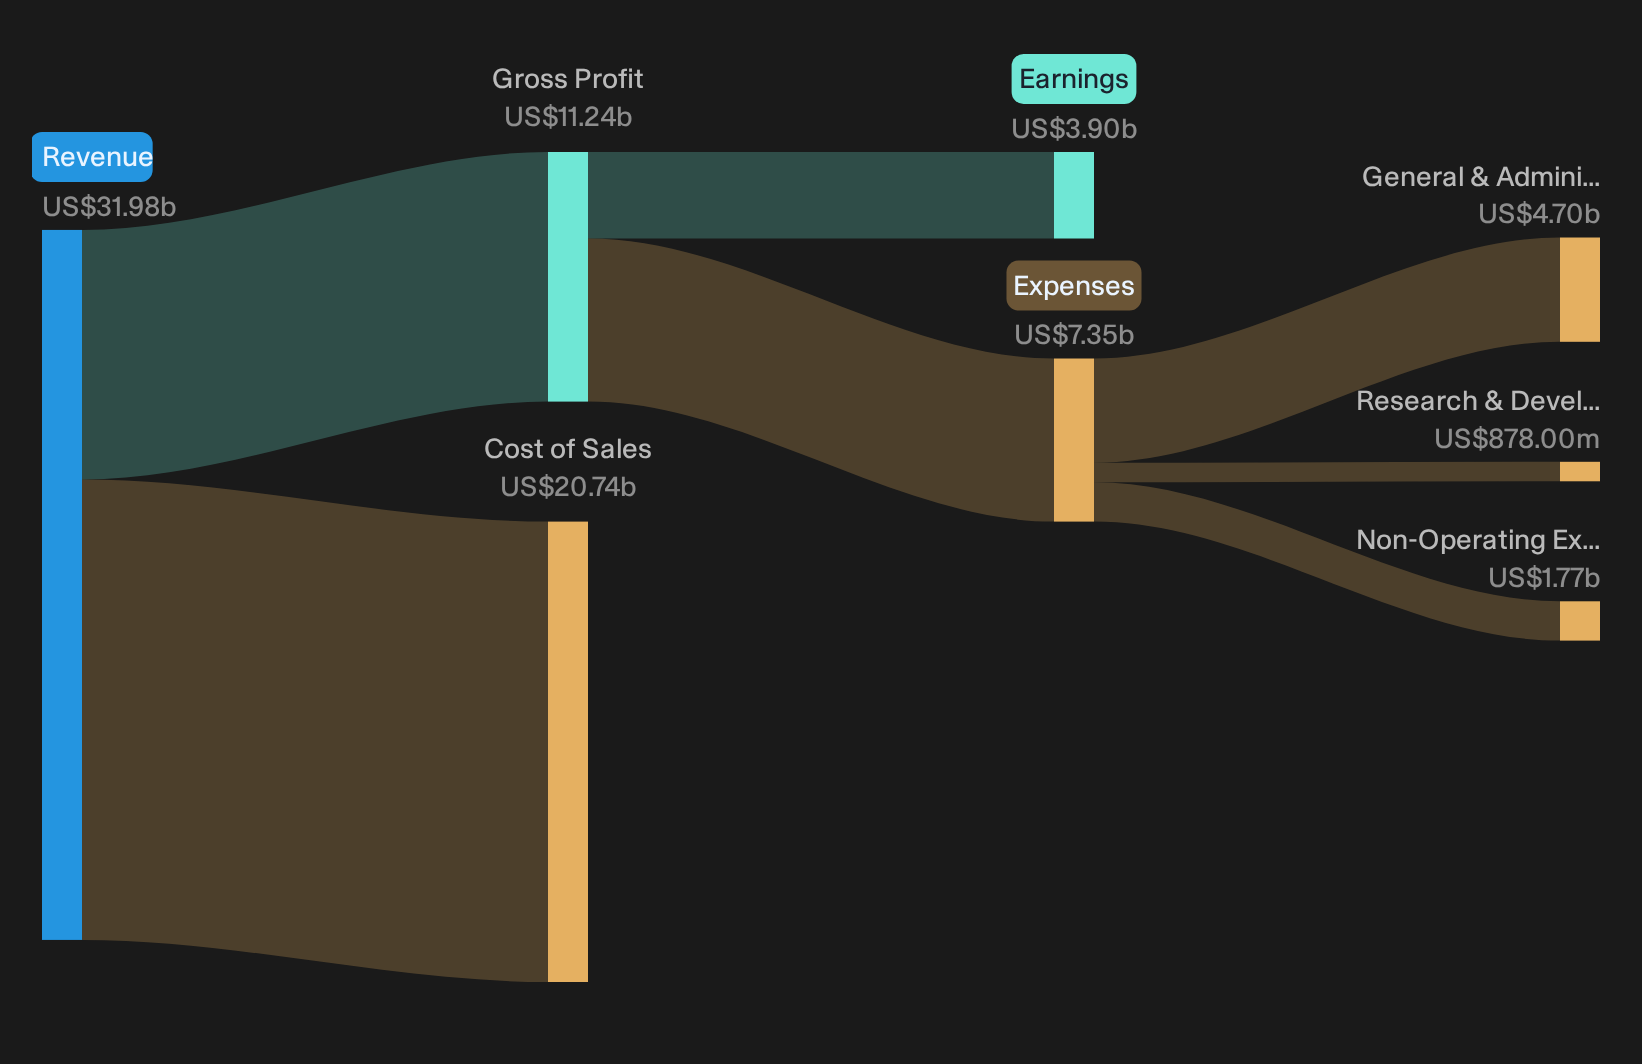
Eaton just reported a record Q3 2026, yet the stock sank almost 10% in Wednesday trading. That is a sharp move for an electrical equipment powerhouse that posted about US$8.9b in quarterly revenue and all-time high adjusted earnings per share of US$3.68.
The market focused on valuation and sentiment, while the results themselves highlighted strong margins. Segment profit in the core electrical operations reached record levels, which is more relevant for a long-term thesis than a single bruising session for the share price.
Love Eaton’s record profitability but uneasy about a sharp 10% share price drop on sentiment and valuation worries? Put those results in context by comparing Eaton against a curated screener of electrical and infrastructure peers in our 42 power grid technology and infrastructure stocks
Q3 2026 Earnings Summary
- Total Revenue (Q3 2026 vs. Q3 2025): US$8,947 million vs. US$6,988 million (up about 28%)
- Net Income, Excl. Extra Items (Q3 2026 vs. Q3 2025): US$1,078 million vs. US$1,010 million (up about 7%)
- Basic EPS (Q3 2026 vs. Q3 2025): US$2.77 vs. US$2.60 (up about 7%)
- Segment Margin, Company Level (Q3 2026): 25.3% compared with prior period record levels not specified (management highlighted this as a new high)
Prefer clean visuals over wading through dense earnings transcripts and spreadsheets? See Eaton’s full financial picture, including how the valuation compares with its recent record quarter, in the interactive company report for Eaton.
Eaton’s AI Power Thesis Meets Hard Numbers
Bulls argue that Eaton’s long game hinges on turning record electrical demand, especially from AI data centers, into durable earnings strength that compounds well beyond a single quarter.
"The main factor that has to go right is that Eaton continues to convert its record electrical backlog and large capacity expansion program into organic growth and high segment margins, while efficiently executing acquisitions and the planned Mobility separation."
Q3 data backs the first part of that claim. Organic sales in Electrical Americas and Electrical Global rose strongly, segment margins hit fresh highs, and management lifted 2026 organic growth and EPS guidance again, with Boyd Thermal and modular enclosures already scaling into that electrical backlog.
Not everyone reads the same price the same way. → See the higher figure this Narrative lands on, and how it gets there.
Eaton Backlog Fears Confront A Blowout Quarter
Bears question whether Eaton can turn today’s AI and grid surge into durable earnings once the backlog rolls off.
"The main thing that has to go right is that Eaton converts its record order books and large data center project pipeline into profitable revenue while maintaining the higher margin profile it has built through portfolio reshaping and recent deals such as Boyd and COL Group."
Q3 points the other way. Electrical Americas organic growth of 22%, record segment margins above 29%, and company level margins at 25.3% show backlog is converting and profitability is holding up. Raised 2026 organic and EPS guidance reinforces execution, even as the stock fell almost 10% on the print.
Hunt Dislocations Before They Close
Eaton just reported record profitability alongside a sharp share price hit. The real opportunity is hunting for stocks that could be undervalued before the market adjusts.
- Company 1 - 30% below our estimate - expand branded and private label coconut drinks as category demand broadens and cost pressures stay controlled.
- Company 2 - 50% below our estimate - scale an asset light hotel network while layering on an in house retail platform for guests.
- Company 3 - 24% below our estimate - ramp next generation NAND production so data center and edge customers can adopt higher density storage products.
Three companies from the same screener. Open all 33 potentially undervalued companies →
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com