


Kratos Defense & Security Solutions has seen its share price swing sharply in recent years, and the question now is whether the current US$35.91 level is properly supported by the cash the business can generate. With that in mind, the focus turns to what the company’s underlying cash flows suggest about an appropriate valuation.
- Over the past 3 years the stock has gained 106.6%, which puts real pressure on the cash flow story to justify how far it has already come.
- A recent US$33.6 million subcontract win related to NASA’s nuclear powered SR-1 Freedom spacecraft may support expectations for future contracts and could influence the timing and visibility of Kratos Defense & Security Solutions’ cash inflows.
- If you'd rather focus on sales, this one's for you. See why Kratos Defense & Security Solutions's 4.4x P/S tells a different valuation story.
The issue now is whether the intrinsic value suggested by Kratos Defense & Security Solutions’ cash flows lines up with where the shares trade today.
If you want a second reference point while you assess whether Kratos Defense & Security Solutions' cash flows justify today’s price, run the same lens across a curated set of 33 high quality undervalued stocks.
Is Kratos Defense & Security Solutions Still Cheap on Cash Flow?
The Discounted Cash Flow (DCF) model here focuses on the cash Kratos Defense & Security Solutions can return to shareholders over time. Latest twelve month free cash flow was a loss of $127.9 million, so the valuation leans heavily on a recovery path that shifts from negative outflows to positive inflows over the next decade.
Analysts feeding into this DCF framework expect Kratos Defense & Security Solutions’ free cash generation to move into growing territory, with higher projected cash inflows in the later years of the model. Because the Discounted Cash Flow (DCF) output sits meaningfully above the current US$35.91 share price, the assumptions imply the market is not fully reflecting that projected turnaround in cash generation. The recent US$33.6 million NASA SR-1 Freedom subcontract adds one concrete contract to that future cash flow story, although the timing and execution risk help explain why the price still sits below what the cash projections support. Find out what Kratos Defense & Security Solutions could be worth using our Discounted Cash Flow (DCF) estimate.
The Kratos Defense & Security Solutions Narrative: What Would Justify Today's Price?
Simply Wall St Narratives pick up where the Kratos Defense & Security Solutions valuation puzzle leaves off by spelling out which paths for future growth, margins and earnings would need to play out for the shares to be worth meaningfully more or less than today’s level. Each scenario ties a fair value estimate to a clear storyline about Kratos Defense & Security Solutions' potential catalysts and key risks, so you can track over time which version appears to be unfolding on the Community page.
One of the top community narratives on Kratos Defense & Security Solutions: 62% undervalued
"The current valuation implies the market is discounting the company’s raised 2026 organic growth guidance, margin expansion plans and growing backlog..."
Discover why this Narrative puts Kratos Defense & Security Solutions at 62% undervalued.
Kratos Defense & Security Solutions: One more factor that could reshape your view
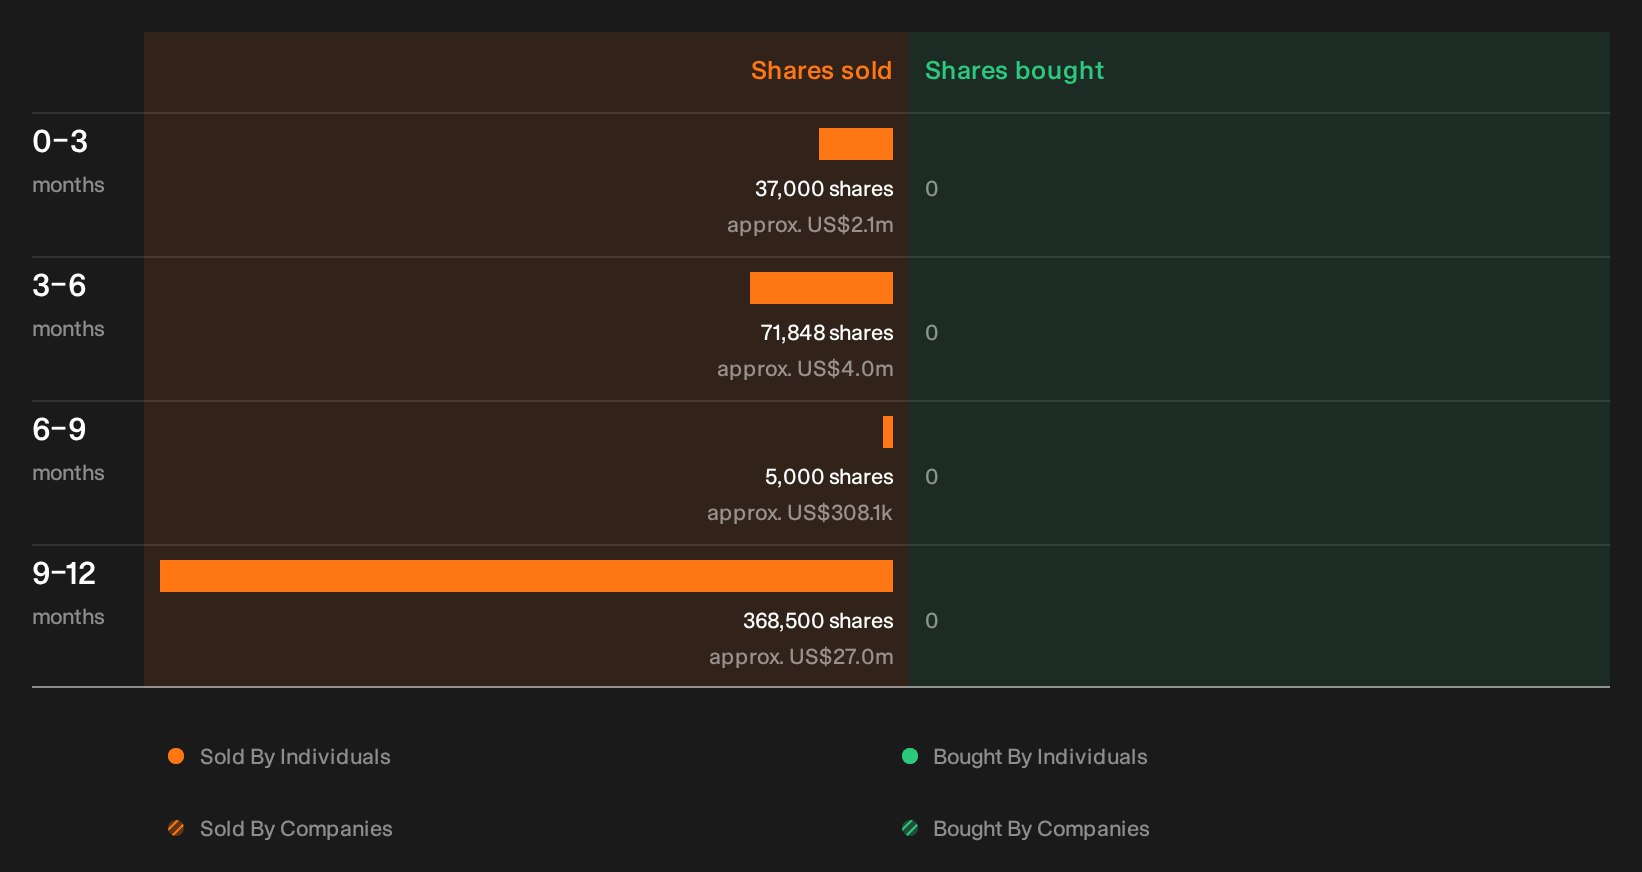
Price, contracts and cash flow only tell part of the Kratos Defense & Security Solutions story. Our checks have also picked up recent share sales by people on the inside, and the who, how much and why are still for you to unpack. See the recent insider selling flagged for Kratos Defense & Security Solutions.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com