


Hemlo Mining (TSX:HMMC) released unaudited third quarter operating and sales figures, giving investors fresh detail on gold production, ore processed and volumes sold across both the quarter and the first nine months of 2026.
Hemlo Mining’s latest operating update lands after a sharp 9.29% 1 day share price gain to CA$5.06, which comes against a 30 day share price return that declined 9.64% and a 90 day move that fell 13.80%. At the same time, the 3 year total shareholder return is very large and the 5 year total shareholder return declined 43.78%, suggesting short term enthusiasm is building on a much more volatile long term record.
Compare Hemlo Mining’s production update with a hand picked group of gold producers and miners screened for balance sheet strength and fundamentals using our list of solid balance sheet and fundamentals (6 results).
Hemlo Mining now trades at a steep discount to both analyst targets and an intrinsic value estimate, yet the mixed share price record still signals caution. Is the gap an opportunity, or a warning about what the market sees next?
Price-to-Earnings of 65.9x: Is it justified?
Valuation on Hemlo Mining quickly turns to its P/E ratio, which sits at 65.9x compared with a peer average of 18.4x and a Canadian Metals and Mining average of 13.4x. At a last close of CA$5.06, that sort of multiple points to a market that is already pricing in a lot of future progress rather than treating the stock as cheap relative to current earnings.
The P/E yardstick compares the share price to earnings per share and is a common way investors judge how much they are paying for each dollar of profit. For a gold producer like Hemlo Mining, a high P/E can signal that investors are focusing heavily on expected growth in earnings instead of the newly established profit base.
That context matters because HMMC has only recently become profitable and its reported net income over the last year includes a large one off loss of $15.1m, which distorts both current earnings and the quality score attached to them. The market is assigning a P/E that is roughly double the estimated fair P/E of 31x. This gap suggests expectations could have run well ahead of what the regression based fair ratio implies the valuation might move toward over time.
The comparison with peers is even starker. Against similar sized companies in the Canadian market the stock is described as expensive on a P/E basis, and against the broader Metals and Mining group the premium is larger again, with Hemlo Mining’s 65.9x multiple sitting far above the 13.4x sector average. In plain terms, investors are paying several times more per unit of current earnings than they are for a typical mining stock in Canada.
Explore the SWS fair ratio for Hemlo Mining.
Result: Price-to-Earnings of 65.9x (OVERVALUED)
Still, the premium P/E for Hemlo Mining leaves little room if earnings momentum slows, or if market confidence in its $16.3m profit base weakens.
Find out about the key risks to this Hemlo Mining narrative.
Another View On Hemlo Mining’s Value
The SWS DCF model paints a very different picture for Hemlo Mining. At a share price of CA$5.06, the stock is assessed as trading around 90.9% below an estimated future cash flow value of CA$55.69. That points to a wide gap between earnings based pricing and cash flow assumptions that investors need to reconcile.
Look into how the SWS DCF model arrives at its fair value.
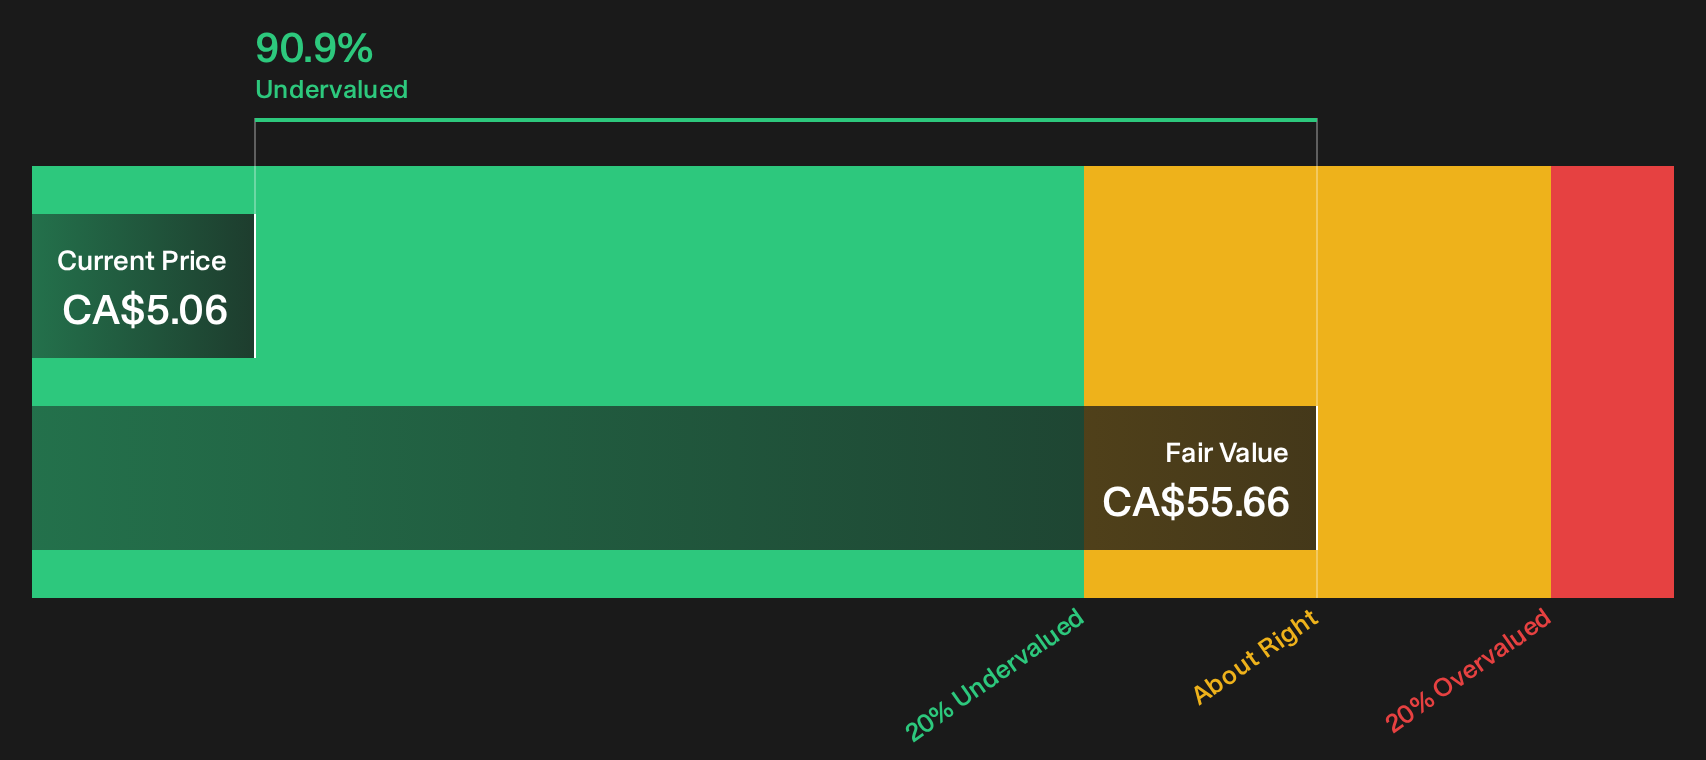
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out Hemlo Mining for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 5 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
Mixed signals on Hemlo Mining’s valuation and risks can feel messy, so move quickly to review the full data set, stress test your own assumptions, and weigh both the concerns and potential upsides highlighted in the 4 key rewards and 2 important warning signs.
Looking for more Hemlo Mining sized opportunities?
If Hemlo Mining feels interesting but not quite enough for a full position, use this moment to widen your universe before the next move passes you by.
- Target steadier compounding ideas by scanning companies that score well on balance sheet strength and fundamentals through our list of solid balance sheet and fundamentals (6 results).
- Hunt for mispriced potential by reviewing a curated 9 high quality undiscovered gems that combine quality fundamentals with limited market attention.
- Prioritise resilience by focusing on 9 resilient stocks with low risk scores that aim to keep downside risk in check while still offering room for upside.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com