


Manulife Financial (TSX:MFC) has drawn fresh attention after Manulife Bank introduced its Visa Infinite and Visa Platinum cards with the Manulife Better Rewards program, which ties credit card perks directly to health, wellness and everyday spending.
For context, the Manulife Financial share price sits at CA$64.17 after a 1 month share price return of 4.70% and a year to date share price return of 28.86%, while total shareholder return over the past year is 41.53%. Multi year total shareholder returns have also been very strong, which suggests momentum has been building as investors respond to product launches like the new Manulife Better Rewards credit cards and follow upcoming milestones such as the November 4 board meeting to review quarterly financials.
Seize this momentum in financials by scanning a curated group of resilient compounders, starting with Manulife Financial and extending across our 9 resilient stocks with low risk scores.Bulls point to Manulife Financial’s strong recent run and fresh product traction, while bears focus on whether the valuation already prices that in. Which side do the current numbers lean toward as we value the stock next?
Most Popular Narrative: 2% Undervalued
Manulife Financial closed at CA$64.17, while the most followed narrative anchors fair value at CA$65.40 using a 6.44% discount rate. This frames only a modest valuation gap and puts the focus squarely on the earnings mix story behind that number.
The earnings mix is continuing to shift toward fee based and protection businesses, with Global WAM already reporting a 31.2% core EBITDA margin and legacy LTC and VA together contributing comfortably less than 10% of earnings, which can support more capital-light earnings and steadier net income.
See why 146 investors see Manulife Financial as 2% undervalued.
Result: Fair Value of CA$65.40 (UNDERVALUED)
Still, that fair value gap for Manulife Financial depends on strength in Asia and fee income offsetting pressure from lower returns on alternative assets and Canada group disability claims.
Find out about the key risks to this Manulife Financial narrative.
Another View: What Manulife’s P/E Implies
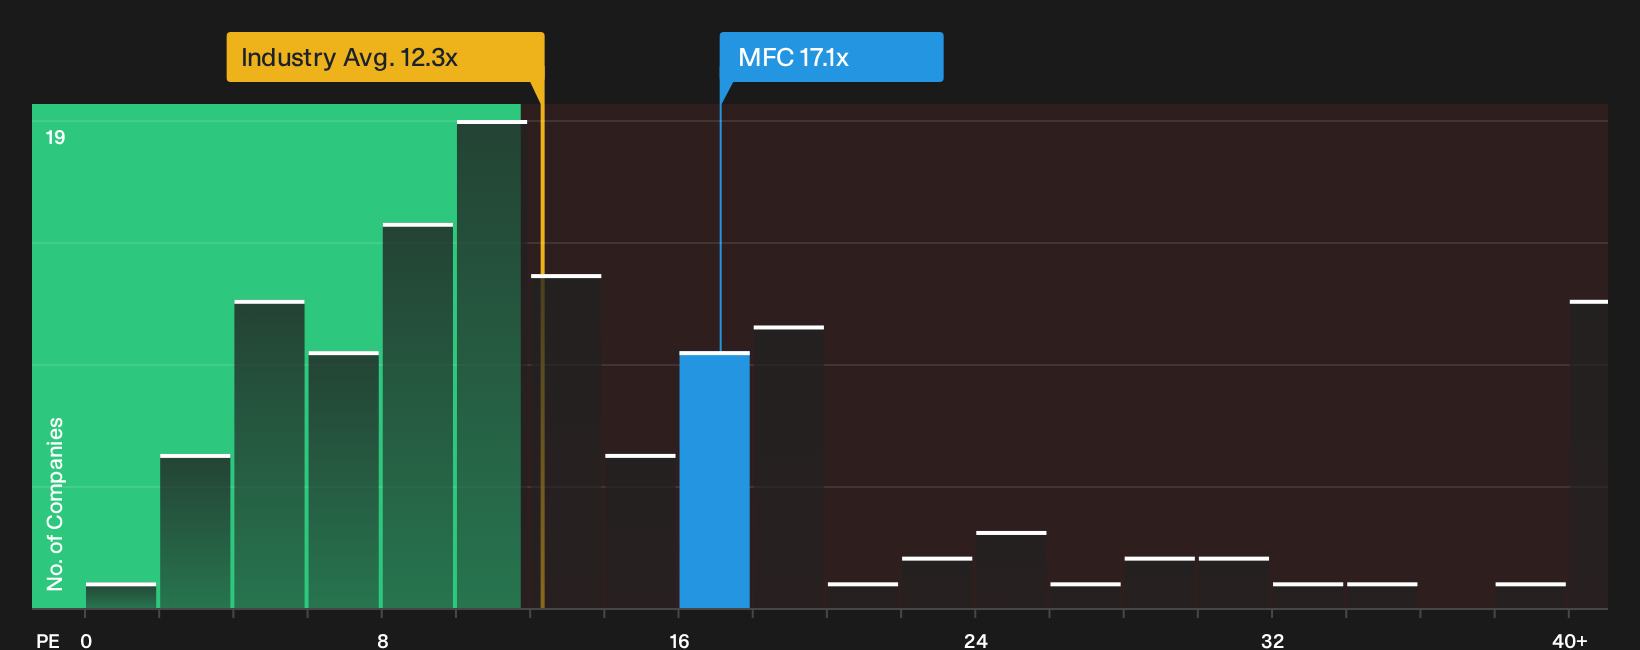
On a simple P/E check, Manulife Financial looks pulled in two directions. The stock trades at 17.1x earnings. That is richer than the North American insurance sector at 12.3x, yet lower than close peers at 19.9x and above a fair ratio of 15.5x suggested by regression work.
This mix of a premium to the wider industry, a discount to peers and a P/E above the fair ratio points to real execution risk if profit delivery softens, but also leaves some room if earnings stay resilient. Which side of that trade off feels more realistic to you right now?
See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Sentiment on Manulife Financial in this piece leans cautiously optimistic, so check the underlying data now and pressure test the thesis for yourself. To see which potential upsides investors are focusing on, review the 4 key rewards.
Looking for more investment ideas beyond Manulife Financial?
If you stop with Manulife Financial, you risk missing other businesses with similar strengths, fresh catalysts and different drivers that could complement your portfolio.
- Target stability by reviewing a curated list of solid balance sheet and fundamentals (6 results) that highlights companies built on stronger financial foundations and cleaner fundamentals.
- Hunt for mispriced opportunities through the 9 high quality undiscovered gems that surfaces lesser known businesses with robust underlying metrics.
- Sharpen your income focus with the 3 dividend fortresses to see stocks combining higher yields with an emphasis on resilience.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com