


- Huhtamäki Oyj released third quarter 2026 results, reporting €1,017.8 million in sales and €59.9 million in net income, with basic EPS from continuing operations of €0.57.
- The nine month figures show slightly lower sales year on year but higher net income and EPS, which indicates improved profitability despite a flat top line.
- We will now consider how Huhtamäki Oyj's higher earnings per share may influence the investment narrative that investors have been using.
Scan Huhtamäki Oyj's latest earnings shift against a curated field of packaging and consumer-goods peers by checking stocks with a list of solid balance sheet and fundamentals (196 results) that warrant a closer look.
Huhtamäki Oyj Investment Narrative Recap
To own Huhtamäki Oyj, you need to believe that steady packaging demand, a mix shift toward higher value fiber and flexible solutions, and disciplined capital spending can support earnings even when volume is sluggish. The latest quarter fits that thesis. Sales were flat to slightly higher and earnings per share inched up, which keeps the focus on execution rather than a sharp demand recovery.
For the next year, the key swing factor is still Huhtamäki Oyj's ability to keep offsetting raw material, energy and logistics costs through pricing and efficiency. The main risk remains that soft Foodservice volumes, exposure to more fragile regions and currency moves leave reported net income leaning heavily on cost savings. This print does not materially change that balance.
Among recent data points, the nine month 2026 figures are most relevant to this earnings update. Sales of €2,973.6 million were slightly lower than a year earlier, yet net income rose to €153.7 million and basic EPS from continuing operations moved to €1.46 from €1.30. That pattern supports the idea that Huhtamäki Oyj is still relying on margin work rather than broad based volume growth.
This matters for the current catalyst and risk set. Efficiency and higher value mix can support EPS in the short term, but it keeps the spotlight on whether Foodservice and North America can eventually contribute healthier top line trends. If raw material or currency pressures intensify while volumes stay muted, the recent earnings progress could prove harder to sustain.
Huhtamäki Oyj's current analyst narrative points to revenues of €4.6 billion and earnings of €309.9 million by 2029, based on 5.0% yearly revenue growth and an earnings increase of about €100.8 million from €209.1 million today.
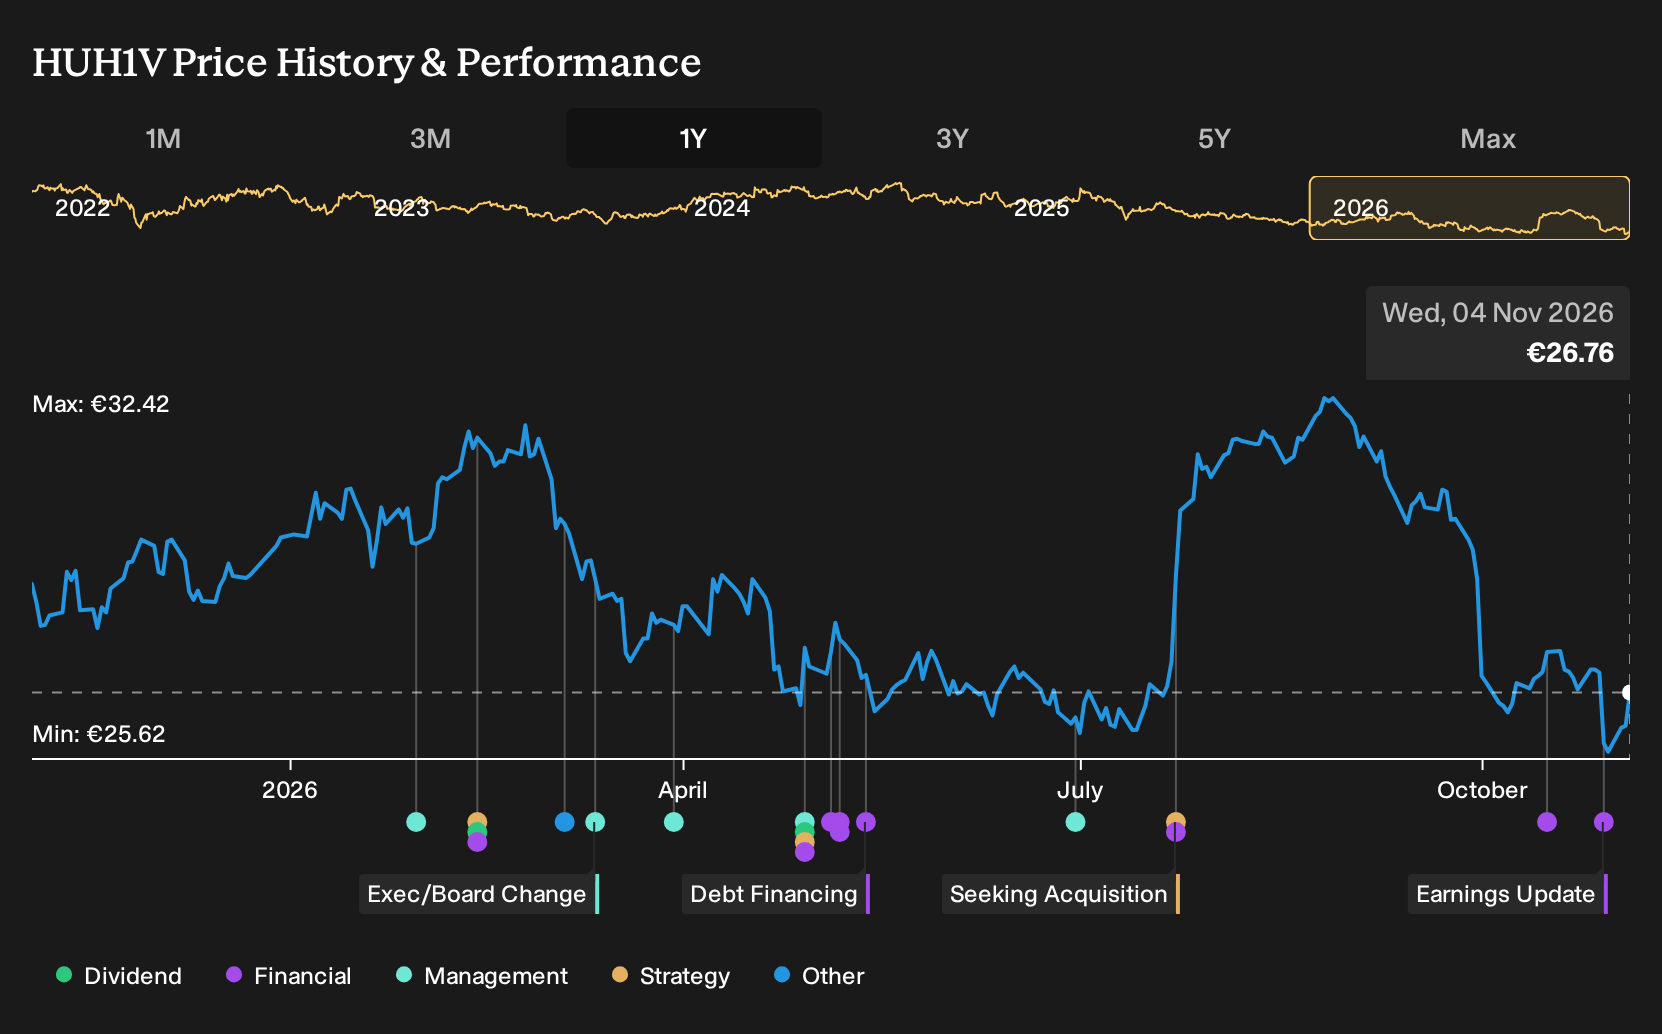
Uncover why Huhtamäki Oyj's fair value indicates a 24% potential upside to its current price, which could narrow quickly.
Exploring Other Perspectives
Four fair value estimates from the Simply Wall St Community span roughly €32 to €61, so retail opinions on Huhtamäki Oyj are clearly spread out. Before the latest earnings, some members saw deep upside while others priced in far more caution. When you factor in risks around weak Foodservice demand and currency swings, you get a wider set of possible earnings paths. That is exactly why it helps to review several community viewpoints rather than anchor on a single target.
Explore 3 other Huhtamäki Oyj fair value estimates, including one that suggests as much as 128% potential increase from the current price.
Reach Your Own Conclusion
Don't just follow the ticker; dig into the data and build a conviction that's truly your own.
- A great starting point for your Huhtamäki Oyj research is our analysis highlighting 6 key rewards and 1 important warning sign that could impact your investment decision.
- See our latest analysis for Huhtamäki Oyj. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Huhtamäki Oyj's overall financial health at a glance.
Looking for more Huhtamäki Oyj style investment ideas?
If Huhtamäki Oyj fits the kind of balanced, fundamentals led story you are building, it makes sense to scan for other businesses with similar qualities using the Simply Wall St Screener.
- For investors who care most about steady finances and durable balance sheets, start with a list of solid balance sheet and fundamentals (196 results). This helps weed out weaker profiles before you even begin your deeper research.
- If value is your anchor and you want to focus on quality companies trading below their estimated worth, use a 193 high quality undervalued stocks to surface ideas where fundamentals and pricing may be out of sync.
- Income focused readers who want yield without ignoring resilience can turn to a 216 dividend fortresses, which highlights payers combining higher distributions with robustness.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com