


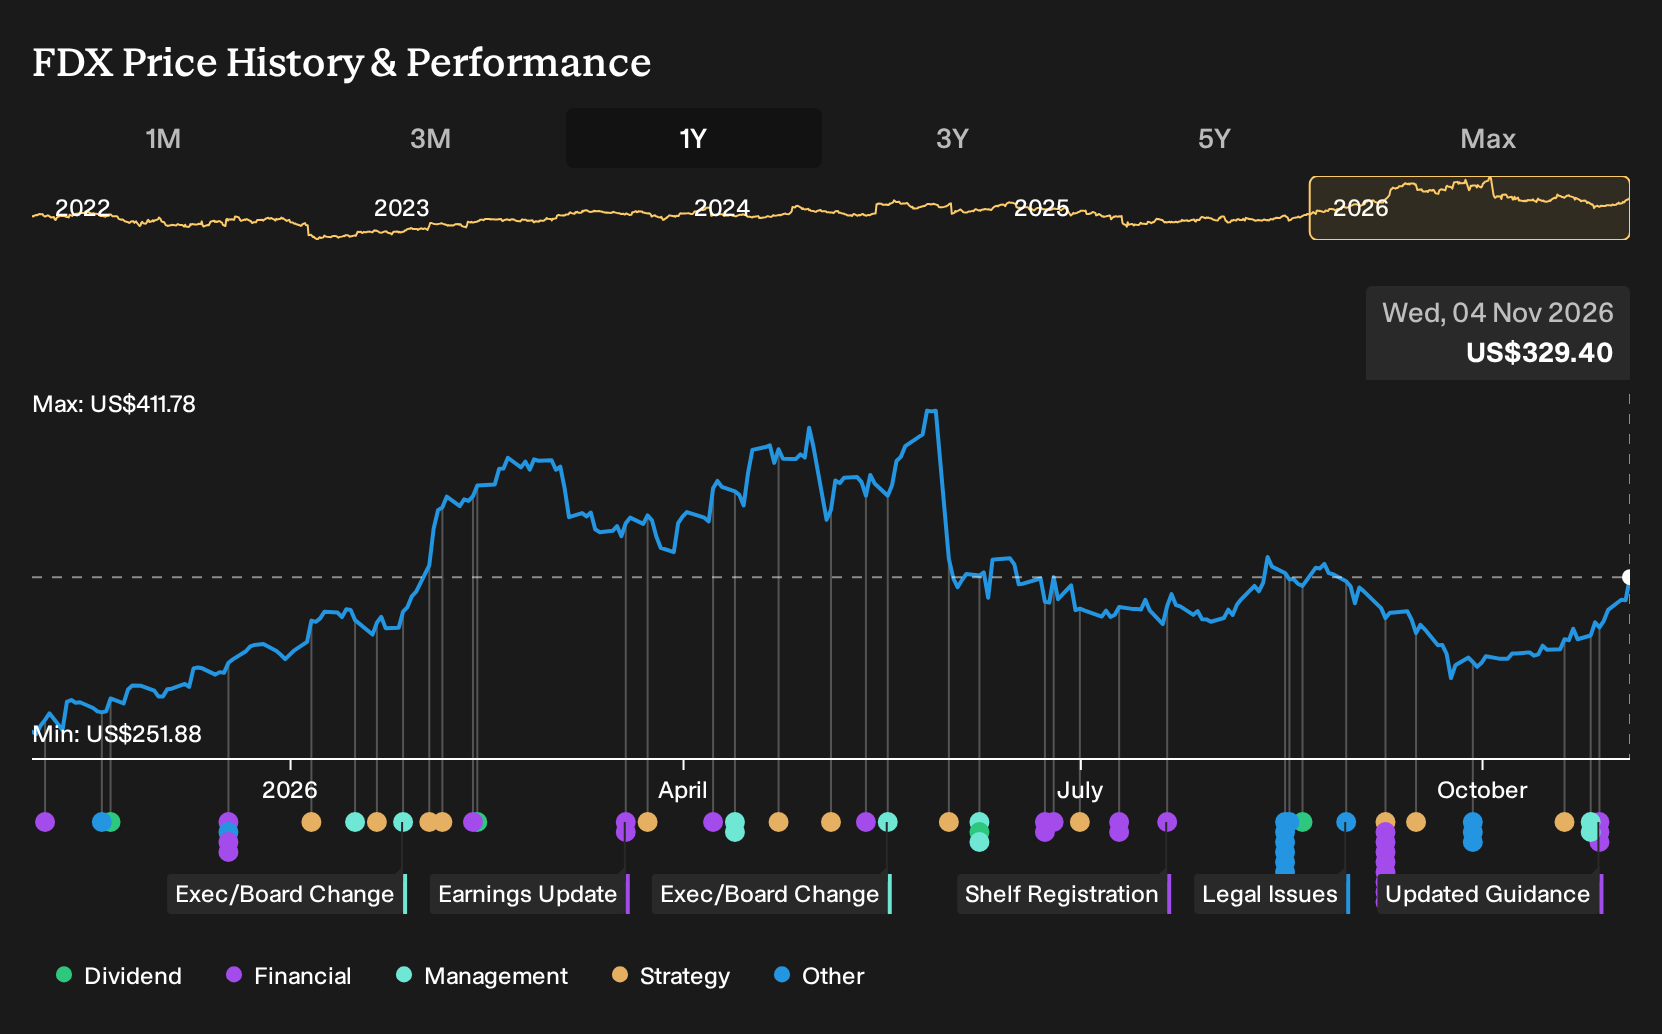
If one moment summed up recent FedEx headlines, it was the $300m order for 2,000 electric trucks from Harbinger Motors, a concrete bet on cheaper fuel and lower emissions in the delivery fleet. For FedEx shareholders, the return over the past year was 62.4%, including dividends. If you were deciding back on 2025-11-04, how confident would you have been that contracts like that would outweigh rising costs and new rivals such as Amazon Supply Chain Services?
On Simply Wall St, a Narrative is an investor's thesis written down: the reasoning, plus the numbers it rests on. Run those numbers and you get an estimated Fair Value.
The easy part of this move is behind FedEx. Zero in on 33 high quality undervalued stocks for companies trading below our estimates.
The Argument FedEx Investors Were Weighing Up
The shares cost US$252 at the start of the period, so any investor looking at FedEx had to decide whether that lined up with their own story of where the business could go next.
The bullish Narrative put Fair Value at US$320, 27% above the start price. It leaned on the DRIVE and Network 2.0 programs, with backers expecting large structural cost savings and margin gains as more global volume flowed through optimized facilities.
The bearish Narrative pointed to a Fair Value of US$200, 21% below the start price. That view focused on risks from rising labor and environmental costs, together with intensifying competition from e-commerce giants and low cost carriers that could keep long term parcel yields under pressure.
What The FedEx Evidence Put To The Test
The FedEx Freight spin off, Supply Chain sale to CMA CGM and over US$1b in Network 2.0 savings all leaned toward the optimistic cost saving story. Amazon Supply Chain Services entering the field and insider share sales pulled the other way and kept pressure on the cautious case. Overall the evidence cut both ways.
The decision in 2025 really hinged on whether FedEx could offset rising labor and fuel costs. For a different stock, you would test that same claim by tracking reported restructuring savings next to new wage agreements and energy spending line items each year.
What FedEx’s 62% Run Already Prices In
FedEx now trades at US$329 after a 62.4% gain over the past year, while the selected Narrative’s Fair Value sits below that level. Its argument focuses on pressure from fuel, labor and decarbonization spending, as well as expectations that DRIVE, Network 2.0 and Dataworks can keep margins and cash generation on track.
A buyer today is effectively assuming FedEx can turn efficiency programs and pricing power into resilient free cash flow with about 4% capex to revenue. The question the selected Narrative raises is how that assumption holds up if higher energy costs and required fleet investment reduce those planned savings.
"The main factor that needs to go right is that FedEx converts its AI, Dataworks and Network 2.0 efficiency programs, along with lower capital intensity, into durable surcharge capture, a healthier mix toward premium B2B and health care, and sustained free cash flow at approximately 4% capex to revenue."
The price and this Narrative do not agree. → Uncover what this Narrative says FedEx is actually worth
Where FedEx’s Question Leads Next
FedEx’s story turns on who captures the value in moving goods. Your next step could be asking who controls the match between demand and available vehicles.
One platform business is wrestling with that puzzle in passenger trips, food delivery and freight. It must decide how much to spend to keep its network central as vehicles become more automated.
Instead of sorting parcels, this operator coordinates drivers, couriers and trucks across cities. The crucial asset is not the vehicles themselves, but the repeat customer relationships and routing data.
If automation reshapes transport economics, that digital gatekeeper role could shift. You can decide whether this kind of marketplace gains power or ends up paying more just to stay in the game.
The case is on the record, with the assumptions it rests on. → See the Narrative that values this company 66% above its price
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com