


Compass Group (LSE:CPG) has rolled out AirisOne, an AI powered managed services platform designed to simplify facility operations and coordinate support across sectors such as education, manufacturing, healthcare, and data centers.
Compass Group shares have picked up pace recently, with a 1 month share price return of 15.93% and a year to date share price return of 9.09%, while longer term total shareholder returns of 43.02% over three years and 75.21% over five years point to sustained value creation. The latest 2.54% 1 day and 2.60% 7 day share price returns, alongside October’s AirisOne launch and the recent board change announcement for 2027, indicate that investors may be reassessing both Compass Group's growth potential in digital services and its governance profile in the context of that track record of total shareholder returns.
Scan how Compass Group’s push into AI managed services compares with other contractors leaning into similar themes by reviewing our hand picked 53 AI infrastructure stocks across listed markets.
After a sharp run in Compass Group’s share price and a wide spread between the current US$34.35 level, analyst targets and intrinsic estimates, where does a reasonable view of fair value actually land now?
Most Popular Narrative: 10% Undervalued
Compass Group’s most followed narrative pegs fair value at $38.06, a little above the last close at $34.35. This frames the recent AI push and contract momentum as key to that gap.
The early position in the AI and data center ecosystem, where Compass Group already serves most of the large outsourcing technology clients and has secured a couple of hundred million dollars of data center contracts in the last 9 to 12 months within an emerging US$10b to US$20b subsector, could add a new stream of long duration revenue and support profit growth as that work ramps.
See why 23 investors see Compass Group as 10% undervalued.
Result: Fair Value of $38.06 (UNDERVALUED)
Still, if net new business remains closer to 4% and leverage stays above Compass Group’s 1x to 1.5x target range, that 10% undervaluation narrative could fade.
Find out about the key risks to this Compass Group narrative.
Another View on Compass Group’s Valuation
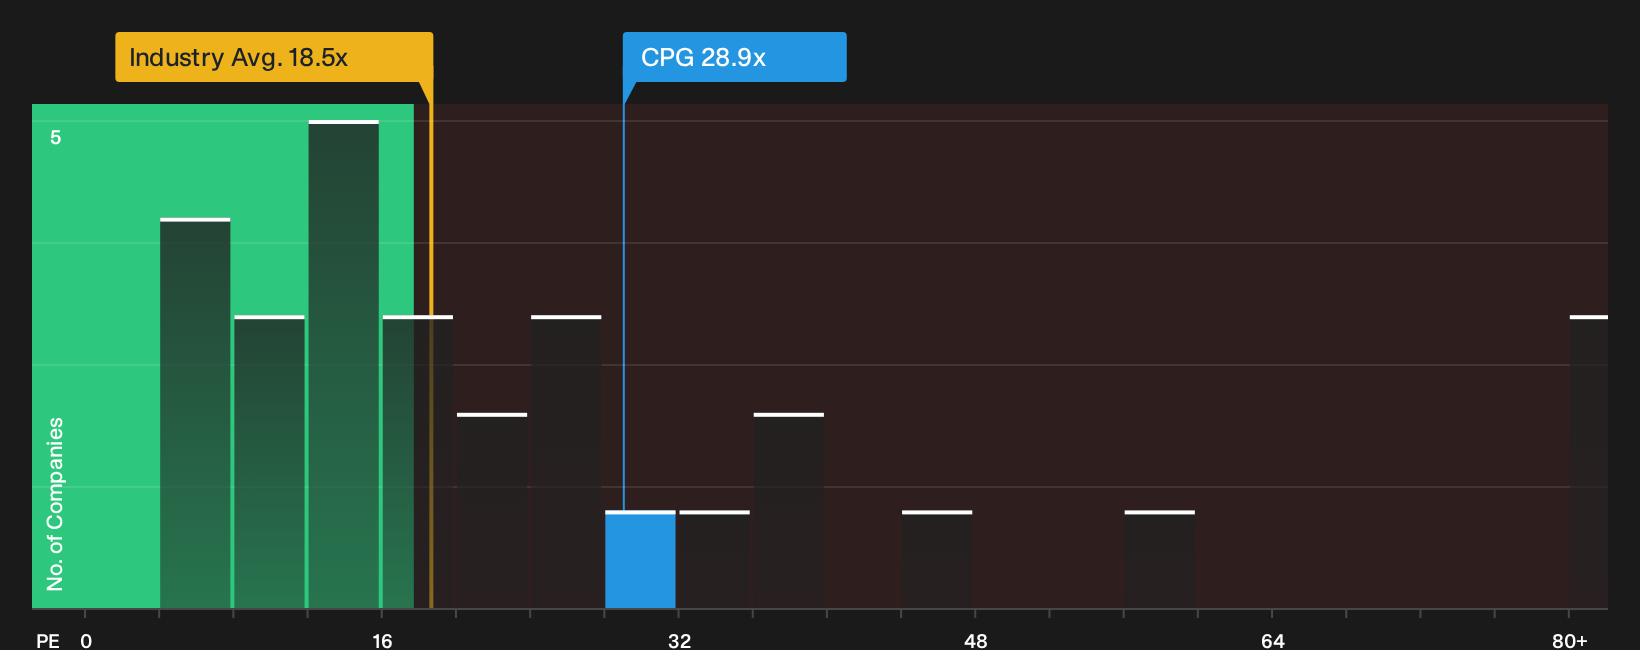
The popular Compass Group story leans on a fair value of $38.06 and calls the shares about 10% undervalued. Look at the P/E though and you get a very different feel. The stock trades on 28.9x earnings, compared with 18.5x for the UK Hospitality group and 15.3x for peers, while the fair ratio sits at 30.5x. That gap points to a premium price with only a small valuation cushion. How comfortable are you paying up for this growth path?
Before leaning on that relative pricing, it is worth seeing how the numbers stack up and where the pressure points really sit in the valuation story for Compass Group. Then you can weigh that against your own expectations for growth and margins over the next few years. See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Mixed on Compass Group after all that, or feeling the story is only half told? Act while the facts are fresh and weigh both sides yourself, starting with the 2 key rewards and 1 important warning sign.
Looking for more Compass Group sized ideas?
Compass Group is only one option. If you stop here, you risk missing other opportunities that could fit your style and risk tolerance even better.
- Target potential mispricing by scanning a curated 14 high quality undervalued stocks that filters for quality businesses trading below their estimated worth.
- Prioritise resilience by reviewing a 5 resilient stocks with low risk scores designed to highlight companies with steadier risk profiles and fewer red flags.
- Hunt for lesser known opportunities by running through a 5 high quality undiscovered gems focused on strong fundamentals that the broader market may be overlooking.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com